Most homeowners know they have homeowners insurance.
But if you asked, “What exactly does your policy cover?” the answer might be a little harder.
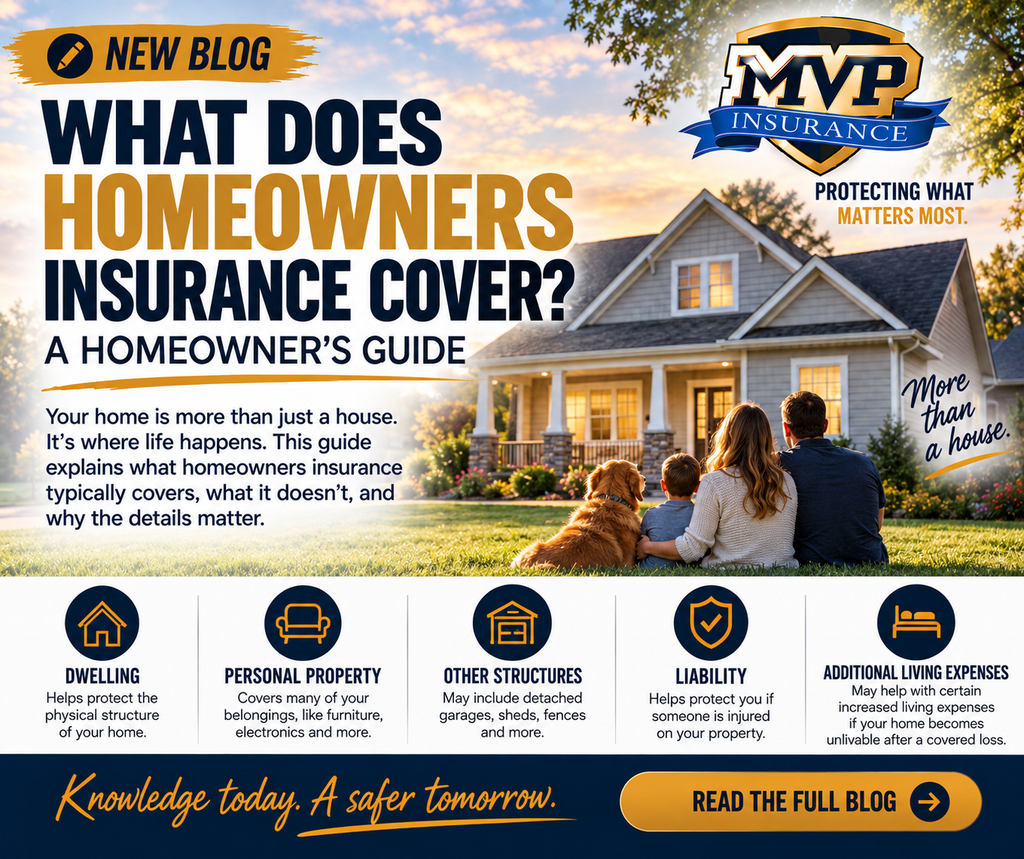
Your home is probably one of your largest financial investments, but homeowners insurance protects more than just the house itself. Depending on your policy, it may also help protect your belongings, provide liability protection, cover other structures on your property, and help with additional living expenses after certain covered losses.
Understanding those pieces before something happens can make a big difference.
Key Takeaways
- Homeowners insurance generally includes several different types of protection—not just coverage for the house itself.
- A typical policy may include coverage for your dwelling, other structures, personal property, liability, and additional living expenses.
- Your coverage limits, deductibles and endorsements can significantly affect your protection.
- Flooding, normal wear and tear, maintenance issues and certain other causes of damage generally aren’t covered by a standard homeowners policy.
- Every policy is different, so it’s important to understand what your specific policy covers.
What Does Dwelling Coverage Protect?
Dwelling coverage is the part of your homeowners policy designed to protect the physical structure of your home from covered causes of loss.
Depending on your policy, that may include damage caused by events such as fire, wind, hail and certain other sudden losses.
One important point: your home’s insurance value isn’t necessarily the same as its market value.
Your dwelling limit is generally based on what it could cost to rebuild the home—not what someone would pay to purchase the property.
That’s why changes such as additions, renovations or major upgrades are worth discussing with your insurance agent.
Related MVP article: Replacement Cost vs. Market Value: What’s the Difference?
What About a Damaged Roof?
Roof claims are a great example of why the cause of the damage matters.
If a storm damages your roof, homeowners insurance may provide coverage depending on the circumstances and your policy.
But a roof that simply deteriorates after years of use is different.
Insurance is generally designed for covered losses—not routine maintenance or replacing something simply because it has reached the end of its useful life.
Related MVP article: Will Homeowners Insurance Pay to Replace My Roof?
Does Homeowners Insurance Cover Water Damage?
Sometimes—but again, the cause matters.
A sudden plumbing problem may be treated very differently than water that has slowly leaked for months.
Sewer or drain backup may require additional coverage, and flood damage is generally not covered by a standard homeowners insurance policy.
That’s why simply asking, “Is water damage covered?” doesn’t tell the whole story.
The better question is:
“What caused the water damage?”
Related MVP article: Does Homeowners Insurance Cover Water Damage? It Depends on What Caused It.
Are My Personal Belongings Covered?
Homeowners insurance typically includes personal property coverage for belongings such as:
Furniture, clothing, electronics, appliances and many of the everyday items inside your home may fall under this portion of the policy, subject to your policy’s terms, limits and exclusions.
Certain valuable items—such as jewelry, collectibles, firearms, fine art or other high-value property—may have special limits.
That’s another reason we encourage homeowners to maintain a home inventory.
Trying to remember everything you owned after a major fire or loss would be incredibly difficult.
Related MVP article: Why Every Homeowner Should Have a Home Inventory.
What Are “Other Structures”?
Your house may not be the only structure on your property.
Depending on the policy, homeowners insurance may also provide coverage for structures that are separate from the home, such as a:
- Detached garage
- Shed
- Fence
- Gazebo
Coverage varies, and certain structures or uses of those structures may need to be discussed specifically with your agent.
What Happens If Someone Gets Hurt at My House?
Homeowners insurance isn’t only property insurance.
It generally includes personal liability protection as well.
For example, suppose a guest is injured on your property and you’re found legally responsible. Your homeowners liability coverage may help with certain covered expenses or legal costs, subject to the policy’s terms and limits.
This is also where your overall liability protection becomes important.
For households with significant assets or higher liability exposure, an umbrella policy may provide additional liability protection above the limits of certain underlying policies.
Related MVP article: Do I Need Umbrella Insurance?
What If My House Becomes Unlivable?
Imagine a covered fire causes enough damage that you can’t live in your house while repairs are being completed.
Where would you stay?
How would you handle additional expenses?
Homeowners policies generally include some form of additional living expense or loss-of-use coverage, subject to policy limits and terms.
That coverage may help with certain increased living expenses resulting from a covered loss while your home is being repaired.
It’s an important part of homeowners insurance that many people don’t think about until they need it.
What Doesn’t Homeowners Insurance Cover?
This is just as important as understanding what it does cover.
A homeowners policy does not cover everything that can happen to a house.
Depending on the policy and circumstances, exclusions or limitations may apply to things such as:
Flooding: Flood insurance is generally separate from a standard homeowners policy.
Normal wear and tear: Insurance generally isn’t intended to pay for things that simply wear out over time.
Maintenance problems: Allowing a known problem to continue can create coverage issues.
Certain water or sewer backups: Additional coverage may be necessary.
Earth movement: Earthquake and other types of earth movement generally require separate or specialized coverage.
Other exclusions and limitations can apply as well, which is why reading and reviewing your particular policy matters.
How Do Deductibles Work?
Your deductible is the amount you’re responsible for paying toward a covered property loss before insurance responds, subject to the terms of the policy.
For example, choosing a higher deductible may lower your premium, but it also means accepting more out-of-pocket expense when a covered claim occurs.
Some policies may also have different deductibles for certain types of losses.
The goal shouldn’t automatically be to choose the lowest or highest deductible.
It should be to choose one that makes sense for your financial situation and risk tolerance.
How Much Homeowners Insurance Do I Need?
There’s no universal number that works for everyone.
Two houses with similar market values can have very different insurance needs.
Your home’s construction, size, features, replacement cost, personal property, other structures, liability exposure and additional coverages can all matter.
And your needs can change.
Renovating your kitchen, finishing a basement, adding an addition, installing a pool, purchasing expensive jewelry or making other significant changes are all good reasons to contact your agent.
The MVP Approach
At MVP Insurance, we don’t believe homeowners insurance should simply be something you buy at closing and forget about.
We want you to understand:
What you’re protecting. What your limits are. What your deductible is. What isn’t covered. And where there may be gaps.
No pressure. No confusing insurance jargon. Just practical advice to help you protect what matters most.
Final Thought
Having homeowners insurance and understanding your homeowners insurance are two different things.
You don’t need to memorize every page of your policy.
But you should understand the major protections, your limits and deductibles, and the situations where additional coverage may be worth considering.
And it’s much better to have that conversation before a claim than after one.
Have Questions About Your Homeowners Insurance?
MVP Insurance can help you review your current homeowners policy and understand how your coverage works.
Request an insurance quote from MVP Insurance
https://www.mvpins.com/quotes/
Already have insurance? Securely send us your current policy information:
https://app.usecanopy.com/c/MVPINSURANCE
“Think you might be overpaying?
Get a fast quote here: https://www.mvpins.com/quotes/”