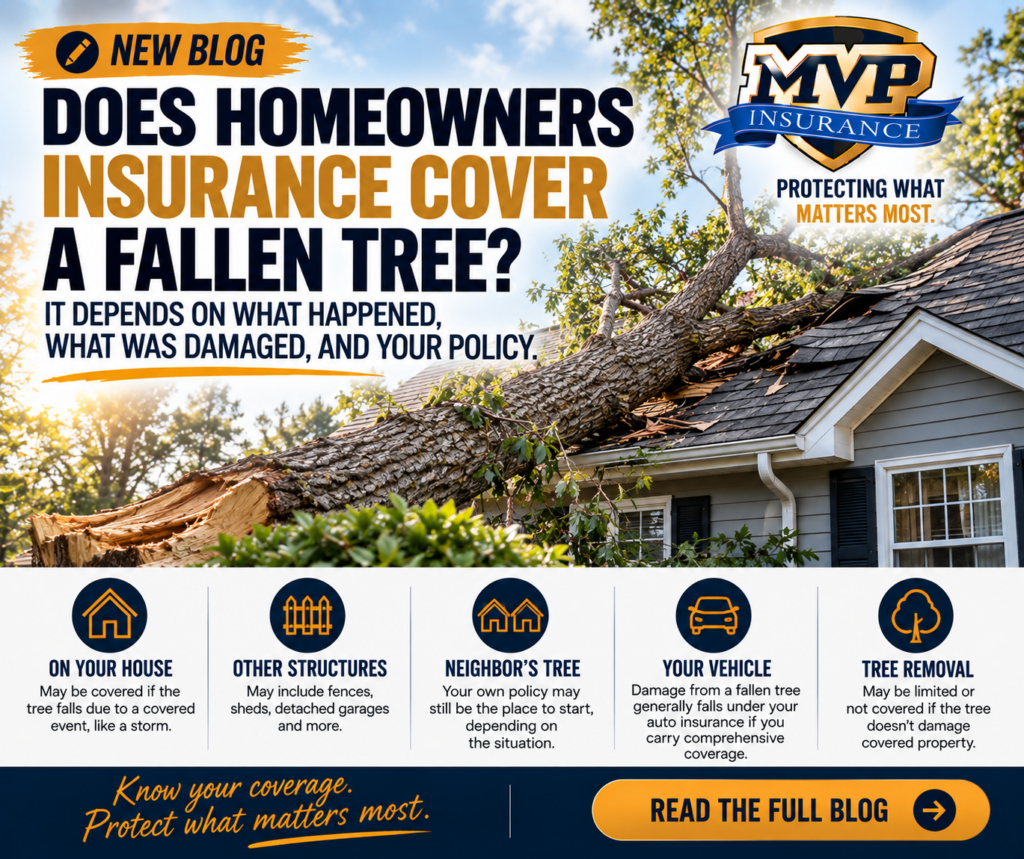
A big storm rolls through overnight.
The next morning, you walk outside and discover a tree—or a large branch—lying across your yard.
Maybe it landed on your roof. Maybe it damaged your fence. Maybe your neighbor’s tree fell onto your property.
The first question is usually:
“Will my homeowners insurance cover this?”
The answer depends on what happened, what was damaged, and the terms of your specific policy.
That’s why it helps to first understand what homeowners insurance actually covers and how the different parts of your policy work together.
Key Takeaways
- Homeowners insurance may cover damage caused by a fallen tree when the loss results from a covered event, such as certain windstorms.
- Where the tree came from isn’t necessarily the most important question. The cause of the loss and what was damaged generally matter more.
- If a tree falls without damaging covered property, tree removal may be limited or not covered, depending on the policy and circumstances.
- If your neighbor’s tree falls on your house, your own homeowners insurance may still be the place to start.
- A dead, diseased or obviously dangerous tree can create a different situation—especially if negligence is involved.
- Coverage, limits, deductibles and exclusions vary by policy.
What Happens If a Tree Falls on My House?
If a storm causes a healthy tree to fall and damage your home, your homeowners insurance may provide coverage for the resulting damage, subject to your policy terms and deductible.
For example, imagine strong winds knock a tree onto your roof.
The resulting roof damage and damage to other covered portions of the house may fall under your homeowners coverage if wind is a covered cause of loss under your policy.
There may also be coverage for certain reasonable costs associated with removing the tree from the damaged structure, subject to policy provisions and limits.
The important distinction is that insurance isn’t necessarily paying because a tree fell.
It’s responding to a covered loss that caused damage to insured property.
What If My Neighbor’s Tree Falls on My House?
This surprises many homeowners.
If your neighbor’s healthy tree falls onto your house during a storm, that doesn’t automatically mean your neighbor—or their insurance company—is responsible for your damage.
In many situations, you would start with your own homeowners insurance company for damage to your home, subject to your coverage and deductible.
Why?
Because trees can fall during storms even when nobody did anything wrong.
However, the circumstances can change if there is evidence that the tree presented a known hazard and the property owner failed to address it.
That’s where things can become more complicated.
What If the Tree Was Dead or Diseased?
Suppose your neighbor has a visibly dead tree leaning toward your house.
You’ve previously expressed concern about it.
The tree eventually falls and damages your property.
That situation may be different from a healthy tree unexpectedly falling during a major storm.
Questions about negligence and prior knowledge can become relevant.
Determining responsibility depends on the facts surrounding the loss, so it’s important not to assume who’s responsible before the circumstances are reviewed.
If you’re concerned about a dangerous tree on a neighboring property, documenting your concerns before a loss occurs can also be helpful.
What If My Tree Falls on My Neighbor’s House?
The same general concept works in reverse.
If an otherwise healthy tree on your property falls onto your neighbor’s house because of a storm, you aren’t automatically responsible simply because the tree grew on your property.
Your neighbor may begin the claim process with their own homeowners insurance.
If there are allegations that you knew—or reasonably should have known—the tree presented a dangerous condition and failed to address it, liability questions could arise.
Again, the circumstances matter.
What If a Tree Falls in My Yard but Doesn’t Damage Anything?
This is where homeowners sometimes get surprised.
Suppose a storm knocks down a tree and it lands harmlessly in the middle of your backyard.
Nothing else is damaged.
Will homeowners insurance pay to cut it up and haul it away?
Not necessarily.
Tree removal coverage can depend on whether covered property was damaged, what caused the tree to fall, where it landed, and the specific provisions and limits in your policy.
Some policies may provide limited tree-removal coverage under certain circumstances, while others may not respond when the only issue is removing a fallen tree from the yard.
Don’t assume every fallen tree automatically creates an insurance claim.
What If a Tree Damages My Fence, Shed or Detached Garage?
Your homeowners policy may protect more than your house.
Most homeowners policies include some form of other structures coverage for qualifying structures separate from the primary dwelling.
That can potentially include things such as:
- Detached garages
- Sheds
- Fences
- Gazebos
If a tree damages one of these structures because of a covered cause of loss, coverage may apply subject to your policy’s terms, limits and deductible.
This is one reason homeowners should understand how much other structures coverage they actually have.
What About My Car?
Here’s another important distinction.
If a tree falls on your vehicle, that’s generally not a homeowners insurance claim for damage to the car.
Damage to the vehicle from a falling tree would generally fall under the comprehensive portion of your auto insurance if you carry comprehensive coverage and the loss is covered.
That’s a great example of why having both home and auto policies doesn’t mean the policies cover the same things.
Should I File a Claim Every Time a Tree Falls?
If the damage appears relatively minor or may be close to your deductible, it can be helpful to understand your coverage and deductible before deciding how to proceed.
Before automatically filing a claim, consider calling your insurance agent to discuss what happened. Your agent can help you understand your coverage, deductible and the potential next steps so you can make a more informed decision.
At MVP Insurance, we believe this is one of the reasons having an insurance agent matters. When something happens, you should have someone you can call to help you understand your policy and talk through the situation.
If you’re unsure how your deductible works, understanding the relationship between your insurance deductible and your out-of-pocket cost can help you evaluate the situation.
If you have minor damage that’s close to or below your deductible, filing a claim may not make sense.
If you’re unsure, this is where talking with your insurance agent before automatically submitting a claim can be helpful.
Your agent can help you understand your coverage and deductible so you can make a more informed decision.
A Little Prevention Can Go a Long Way
You can’t prevent every storm.
But you can reduce some of the risk surrounding trees on your property.
Periodically look for things such as dead branches, visibly leaning trees, decay, damaged trunks, roots lifting from the ground or trees growing dangerously close to your home.
If something concerns you, consider having a qualified tree professional evaluate it.
Insurance is there for covered unexpected losses.
Maintenance and prevention are still the homeowner’s responsibility.
Preventive maintenance is also a good reminder to periodically review your insurance coverage as your home, belongings and property change.
The MVP Approach
At MVP Insurance, we want our clients to understand their coverage before the tree hits the house—not afterward.
That means understanding your dwelling coverage, other structures coverage, deductible, liability protection and the limitations within your policy.
And when something does happen, we’re here to help you understand the situation and determine the appropriate next step.
No pressure. No confusing insurance jargon. Just practical advice to help you protect what matters most.
Frequently Asked Questions
Who pays if my neighbor’s tree falls on my house?
Often, a homeowner starts with their own insurance when a neighbor’s tree damages their home during a storm. Responsibility can become more complicated if negligence or a known hazardous condition is involved.
Does homeowners insurance pay to remove a fallen tree?
It depends on the circumstances, including what caused the tree to fall, whether covered property was damaged, where the tree landed and the provisions of your policy.
Does homeowners insurance cover a tree falling on my car?
Damage to the vehicle would generally fall under comprehensive auto coverage rather than homeowners insurance, assuming comprehensive coverage applies to the loss.
Final Thought
When a tree falls, don’t focus only on whose tree it was. The cause of the loss, what was damaged, your policy coverage and the circumstances surrounding the event can all matter.
If you’re unsure what to do next, call your insurance agent and talk through the situation before making assumptions about coverage or responsibility.
Have Questions About Your Homeowners Insurance?
MVP Insurance can help you review your current homeowners policy and understand how your coverage works.
Request an insurance quote from MVP Insurance
https://www.mvpins.com/quotes/
Already have insurance? Securely send us your current policy information:
https://app.usecanopy.com/c/MVPINSURANCE