


Pennsylvania Builders Risk Insurance

Owner, MVP Insurance

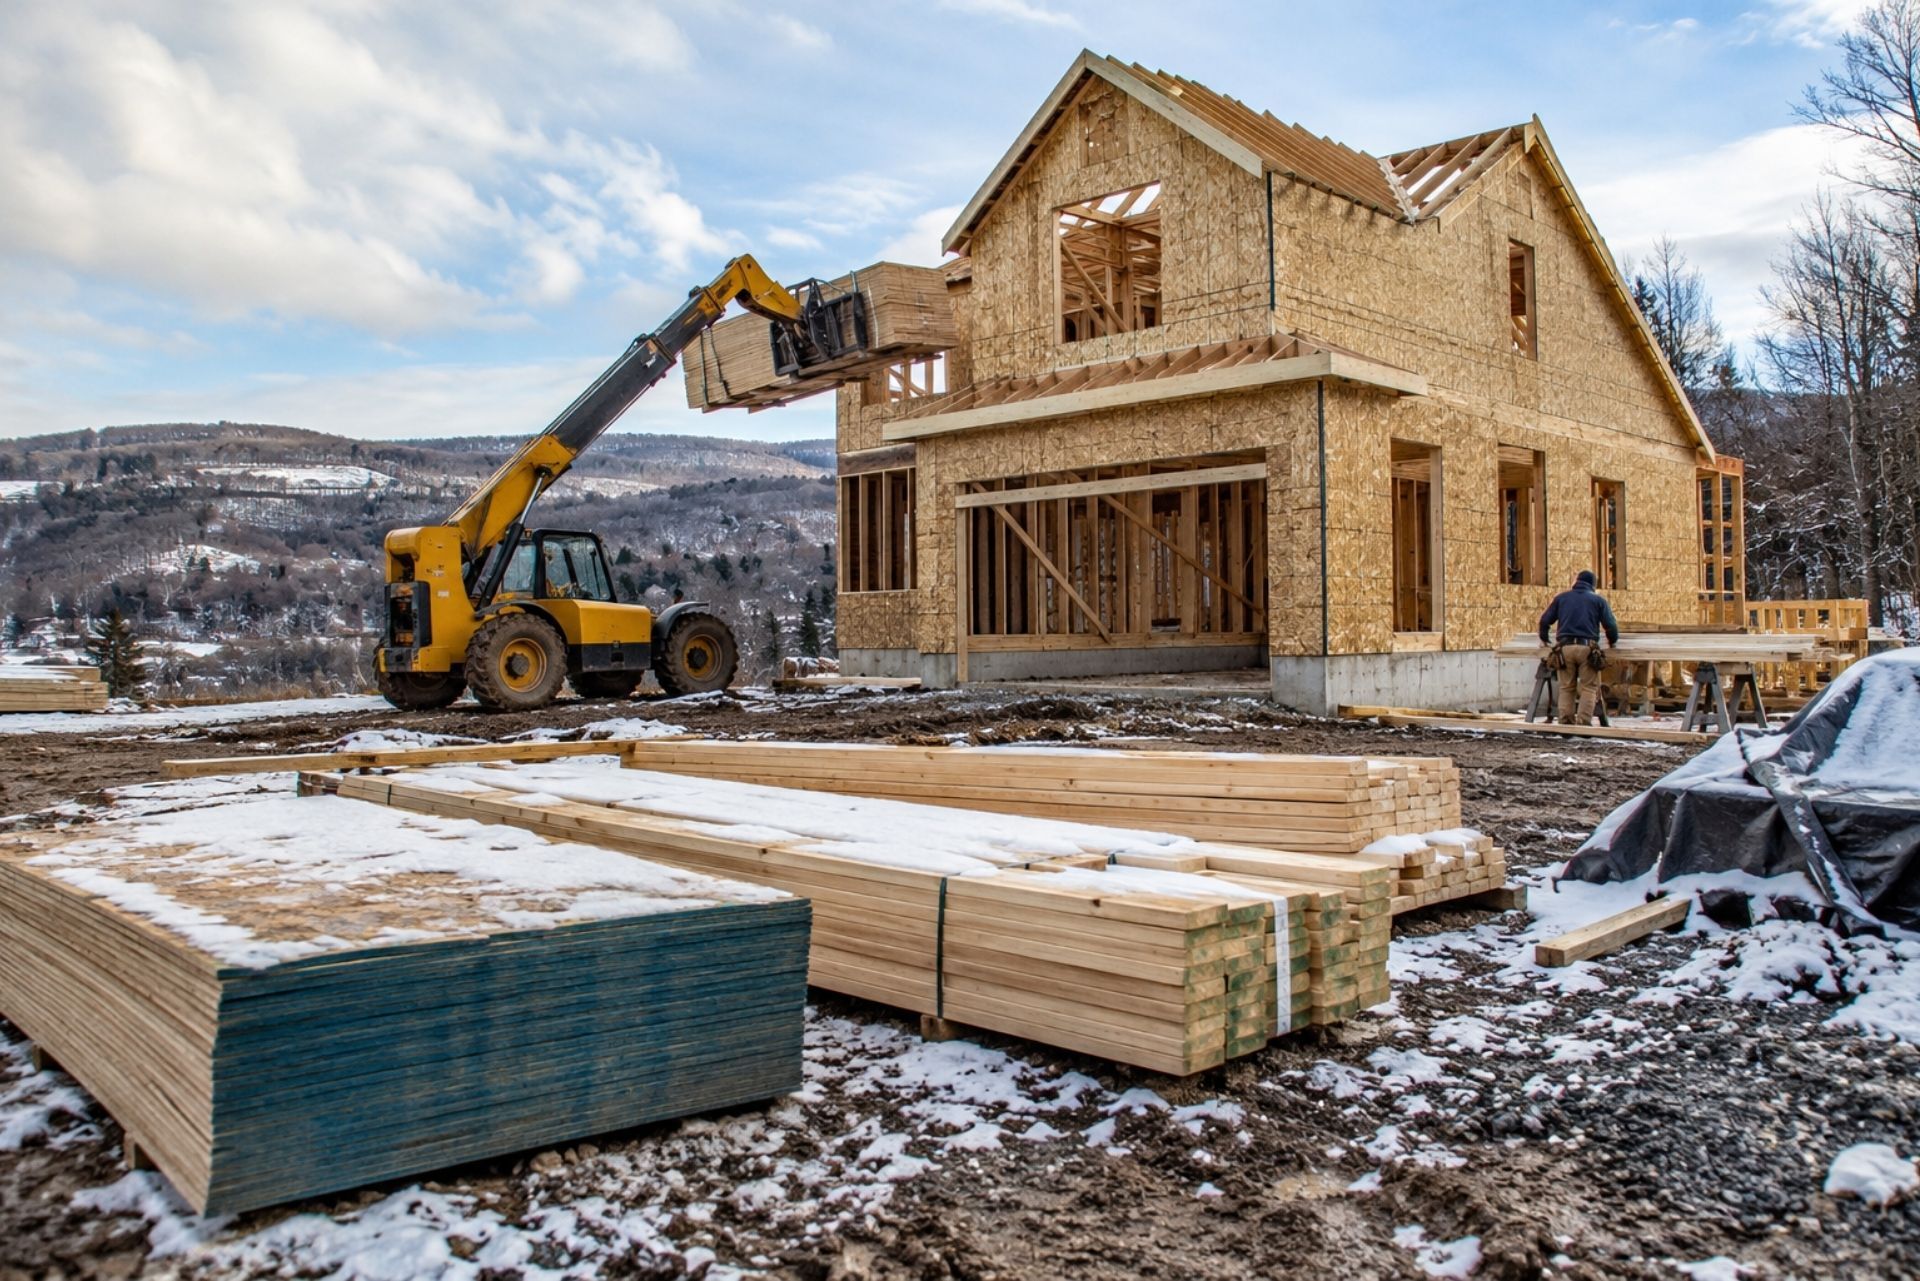
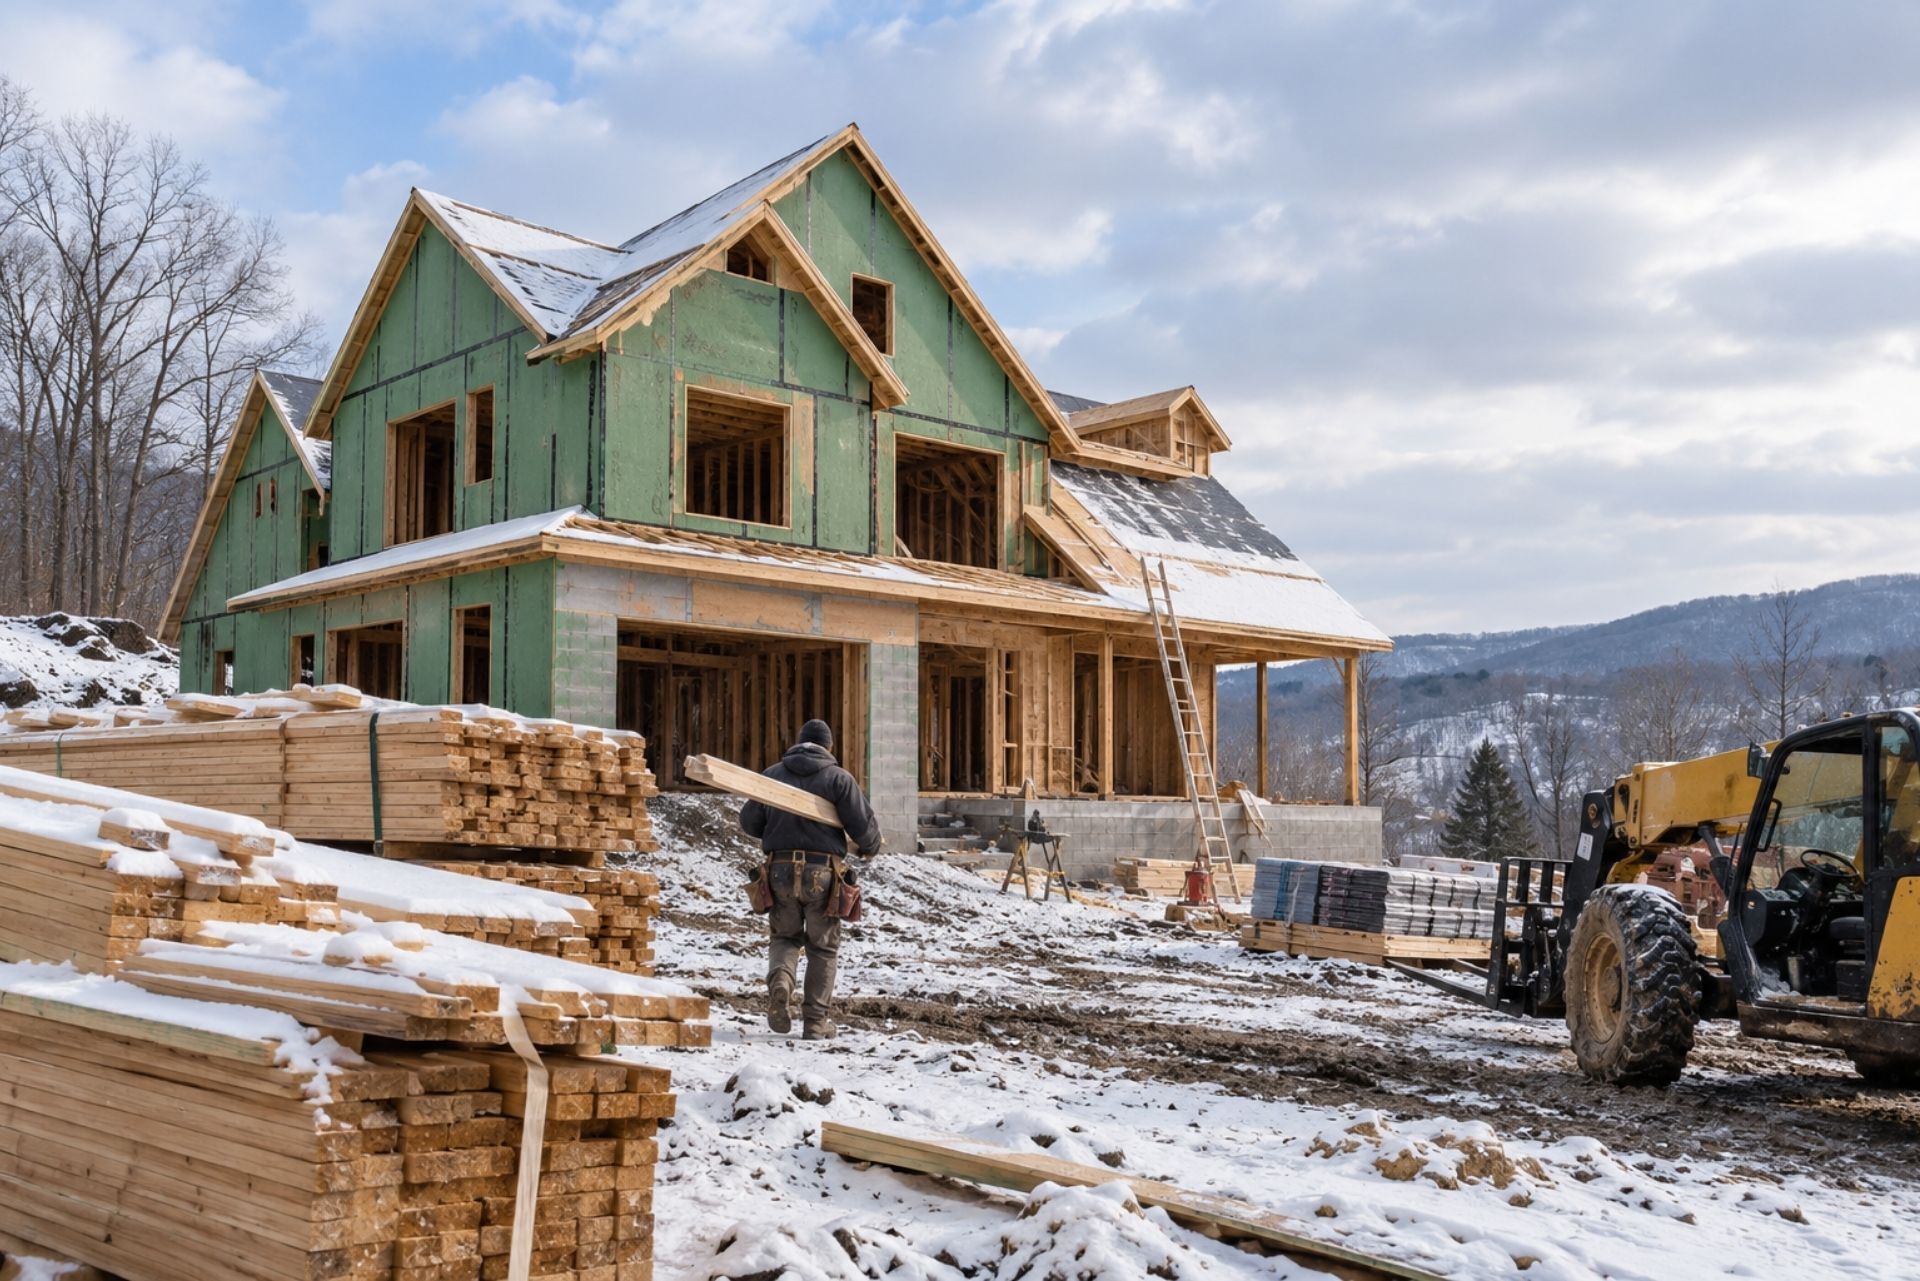
Pennsylvania builders risk insurance protects a home or commercial building while it's still going up. It covers the structure, the materials on site, and often materials in transit against fire, wind, theft, and vandalism. Coverage starts with construction and ends at completion or occupancy. Either the owner or the general contractor can buy the policy.


That short answer leaves a lot out, and the gaps are where most claim disputes start. A half-framed house in western Pennsylvania faces hazards a finished home never will: open walls, piles of copper sitting overnight, and months of freeze-thaw weather. Below, we cover what the policy actually pays for, where builders get caught off guard, and how to decide who should hold the coverage.

Protecting Pennsylvania Homes and Commercial Projects Under Construction

Builders risk coverage pays to repair or rebuild a structure damaged by fire, wind, hail, vandalism, and similar covered events during the construction phase. Your homeowners or standard commercial property policy usually won't respond to a building that isn't finished. Builders risk fills that gap from the day work begins until the project is complete.


The types of projects vary widely. MVP Insurance places coverage for residential new builds across Butler County, from custom homes on rural lots to small subdivision builds. It also covers commercial projects in Cranberry Township, where retail, office, and mixed-use construction keeps growing. A wood-frame house and a steel-frame medical office carry very different fire and wind exposures, so the rate and the form should differ too.


The most common mistake we see is setting the limit too low. The limit should reflect the full completed value of the project, including labor, not just the materials budget. If a fire hits at 80% completion and your limit only matches the original material estimate, you'll be short. For the broader commercial picture, our page on business insurance in Pennsylvaniaexplains how builders risk fits alongside liability and property coverage.

David Varrati

By: Joshua Medure

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Life

Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.

Feature DP-1 (Basic) DP-3 (Special)
Covered perils Named perils only All risks, minus exclusions
Building settlement Usually actual cash value Usually replacement cost
Sudden water damage Often excluded Usually covered
Theft/vandalism Optional, limited Typically included
Loss of rent Often optional Usually included
Liability Often an add-on Add-on or included
Best fit Older, low-value homes Most modern rentals
PA legal requirement None by state law None by state law

Coverage for Theft of Materials From Job Sites

A builders risk policy covers building materials such as copper piping, wiring, and lumber before they're installed, as long as those materials are scheduled on the policy or included in the limit. That condition matters. If a supplier drops off $18,000 in copper and framing lumber on Friday and it's gone Monday morning, the claim depends on how the policy was written.


Theft is a real exposure here. Pennsylvania's builders risk market in 2026 has been shaped by rising material theft and a complicated litigation environment.Copper is the usual target because it's easy to resell, but lumber disappears too, especially on unfenced lots.


A few things to check before materials arrive:


  • Stored materials:Confirm that on-site storage is covered, not just installed work.
  • Off-site and transit:Ask whether materials at a staging yard or on a truck are included.
  • Security conditions:Some policies require fencing, lighting, or locked storage, and a claim can be denied if you didn't meet them.
  • Theft deductibles: These are sometimes higher than the base deductible.


Contractors' tools and equipment are usually a separate coverage. Our guide to contractors insurance in Pennsylvaniacovers inland marine options for that gear.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

HCertificates of Insurance for Pennsylvania Contracts

Canopy import

Share your current policies in a few clicks through Canopy. We see exactly what you have today, so the comparison is apples to apples.

Managing Winter Weather Delays and Property Damage

Builders risk generally covers physical damage from winter weather, such as a burst pipe or ice damming that soaks new drywall. It doesn't automatically cover the money you lose when that damage pushes the project back. That second piece is called soft costs coverage, and it has to be discussed and added on purpose.


Pennsylvania winters are hard on job sites. A common scenario: a crew roughs in plumbing in December, the heat isn't running yet, temperatures drop into the teens over a weekend, and a fitting splits. The water damage claim is straightforward. The six-week delay that follows is a different matter, because it brings extra loan interest, an extended equipment rental, lost rent on a commercial unit, and re-permitting fees.


Soft costs or "delay in completion" coverage can reimburse those financial losses after a covered physical loss. It typically won't pay when a project simply runs slow because of snow days with no damage. If you're financing a Cranberry Township commercial building with tenants lined up, this coverage can matter more than the physical damage limit. Also ask about freeze-protection requirements, since some carriers expect temporary heat or drained lines.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Who Should Buy the Policy: Owner vs Contractor

Either the property owner or the general contractor can buy builders risk insurance. Owners often purchase it themselves so they control the coverage limits, deductibles, and who gets named on the policy. Your construction contract should say clearly who is responsible, and the policy should match that language.


Contractor-purchased policies are common on residential builds, where the builder may carry a blanket policy across several homes. That works, but the owner should confirm their interest is protected and that the limit fits their specific house. On larger commercial projects, owners and lenders frequently want the policy in the owner's name. Contract risk is shifting too: the Pennsylvania House passed H.B. 1541 in April 2026 to shield contractors from liability for others' negligence in construction contracts, so have your attorney review indemnity terms. MVP Insurance works with owners and contractors to sort out which setup fits the contract.

Comparison of Builders Risk Coverage Options

Factor Owner Buys Contractor Buys
Controls limits Owner Contractor
Typical project Commercial, financed builds Residential, spec homes
Lender preference Often required Sometimes accepted
Cost passed along Paid directly Built into bid
Main risk Paying for coverage you don't need Limit may not fit your project

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Frequently Asked Questions About PA Builders Risk Insurance

How much does builders risk insurance cost in Pennsylvania? In 2026, benchmark premiums range from about $0.85 to $4.20 per $100 of project value. Where your project lands in that range depends on the structure type and location, and wood frame usually costs more than masonry.


How long does builders risk coverage last? Most policies are written for the length of the project, often 3 to 12 months. They end at completion or occupancy, so ask for an extension early if the schedule slips.


Does Pennsylvania require builders risk insurance? State law doesn't require every builder to carry it, but lenders and contracts usually do. Builders risk remains subject to statutory requirements even after the state's updated filing rules for property and casualty insurance took effect in April 2026.


Can I get builders risk for a home renovation? Yes. Many carriers write renovation policies, though major remodels are rated differently from new construction.


Is the land covered? No. Builders risk covers the structure and materials, not the land value.


Who can help me locally? MVP Insurance has offices in Zelienople, PA (108 E Grandview Ave, 724-453-1122) and New Springfield, OH (13823 Grant St, 330-707-9055). You can stop in or call either one with questions.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Industry Common Per Occurrence Common Aggregate Typical Driver
Retail shop $1,000,000 $2,000,000 Commercial lease
Restaurant/café $1,000,000 $2,000,000 Lease, liquor license, events
Residential contractor $1,000,000 $2,000,000 Client and GC contracts (HICPA floor is lower)
Commercial contractor $1,000,000 $2,000,000 + umbrella GC and municipal contracts
Manufacturer $1,000,000 $2,000,000 products aggregate Distributor agreements
Office/consultant $1,000,000 $2,000,000 Client contracts, lease
Event vendor $1,000,000 $2,000,000 Venue or borough permit

Getting the Right Builders Risk Coverage in Place

A strong builders risk policy for a Pennsylvania project accounts for the full completed value, spells out how stored materials like copper and lumber are covered, and considers soft costs for winter delays. It also needs to match what your contract says about who buys it. Most claim problems come from skipping one of those steps, not from bad luck.


MVP Insurance is an independent agency, so we compare options from multiple carriers instead of steering you toward one. If you're breaking ground in Butler County or Cranberry Township, start your quotebefore the first delivery truck shows up. MVP Insurance is licensed in Pennsylvania (#519263) and Ohio (#37714), NPN 10588293.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

Joshua Medure

Owner, MVP Insurance


I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania






