


Owner, MVP Insurance
Auto
Auto insurance covers injuries and damage you cause to others, and with collision and comprehensive, your own vehicle too. Ohio and Pennsylvania set different minimums and Pennsylvania adds a tort choice, so we walk you through both before you pick limits.
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
Most Pennsylvania homeowners policies do not cover flood damage, so you need a separate flood policy through the NFIP or a private flood carrier. NFIP coverage usually takes 30 days to start. With the Ohio River, its tributaries, and creeks like the Connoquenessing running through Western PA, flood risk reaches far beyond the mapped high-risk zones.
That last point surprises a lot of people. Many buyers assume flood insurance is only for riverfront homes or properties their lender flagged at closing. Yet some of the costliest water losses we see come from a creek that "never floods," a hillside that funnels runoff into a basement, or a storm drain that backs up during a summer downpour. The average paid NFIP claim in Pennsylvania between 2017 and 2026 was $40,512. That is a figure most families would struggle to cover out of savings.
This guide walks through why your homeowners policy stops at your front door, how NFIP and private flood coverage compare, what the waiting period means for your timing, and where local flooding actually happens, from Pittsburgh's three rivers to Zelienople and Harmony.
Why Standard Homeowners Policies Exclude Flood Insurance
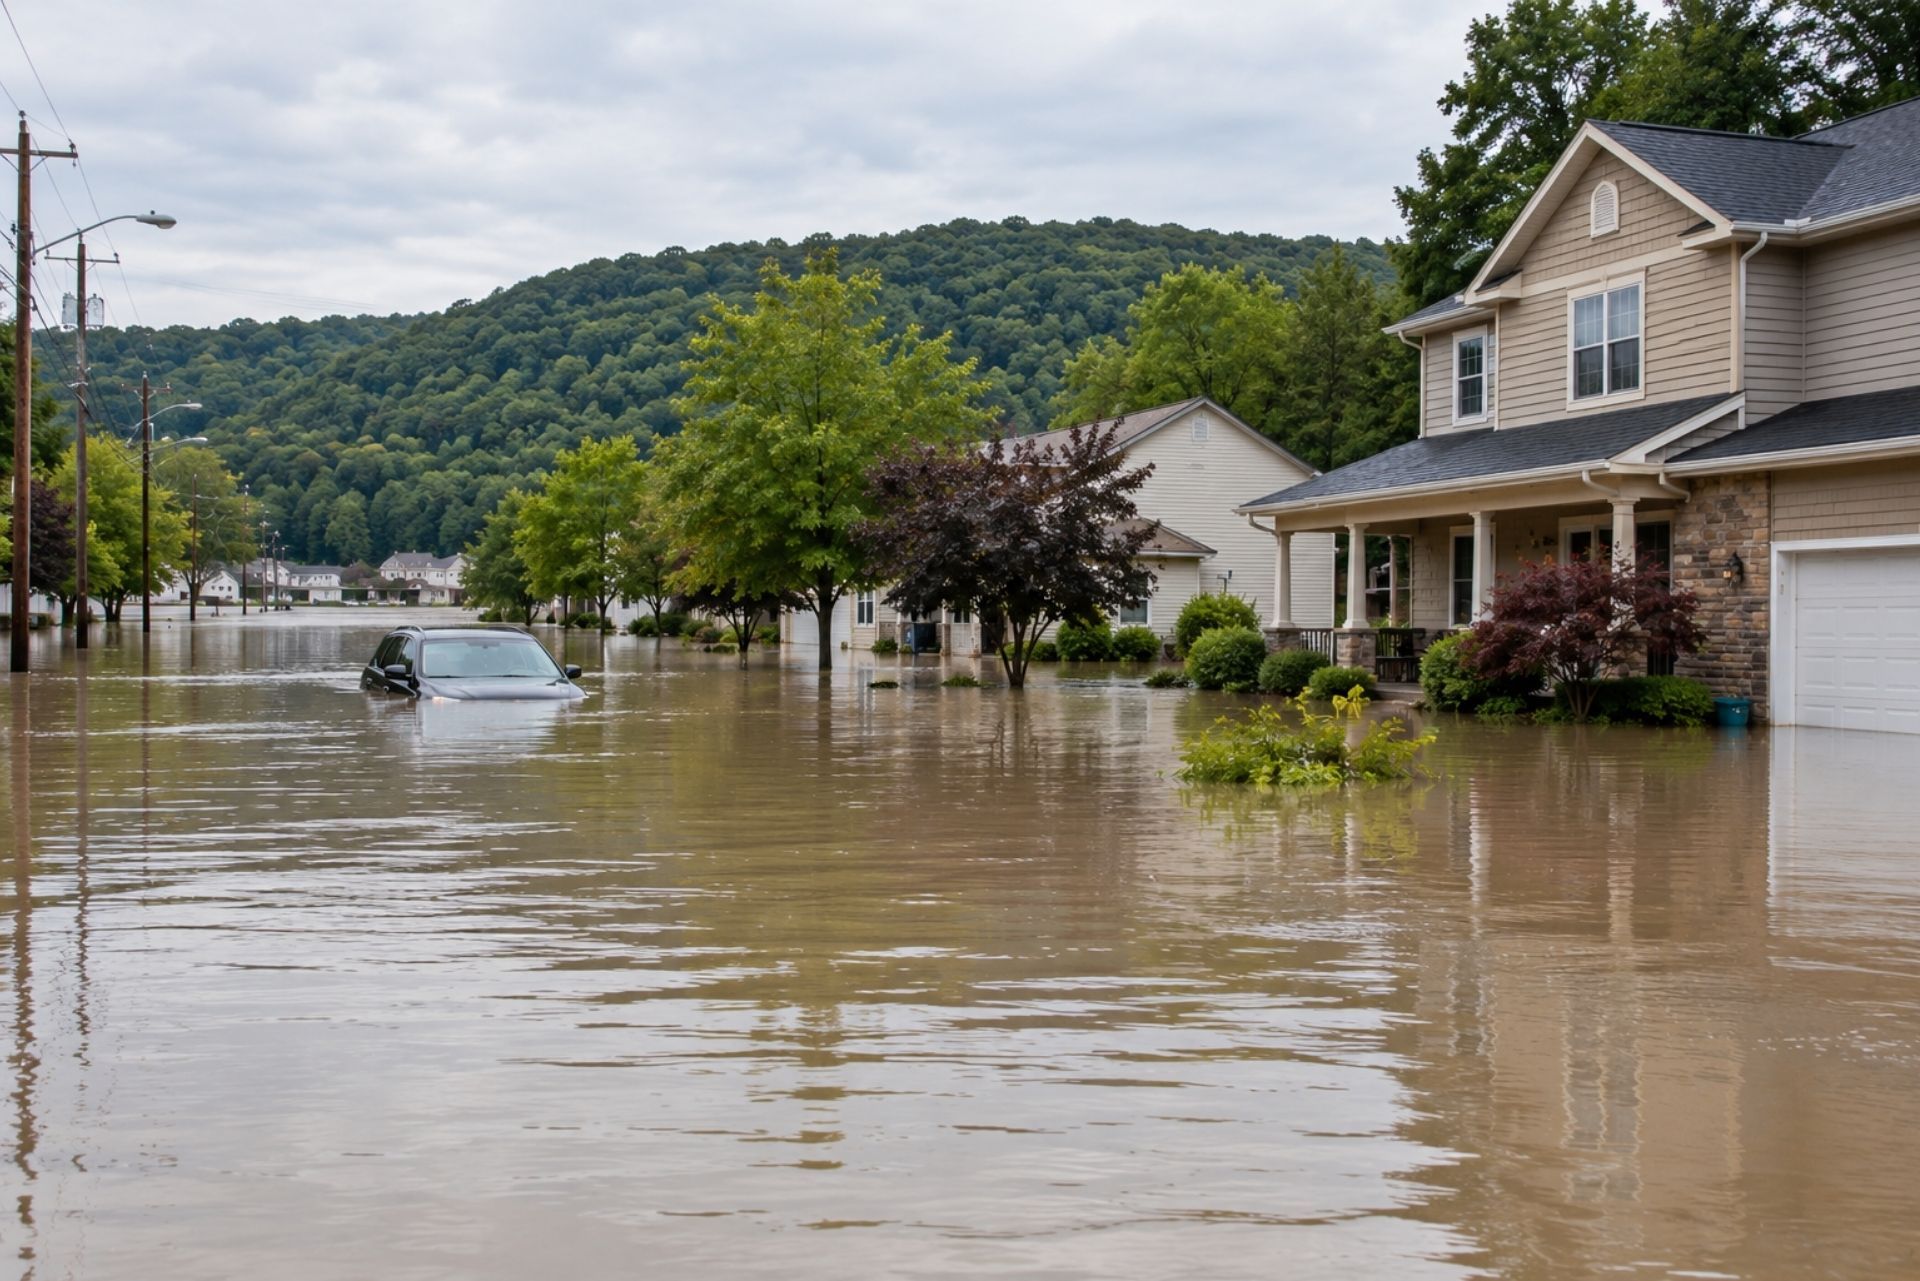
Your homeowners policy covers water that starts inside the house, but it excludes water that rises from outside. A burst supply line under the kitchen sink, a water heater that splits, or rain blowing through a storm-damaged roof are typically covered. Water that rises from the ground, overflows a creek bank, or pours down a hill and through your basement door is flood, and flood is excluded.
Insurers draw the line between "top-down" and "bottom-up" water for a reason. Flood is treated as a catastrophic risk, and bundling it into standard homeowners coverage would threaten the solvency of private insurers.One river crest can damage thousands of homes in the same week, and that concentrated loss is something ordinary homeowners pricing was never built to absorb.
Pennsylvania lawmakers are also trying to make this gap harder to miss. House Bill 1718 in the 2025-2026 session would require insurers to provide a specific Flood Disclosure format issuance or renewal stating plainly that flood is not covered. The bill's status may change, so check where it stands before relying on it.
A common mistake we see is assuming a sump pump or water backup endorsement equals flood coverage. It does not. Backup coverage handles a failed pump or a clogged drain, not surface water entering the home. You can review how your current policy handles water on our Pennsylvania homeowners insurancepage or see the full range of personal insurance options in Pennsylvania.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
NFIP vs Private Flood Insurance Options
The short answer: NFIP coverage is standardized and widely available, while private flood policies often offer higher limits and more flexible terms. Neither option fits every home, which is why we compare both.
As an independent agency, MVP Insurance works with American Bankers for NFIP policies and with Franklin Flood and Foremost for private flood options. We are not the carrier on any of these. We shop them side by side so you can see the real difference in price, limits, and deductibles for your address.
The NFIP is backed by the federal government, and its rules are the same whether you live in Cranberry or Coraopolis. In 2026, the typical yearly NFIP cost for a single-family home in Pennsylvania runs about $1,210, though your number depends heavily on elevation, foundation type, and distance from water. Private carriers price risk on their own models, and for some homes outside high-risk areas, the private quote comes in noticeably lower. For others, especially older homes close to a creek, the NFIP is the more practical route.
Private flood also tends to offer extras the NFIP limits or skips, such as additional living expenses while you are displaced, or broader coverage for finished basements. Ask about each of these specifically, because private policies vary from carrier to carrier.
Comparing Flood Insurance Coverage Limits
Coverage limits are where the two options separate most clearly. Figures below reflect general NFIP residential maximums; confirm current limits at the time of purchase.
| Coverage | NFIP (residential) | Private Flood |
|---|---|---|
| Building | Up to $250,000 | Often higher; varies by carrier |
| Contents | Up to $100,000 | Often higher; varies by carrier |
| Living expenses | Not included | Available on some policies |
| Basement coverage | Limited | Broader on some policies |
| Waiting period | Usually 30 days | Often shorter; varies |
If your home would cost more than $250,000 to rebuild, the NFIP alone may leave a gap. Some homeowners pair an NFIP policy with excess flood coverage to fill it.

Written By
David Varrati
Owner, MVP Insurance
On this page
Multiple carriers
We quote your home, auto and other policies across the carriers we represent, look at how they pair for discounts, and show you the differences in coverage, not just the price.
Understanding the NFIP 30 Day Waiting Period
Most NFIP policies take 30 days to become effective after purchase. If you buy on June 1, you generally are not covered for a flood until July 1.
That rule exists to stop people from buying coverage only when the water is already coming. It also catches a lot of Pennsylvania homeowners off guard. By the time the National Weather Service is talking about a remnant tropical system tracking up the Ohio Valley, or forecasters are warning about several inches of rain over the Laurel Highlands, it is already too late to buy a policy that will respond to that storm.
There are a few exceptions. Coverage purchased in connection with a new mortgage, or a policy change tied to a flood map revision, may start sooner. Those situations are specific, and you should confirm with your agent whether one applies to you before counting on it.
Private flood policies frequently carry shorter waiting periods, which is one reason some clients go that route. Even so, do not treat private coverage as a last-minute fix. Underwriters can decline or delay new business when a named storm is approaching.
Our practical advice is simple: buy flood coverage during a dry stretch, when nothing is on the radar. Spring snowmelt and summer thunderstorm season are both predictable, so set up the policy in the months before them, not during them.
River and Creek Flooding From the Ohio River to Connoquenessing Creek
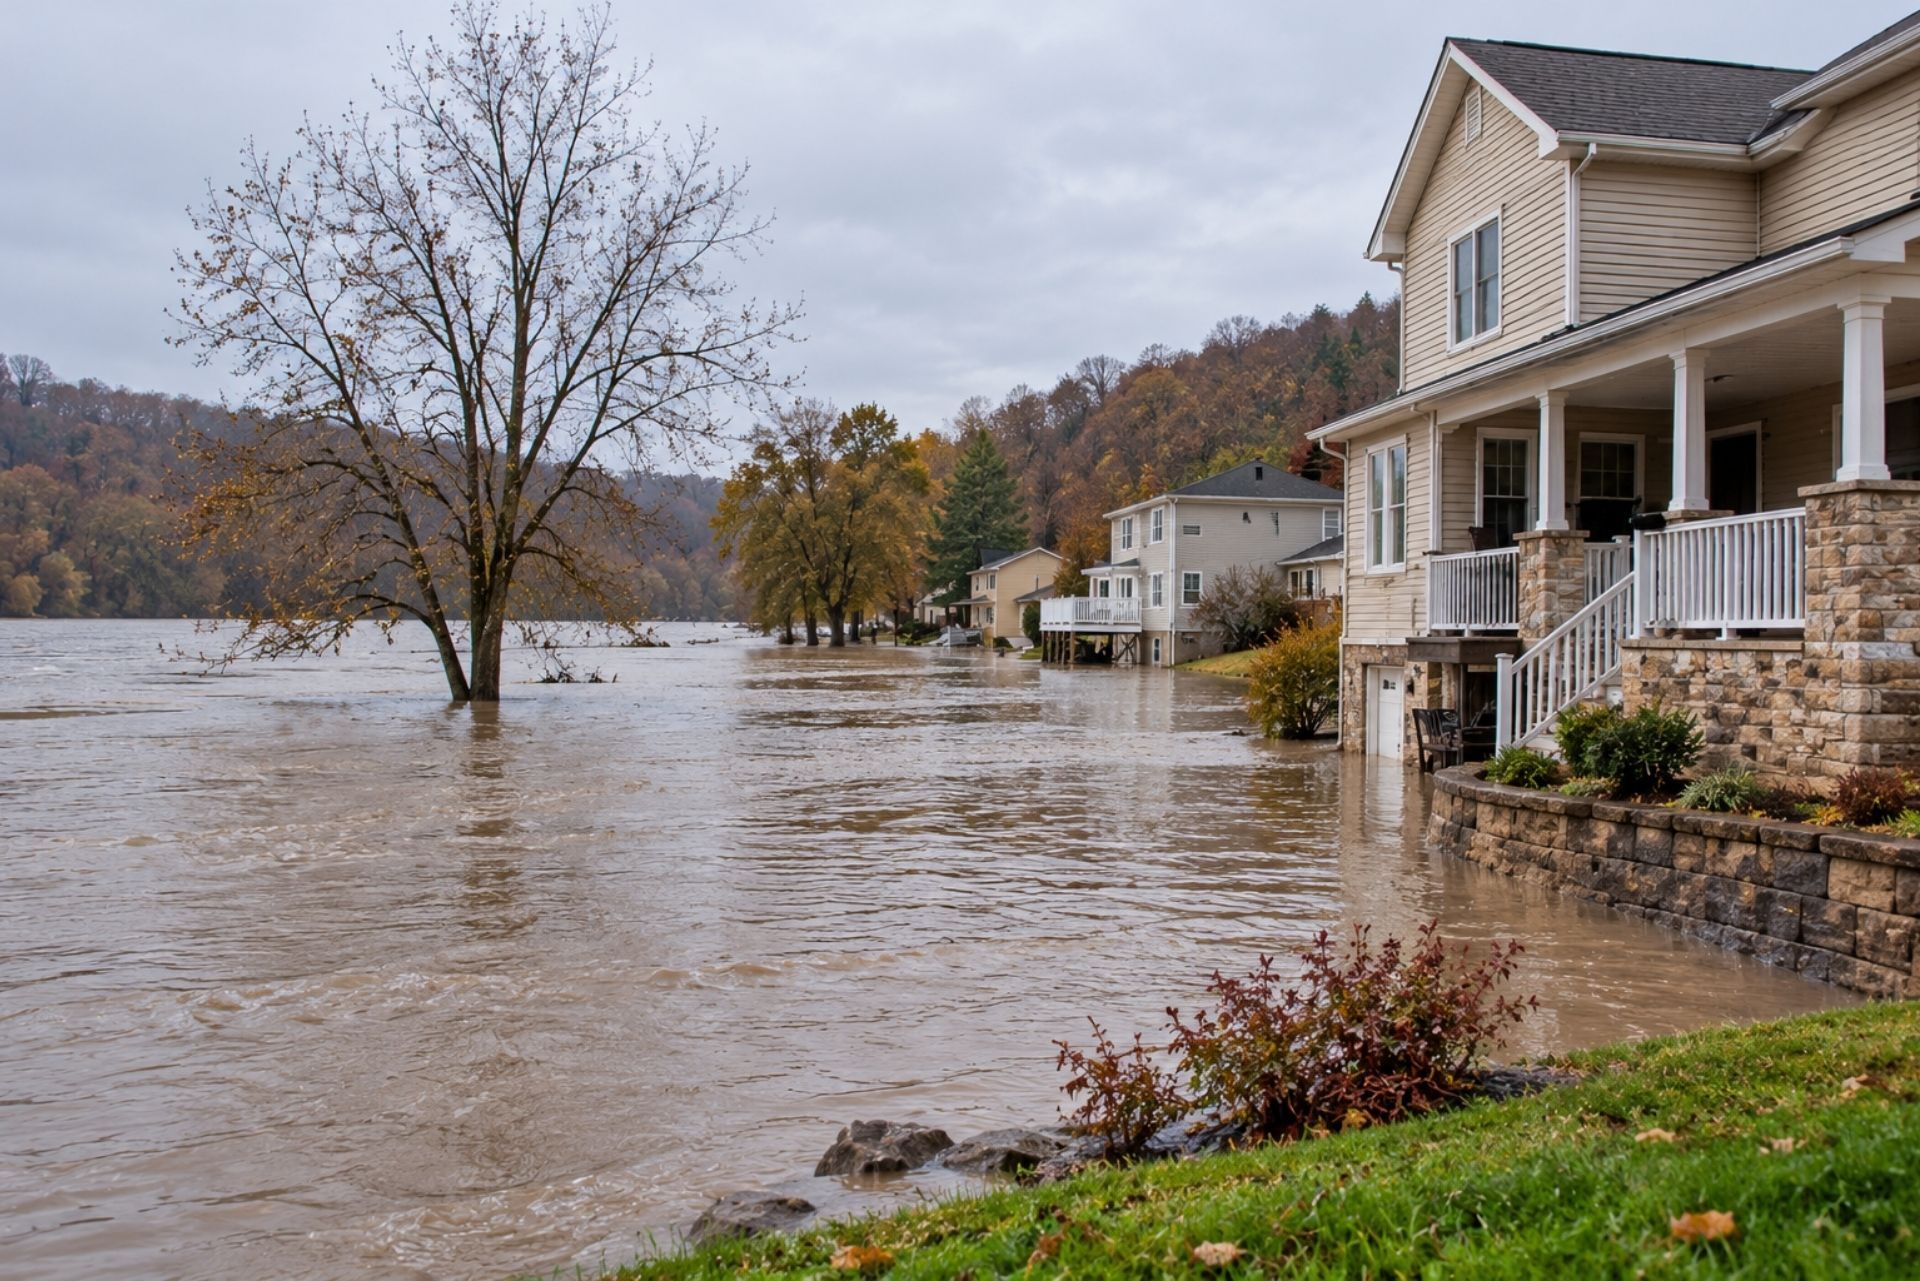
Western Pennsylvania flood risk comes from both big rivers and small creeks, and the smaller waterways often catch people off guard. Pittsburgh sits where the Allegheny and Monongahela meet to form the Ohio, so heavy rain or snowmelt anywhere upstream can push water toward the city's riverfront neighborhoods.
The river gauges move constantly. On October 19, 2026, the Ohio River at Pittsburgh read 16.86 feet, below the 22-foot flood stage. A few days of steady rain across the Allegheny and Monongahela watersheds can close a gap like that faster than most people expect, and low-lying areas along all three rivers have a long history of high-water events.
Closer to our Zelienople office, Connoquenessing Creek is the local concern. The creek floods in Zelienople and Harmony, sending water into streets, yards, and basements near the banks. It is also part of a larger system: the Connoquenessing is a major tributary of the Beaver River, which flows into the Ohio at Rochester, so its runoff contributes to downstream river levels.
Homes along smaller creeks frequently skip flood insurance because their lender never required it. That is how a family in a moderate-risk zone ends up paying for a ruined furnace, drywall, and flooring out of pocket.
Flash Flooding and Heavy Rain on Pennsylvania Hillsides
You do not need to live on a riverbank to flood. Pennsylvania's steep terrain sends rainwater downhill fast, and when two or three inches fall in an hour, the ground and storm drains cannot keep up.
That runoff collects in low spots, driveways, and the bottom of hillside streets. Homes built into slopes, with walkout basements facing uphill, often take water through basement doors and window wells. Small streams that are barely a trickle in August can rise several feet in less than an hour after a summer thunderstorm.
Because this damage comes from surface water, your homeowners policy treats it as flood. If you live at the bottom of a hill, near a culvert, or on a street where water pools after storms, a flood policy deserves a serious look even if your property sits outside any mapped zone.
Written By
David Varrati
Owner, MVP Insurance
On this page
01
Tell us about your household
Your home, your vehicles, your drivers and anything else you want protected.
Pennsylvania Flood Insurance FAQ
Does my PA home insurance cover floods? No. Standard Pennsylvania homeowners policies exclude flood damage from rising or surface water. You need a separate NFIP or private flood policy.
How much flood insurance do I need? Aim for enough building coverage to rebuild your home and enough contents coverage to replace what you own. If rebuilding costs exceed NFIP limits, a private policy or excess flood coverage can close the gap.
Can I get flood insurance if I am not in a high risk zone? Yes. Anyone in a participating community can buy NFIP coverage, and private carriers write homes in every zone. Premiums are often lower outside high-risk areas.
How long does it take for a flood policy to start? Most NFIP policies start 30 days after purchase. Private policies may begin sooner, depending on the carrier.
Does flood insurance cover my basement? Only partly under the NFIP, which limits coverage for finished basements and their contents. Some private policies offer broader basement coverage.
Is flood insurance required in Pennsylvania? Lenders usually require it for federally backed mortgages on homes in high-risk flood zones. Otherwise, it is optional but often worth carrying.
Consult With MVP Insurance in Zelienople and New Springfield
Flood is the gap in most Pennsylvania homeowners policies, and it is one of the easiest to overlook. Your homeowners coverage handles a burst pipe, not a rising creek. The NFIP offers standardized protection with a 30-day wait, while private carriers like Franklin Flood and Foremost can offer higher limits and different terms. And the risk is real well beyond Pittsburgh's rivers, from Connoquenessing Creek in Zelienople and Harmony to any hillside home in a heavy downpour.
Josh Medure and David Varrati can review your specific flood risk and compare NFIP and private options for your address. Call our Zelienople office at (724) 453-1122 or our New Springfield office at (330) 707-9055. If you would rather begin online, you can start your quote here,and we will do the shopping for you.
MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. The right time to buy flood coverage is on a clear, dry day, long before the next storm shows up on the forecast.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













