


Butler PA Business Insurance

Owner, MVP Insurance

Butler PA business insurance means building a policy set around how your company actually operates here: product liability for manufacturers and medical suppliers, property coverage that fits older downtown buildings, accurate workers comp class codes, and commercial auto for your vehicles. An independent agent can compare carriers so each piece fits without gaps.


That sounds simple until you look at a real Butler business. A machine shop off Route 8 might share almost nothing with a boutique on Main Street, yet both owners sign renewal paperwork every year without knowing what changed. Below is a practical look at the coverage decisions that matter most for local employers in 2026, including where policies tend to fall short.

Protecting Butler PA Businesses from Local Risks

Butler businesses face a specific mix of risks: aging commercial buildings, ground affected by historic coal mining, a workforce spread across industrial and service jobs, and vehicles covering long rural distances. The right insurance program addresses each of these instead of relying on a generic package policy.


Butler is the county seat, so the city draws courthouse traffic, professional offices and retail that depends on weekday foot traffic. Head north and you reach Slippery Rock University, which supports landlords, restaurants and service companies whose revenue rises and falls with the academic calendar. Those businesses often need business income coverage that reflects seasonal swings, not a flat monthly average.


Much of the county also sits over historic coal mining areas. That history shows up in property risk, since standard commercial property forms generally exclude earth movement, including subsidence. Owners who assume their building policy covers a cracked foundation from collapsing mine voids are often surprised at claim time.


A sound local risk plan usually includes:


  • General liability for customer injuries and property damage
  • Commercial property with appropriate valuation and endorsements
  • Workers compensation, required for most Pennsylvania employers
  • Commercial auto for any vehicles titled to the business
  • Umbrella liability to sit above the core policies
David Varrati

By: Joshua Medure

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Life

Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.

Feature DP-1 (Basic) DP-3 (Special)
Covered perils Named perils only All risks, minus exclusions
Building settlement Usually actual cash value Usually replacement cost
Sudden water damage Often excluded Usually covered
Theft/vandalism Optional, limited Typically included
Loss of rent Often optional Usually included
Liability Often an add-on Add-on or included
Best fit Older, low-value homes Most modern rentals
PA legal requirement None by state law None by state law

Insurance for Manufacturers and Healthcare Suppliers

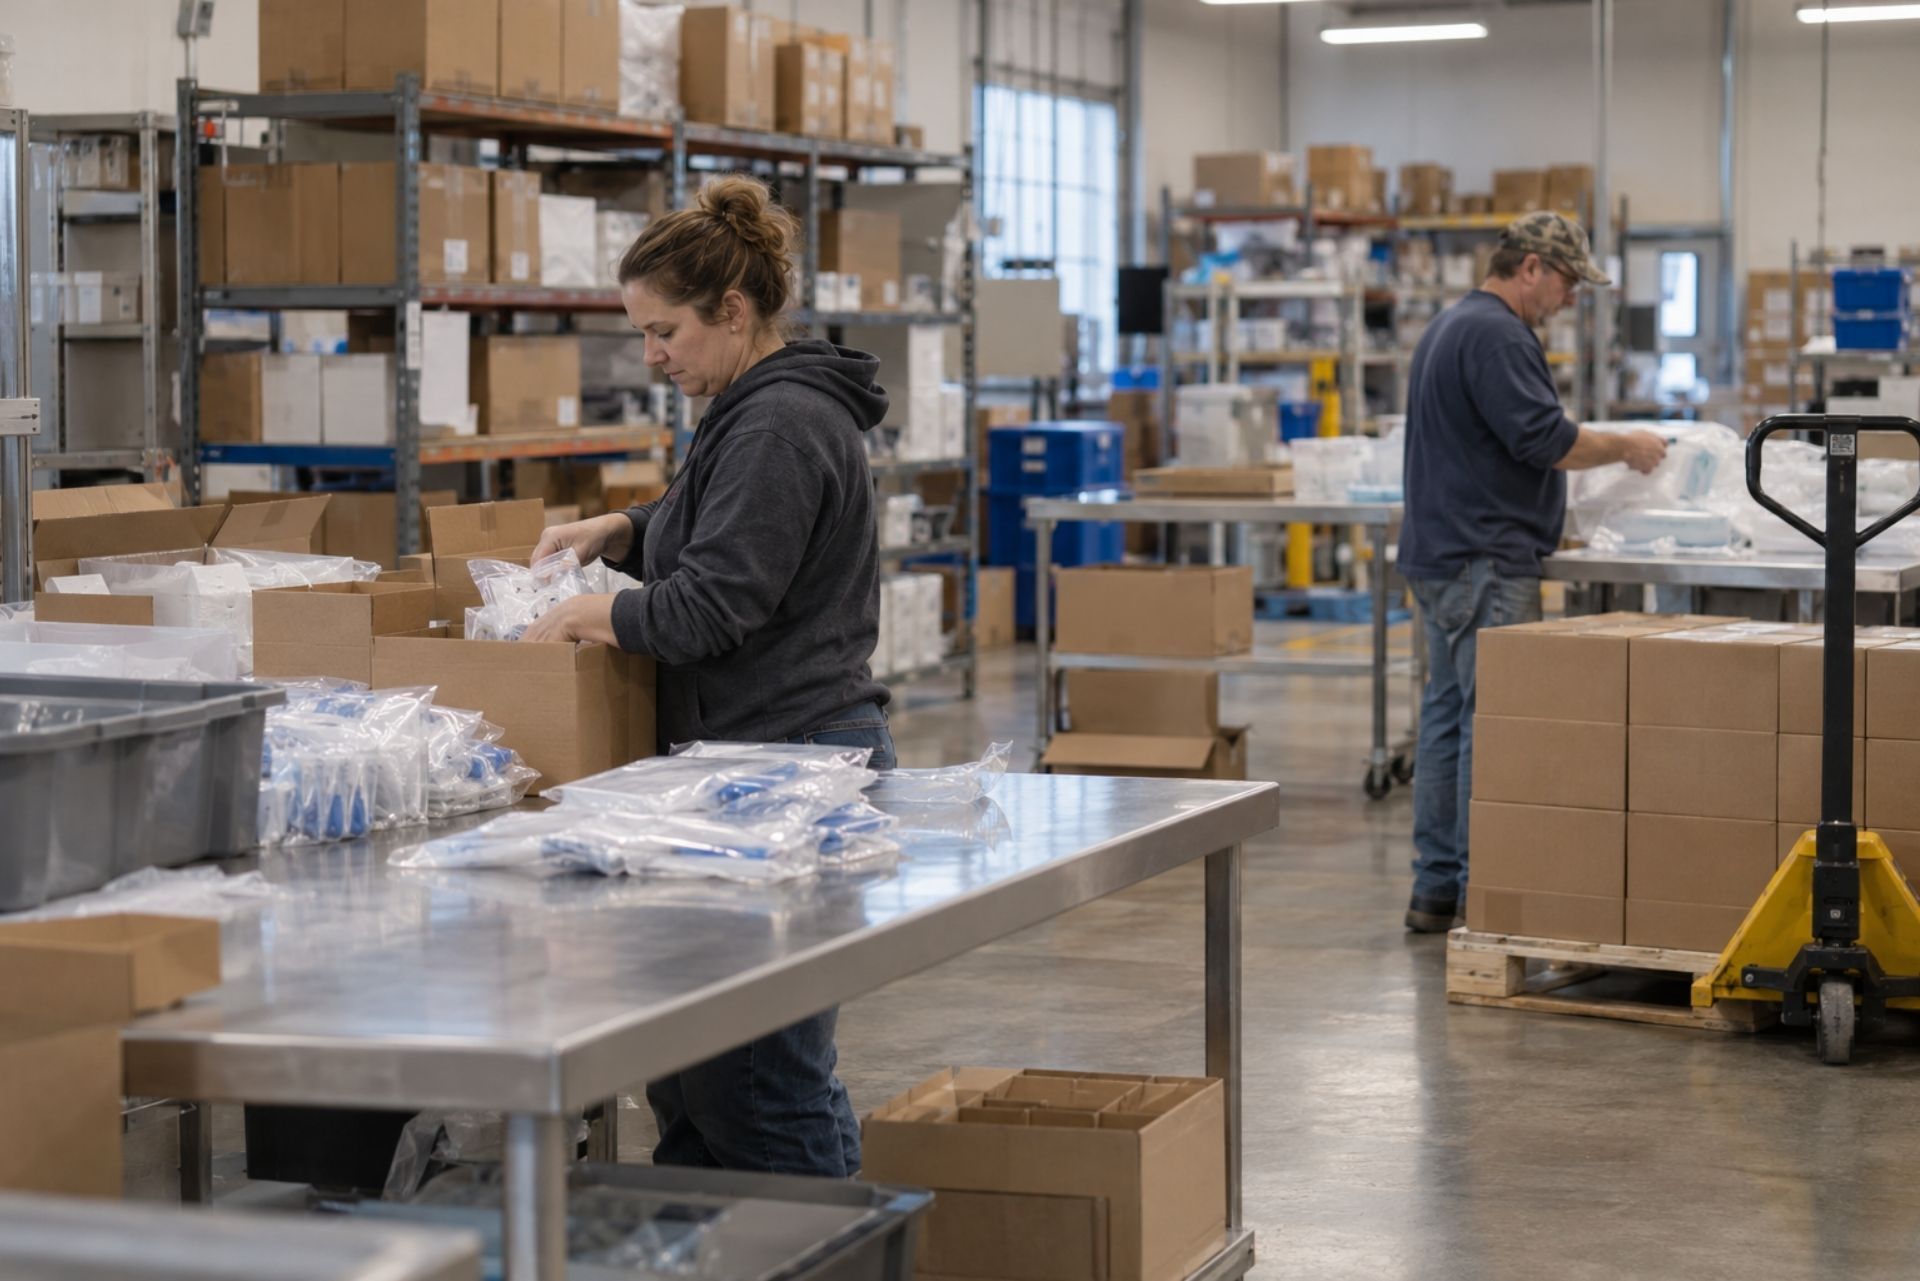
Manufacturers and healthcare suppliers in Butler County need product liability, supply chain protection and property coverage for equipment and inventory. The biggest exposures come from what leaves your loading dock, not just what happens inside the building.


Product liability is where these operations differ most from a typical small business. A fabricator supplying brackets to an equipment maker can be pulled into a lawsuit years after shipment if a part fails. Medical supply distributors carry similar exposure when a mislabeled or contaminated product reaches a patient, even if they never manufactured it. Look closely at whether your policy is written on an occurrence or claims-made basis, and whether completed operations coverage is included.


Supply chain interruptions are the other quiet threat. Standard business income coverage typically responds only when your own property is damaged. If a key supplier's plant floods and you can't fill orders, you need contingent business income coverage, which must be added deliberately.

Coverage gaps we see often

  • Equipment breakdown: a failed compressor or CNC controller isn't usually covered under basic property forms
  • Spoilage: temperature-sensitive medical goods need a specific endorsement
  • Product recall expense: liability policies often exclude the cost of pulling products off shelves
  • Vendor contracts: customers increasingly demand additional insured status and higher limits before signing

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

HCertificates of Insurance for Pennsylvania Contracts

Canopy import

Share your current policies in a few clicks through Canopy. We see exactly what you have today, so the comparison is apples to apples.

Downtown Shops and Commercial Property in Older Buildings

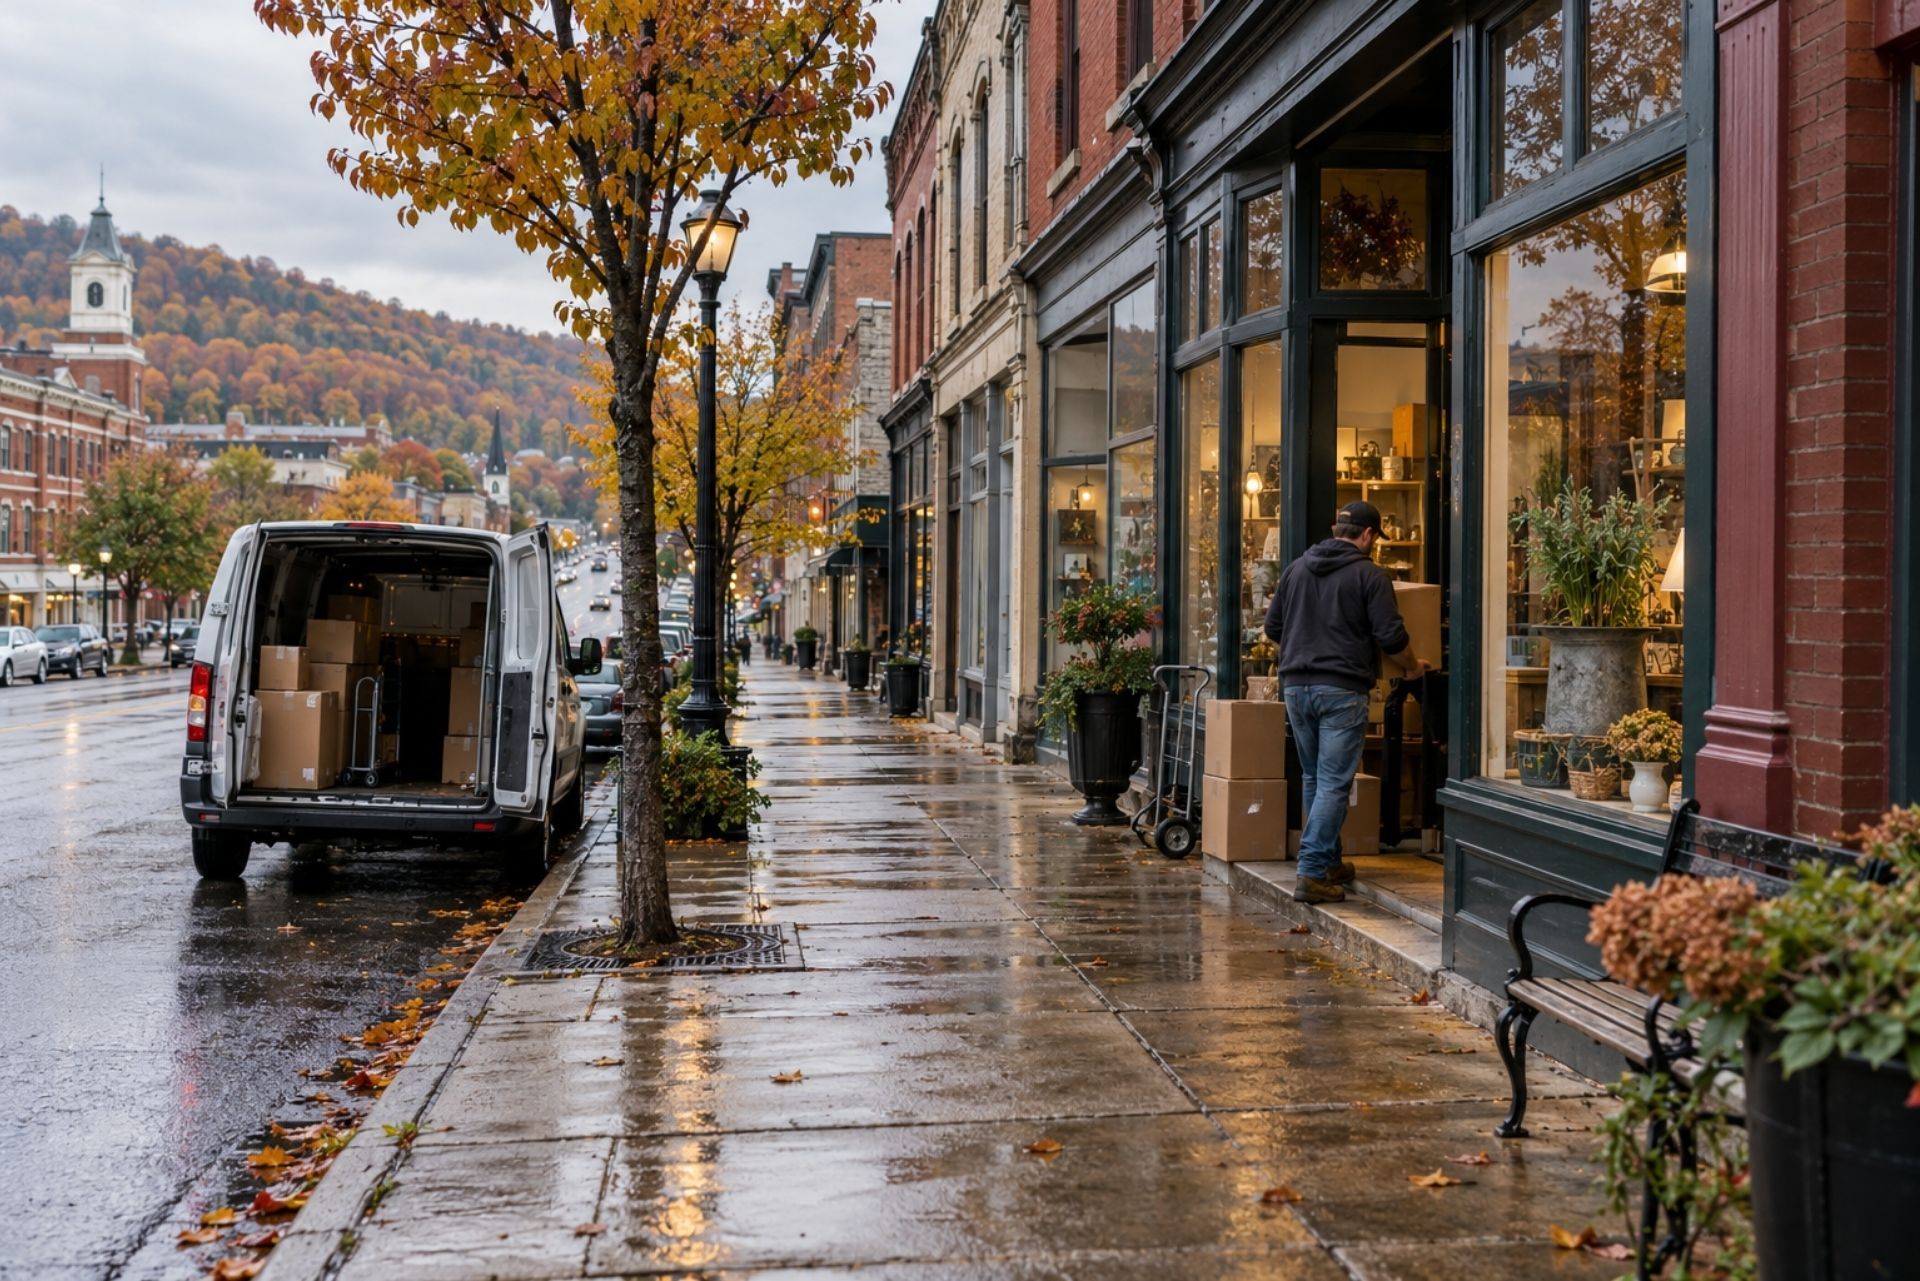
Historic Main Street storefronts in Butler are insurable, but they need careful valuation, building code upgrade coverage and, in many cases, mine subsidence protection. Underwriters will ask about wiring, roofs, plumbing and heating before quoting.


Older buildings create a valuation problem. Replacing a 1910s brick facade with matching materials costs far more than a basic market value estimate suggests. If you insure at actual cash value, depreciation can leave a big shortfall. Replacement cost is usually the safer choice, paired with ordinance or law coverage. That matters because the City of Butler requires a 2026 Commercial Permit Application for structural changes, which brings current energy efficiency and accessibility standards into play. After a fire, you may be rebuilding to modern code, not to the original design.


Mine subsidence deserves its own conversation. Because of the county's coal mining history, a commercial property policy alone won't protect against ground collapse from old mine workings. Pennsylvania offers subsidence insurance through a state program, and adding it is relatively simple if you ask before a problem appears.


Financing adds another layer. The Butler Area Development Corporation's Downtown Business Loan of up to $100,000 at 2.5% interest requires proof of property and flood insurance, so line up your policies early.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Understanding Workers Comp Class Codes for Pennsylvania Employees

Your workers comp premium in Pennsylvania is built from class codes, payroll and your experience modification. Each employee is assigned a classification reflecting their job's risk, and every code carries its own rate per $100 of payroll.


Market data puts the average Pennsylvania rate around $1.27 per $100 of payroll as of October 2026 (verify at publish), ranking the state 14th nationally. That average hides huge variation. A clerical code may cost a small fraction of what a foundry or roofing code costs. Pennsylvania uses its own classification system through the PCRB rather than the national NCCI codes, so don't assume a code from another state applies here.


Rates shift too. The PCRB implemented Filing No. C-387 on April 1, 2026, updating loss costs and rating values. It has also updated minimum and maximum payroll amounts for executive officers, which affects owner-heavy small companies.


Misclassification is the expensive mistake. When an auditor finds that your "office manager" spends half her day on the shop floor, the carrier can reclassify that payroll and send a bill for the difference. To protect yourself:


  1. Write down actual job duties for each role
  2. Track payroll separately for workers who split duties
  3. Keep subcontractor certificates of insurance on file
  4. Review codes with your agent before each audit

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Fleet Coverage and Commercial Auto Policy Comparison

Any vehicle owned by your business, or regularly driven for it, should be on a commercial auto policy. Personal auto policies commonly exclude business use, and that exclusion surfaces right after an accident.


Costs have been climbing. Commercial auto rates in Pennsylvania rose by more than 20% in 2025, with double-digit increases continuing through late 2026 (verify at publish), driven by repair costs and larger jury awards. Market figures put the average annual Pennsylvania fleet premium near $7,536 per unit. On the personal side, lawmakers have considered raising minimum property damage liability from $5,000 to $25,000,a reminder that state minimums are a floor, not a target. Employees who drive their own cars on errands should also review their Butler auto insurance.

Coverage What it does Typical business limit
Liability Injuries and damage you cause $1M combined single limit
Hired & non-owned Rentals and employee cars on business Matches liability
Collision/comprehensive Damage to your vehicles Actual cash value
Uninsured motorist Injuries from uninsured drivers Matches liability
Medical payments Occupant medical bills $5,000 to $10,000

Fleet discounts on rates aren't the goal here: driver screening, telematics and a written vehicle policy often do more for pricing over time. See how auto fits your full Pennsylvania business insuranceprogram.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Industry Common Per Occurrence Common Aggregate Typical Driver
Retail shop $1,000,000 $2,000,000 Commercial lease
Restaurant/café $1,000,000 $2,000,000 Lease, liquor license, events
Residential contractor $1,000,000 $2,000,000 Client and GC contracts (HICPA floor is lower)
Commercial contractor $1,000,000 $2,000,000 + umbrella GC and municipal contracts
Manufacturer $1,000,000 $2,000,000 products aggregate Distributor agreements
Office/consultant $1,000,000 $2,000,000 Client contracts, lease
Event vendor $1,000,000 $2,000,000 Venue or borough permit

Frequently Asked Questions About Butler Business Insurance

Do I need workers comp if I only have one employee in Pennsylvania? Generally yes. Pennsylvania requires most employers to carry workers comp starting with their first employee, with limited exceptions.


Does my commercial property policy cover mine subsidence? Usually not. Standard policies exclude earth movement, so Butler County owners typically add separate subsidence coverage.


What's the difference between general liability and product liability? General liability covers injuries and damage from your operations. Product liability covers harm caused by products you make or sell, and manufacturers often need higher limits for it.


Can I use my personal car insurance for business deliveries? Not safely. Most personal policies exclude business use, so a commercial auto or hired and non-owned auto policy is the right fit.


Why did my workers comp bill go up after the audit? Usually payroll was higher than estimated or an employee was reclassified to a higher-risk code. Accurate job records help prevent surprises.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Consulting with MVP Insurance Agency Specialists

Getting Butler business coverage right comes down to matching each policy to a real exposure: product claims, older buildings over mined ground, payroll codes and vehicles on the road. Small details, like a missing contingent income endorsement or a misclassified employee, create the most painful claims.


MVP Insurance was founded in 2008 by Josh Medure and David Varrati as an independent agency, which means we compare multiple carriers on your behalf instead of selling one company's products. Our team can review your current policies, flag gaps and handle renewals so you aren't chasing paperwork. We're licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


Visit or call either office:


  • Zelienople, PA:108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122
  • New Springfield, OH:13823 Grant St, New Springfield, OH 44443, (330) 707-9055


If your renewal is coming up or you've never had a full review, now is a good moment to start your quote.A short conversation today can keep a bad claim from becoming a business-ending one.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

Joshua Medure

Owner, MVP Insurance


I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania






