


Cranberry Township PA Car Insurance

Owner, MVP Insurance

Cranberry Township drivers need more than Pennsylvania's minimum coverage. Daily traffic through the Route 19, I-79 and Turnpike interchange, long highway commutes into Pittsburgh, and the cost of adding a teen all call for higher liability limits, stacked underinsured motorist protection, and a policy built around how your household actually drives.


That's the short answer. The longer one depends on where you drive, how many cars sit in your driveway, and whether a 16-year-old just got a learner's permit. The township sits at the center of some of the heaviest traffic in western Pennsylvania, and a policy written for a quiet rural county doesn't always hold up here.


The good news is that the statewide market has calmed. The Pennsylvania Insurance Department reported in April 2026 that the state's auto insurance market is stabilizing, with an average 0.5% decrease across approved filings. That makes this a reasonable time to review your coverage without bracing for a big jump. Below we walk through the local risks and the coverage choices that matter most.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Route 19, I-79 and Turnpike Interchange Traffic Risks

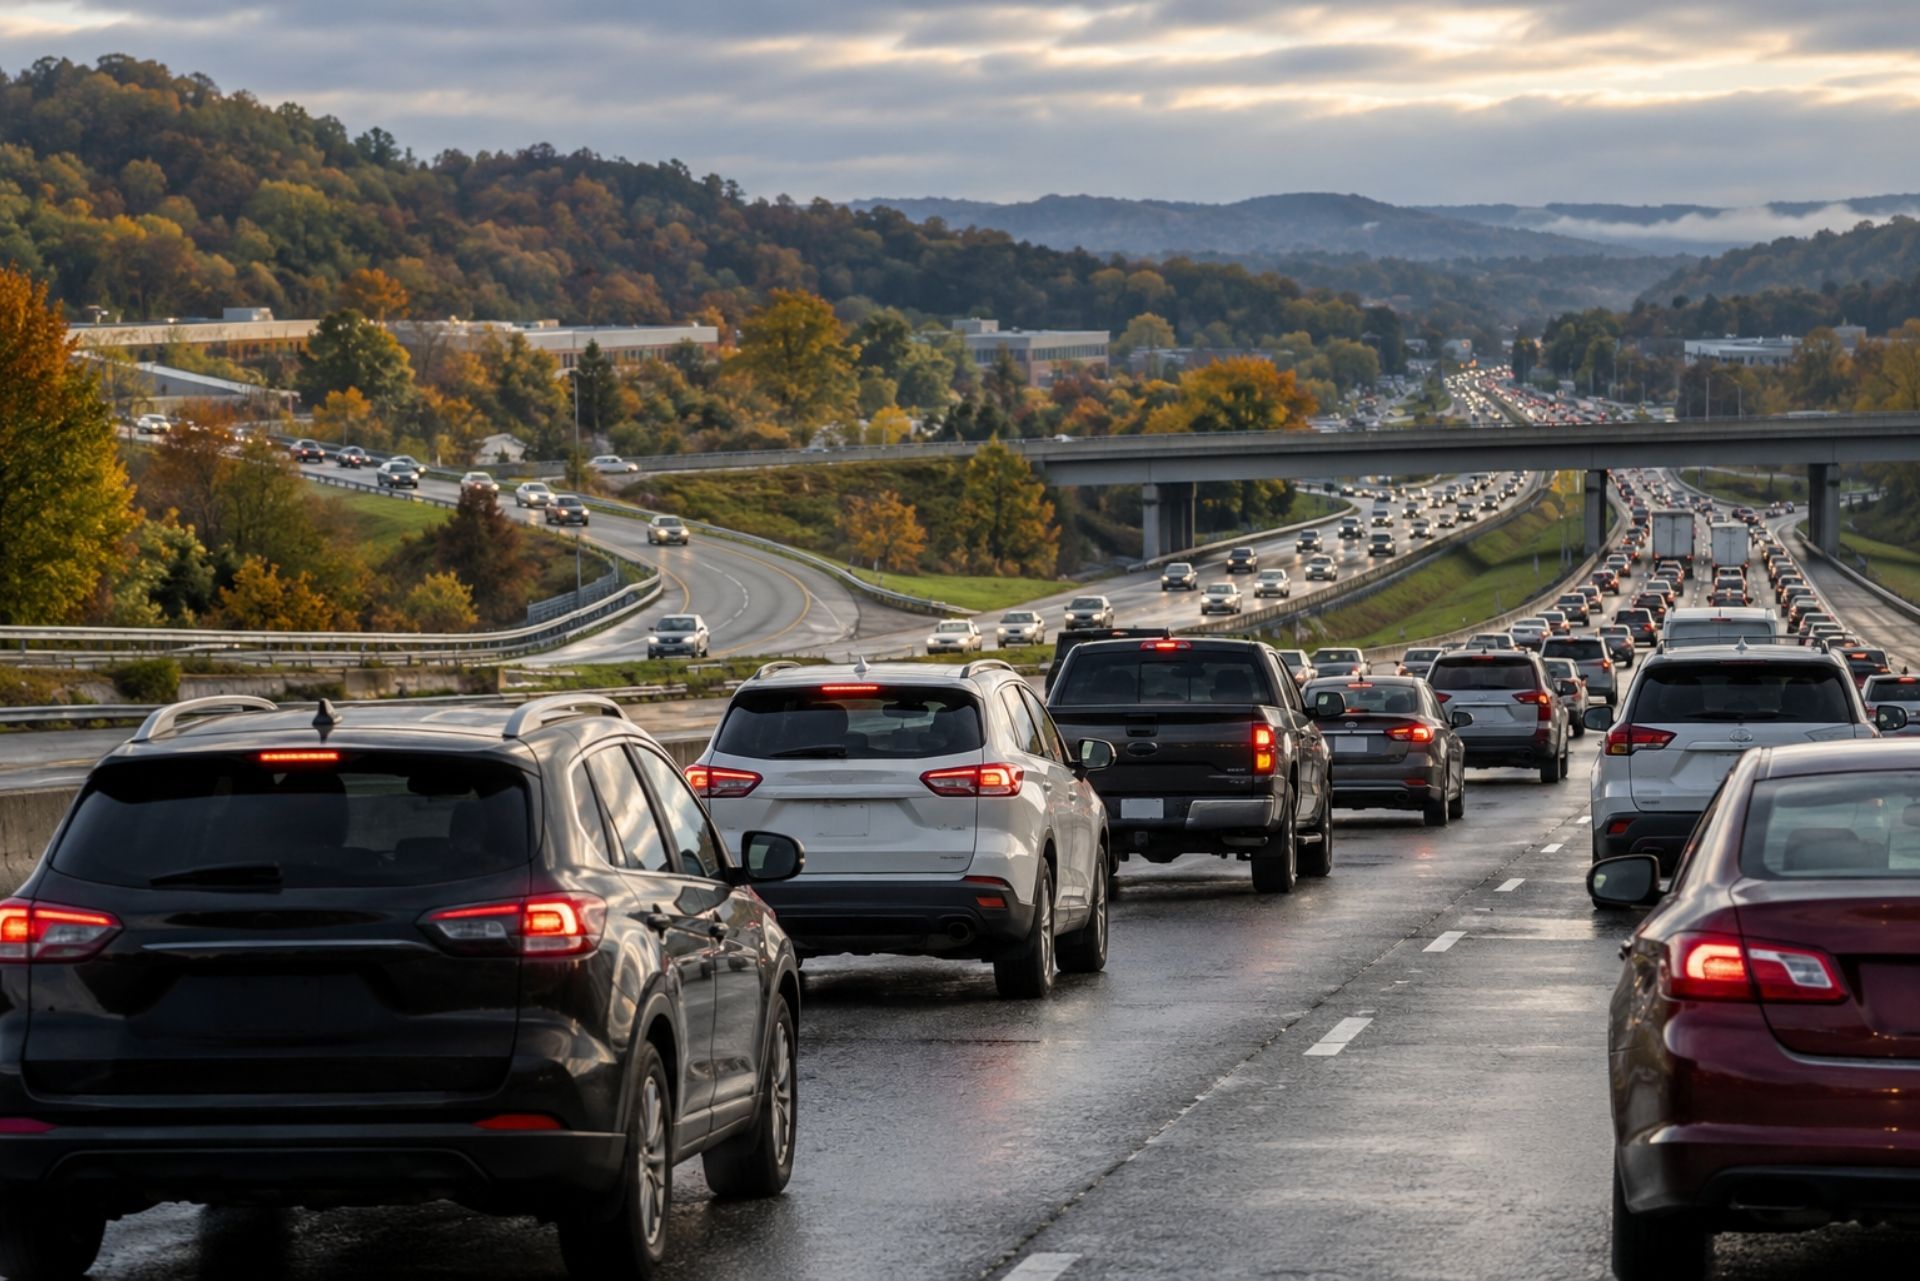
Higher traffic density means higher claim frequency, so liability limits matter more here than in most places. Cranberry is where I-79, the I-76 Turnpike, and Route 19 converge, and the intersection of Route 19 and Freedom Road (Route 228) sees weekday volumes reaching 100,000 vehicles. That is a lot of merging, braking, and lane changing in a small space.


The Route 228 business corridor adds commercial traffic: box trucks, delivery vans, and contractors heading to job sites. A rear-end collision involving a work vehicle or a multi-car chain reaction can produce injury claims that blow past a $15,000 limit in a hurry.


Construction is part of daily life here too. PennDOT District 10 is running Route 228 corridor improvement projects between Route 8 and Route 19, and a planned expansion would add a third lane in each direction on I-79 from the Allegheny/Butler line to the SR 528 interchange. Work zones mean shifting lanes and sudden stops. We generally suggest liability limits of at least 100/300/100 for drivers who use these roads daily, and higher if you own a home or have savings to protect.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Managing Risks During Long Commutes into Pittsburgh

Long commutes call for strong collision and comprehensive coverage, plus roadside assistance and rental reimbursement. A typical 20-mile trip south takes roughly 38 to 55 minutes during the 7:00 to 8:30 AM peak. The ride home between 4:30 and 6:00 PM usually runs 35 to 50 minutes. That's well over an hour a day at highway speed, five days a week.


More miles mean more exposure. Here's what we see go wrong most often for commuters:


  • Kicked-up debris cracking a windshield on I-79 (a comprehensive claim)
  • Deer strikes on early winter mornings, also comprehensive
  • Slow-speed rear-end crashes in stop-and-go traffic near the Parkway
  • Breakdowns on a shoulder with no safe spot to wait


A common mistake is dropping collision on a car that's still your only way to work. If it's out of commission for two weeks, rental reimbursement keeps you employed. Roadside assistance usually costs little and pays for a tow off a busy interstate.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella Coverage

An umbrella policy typically kicks in once your underlying auto or home liability is exhausted. Picture a multi-car accident where injuries run well past your auto limit, or a guest seriously hurt on your deck. Umbrellas often cover claims your base policies don't, like certain libel or slander suits. The catch: carriers usually require minimum underlying limits, so your auto and home policies must be set correctly first.

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Life Insurance

Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.

Why You Need Stacked Underinsured Motorist Coverage

Stacked underinsured motorist (UIM) coverage multiplies your protection by the number of vehicles on your policy, which matters when the at-fault driver carries only state minimums. With two cars and $100,000 stacked UIM, you could have up to $200,000 available for your medical bills and lost wages after a serious crash.


Pennsylvania lets you waive stacking by signing a form, and plenty of people sign it at the counter without understanding it. That signature can save a modest amount of premium and cost you dearly later. If the other driver has $15,000 in liability and your injuries run $150,000, stacked UIM is often what closes the gap.


Case law here has shifted. A January 2025 Superior Court decision allows plaintiffs to recover both liability and UIM coverage from the same policy in certain circumstances, departing from decades of prior rulings. A 2026 decision also found that substituting a vehicle does not require a new stacking waiver. Translation: if you waived stacking years ago, that choice may still follow you after you trade cars. Review it.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Adding Teen Drivers to Your Cranberry Township Policy

Adding a teen is the right moment to raise your liability limits, not lower them. Your household risk changes overnight, and so does your exposure if your new driver causes a serious crash. In Pennsylvania, adding a teen to a standard family policy typically runs about $2,533 a year on average, though your number depends on the vehicle, your carrier, and your driving history.


A few steps reliably help families manage that cost:


  1. Ask about good student credits if your teen keeps a B average or better.
  2. Look into driver training credits for completing an approved course.
  3. Assign the teen to the safest, least expensive vehicle where the carrier allows it.
  4. Consider an umbrella policy if you own a home or have significant savings.


What we avoid is cutting comprehensive or UIM to offset the teen premium. New drivers on Route 19 and I-79 are exactly when you want the full policy in place. We shop multiple carriers so families can compare credits side by side.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Comparing Pennsylvania Car Insurance Coverage Options

Pennsylvania's minimums are low for an area with this much traffic. Here's how they compare with what we commonly recommend for Cranberry commuters.

Coverage PA Minimum Suggested for Cranberry Commuters
Bodily injury liability $15,000 / $30,000 $100,000 / $300,000 or higher
Property damage liability $5,000 $100,000
Medical benefits (first party) $5,000 $10,000 to $25,000
Underinsured motorist Optional Match liability, stacked
Uninsured motorist Optional Match liability, stacked
Collision / comprehensive Not required Yes, with a deductible you can afford
Rental and roadside Not required Yes, for daily commuters

A $5,000 property damage limit won't replace most newer vehicles, let alone a commercial truck. The gap between minimum and suggested coverage is often smaller in price than people expect.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Coverage What It Protects Common Gap to Watch
Homeowners Dwelling, belongings, liability High wind/hail deductibles
Renters Belongings, liability, living costs Low liability limits
Auto Vehicle damage, injury liability State minimum limits only
Motorcycle Bike, gear, liability Custom parts excluded
Boat Hull, motor, liability on water Trailer or navigation limits
Umbrella Excess liability above other policies Underlying limits too low
Life Income replacement for family Only employer coverage

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Frequently Asked Questions About Cranberry Township Auto Insurance

Is car insurance more expensive in Cranberry Township? Rates depend on your vehicle, driving record, and coverage choices. Busy roads can push claim frequency up, but comparing several carriers usually turns up a fair option.


What is stacked coverage in Pennsylvania? It lets you combine uninsured or underinsured motorist limits across each car on your policy. Two cars with $50,000 each can mean $100,000 of protection.


Should I choose full tort or limited tort? Full tort keeps your right to sue for pain and suffering after a crash. Limited tort costs less but restricts that right in many cases, so most commuters do better with full tort.


When should I add my teen to my policy? Call your agent when your teen gets a learner's permit. Some carriers handle permit drivers differently, so ask before they start driving.


Do I need rental coverage if I have two cars? If both cars are used every day, yes. A two-week repair can leave one person without a ride to work.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Partnering with MVP Insurance for Local Expertise

The right policy for a Cranberry driver accounts for interchange traffic, long highway commutes, stacked UIM, and the day your teen gets a license. Getting those pieces right takes someone who knows the roads and compares more than one carrier's offer.


MVP Insurance is an independent agency founded in 2008 by Josh Medure and David Varrati, with offices in Zelienople and New Springfield, Ohio. We work for you, not an insurance company, and we serve Cranberry residents from our nearby office at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122. Our New Springfield office is at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293.


If it's been a while since anyone looked at your limits or your stacking waiver, now is a good time. You can start your quote online, and we'll compare options across carriers so you can drive Route 19 knowing your coverage fits your life.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








