


Owner, MVP Insurance
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
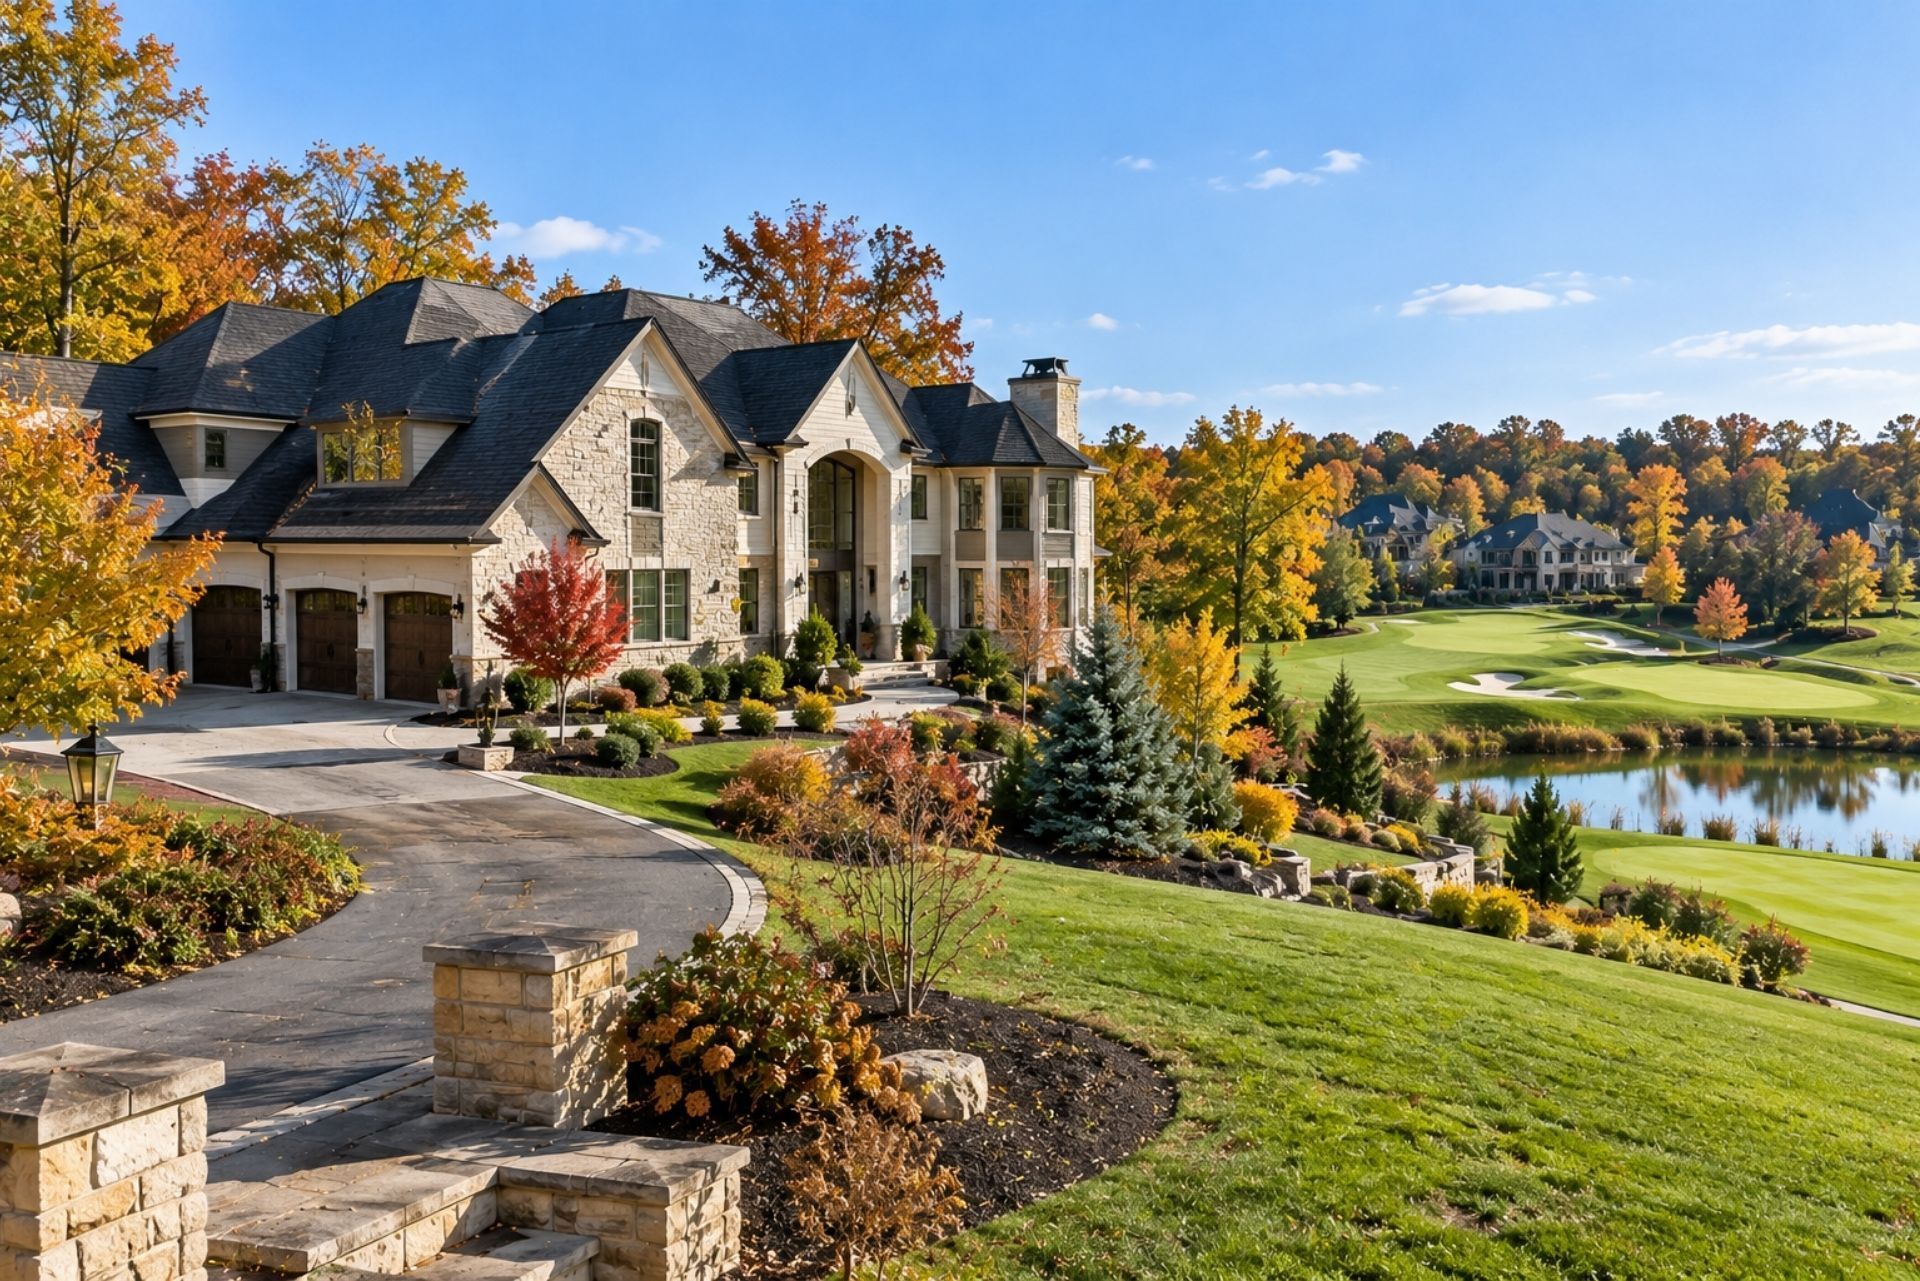
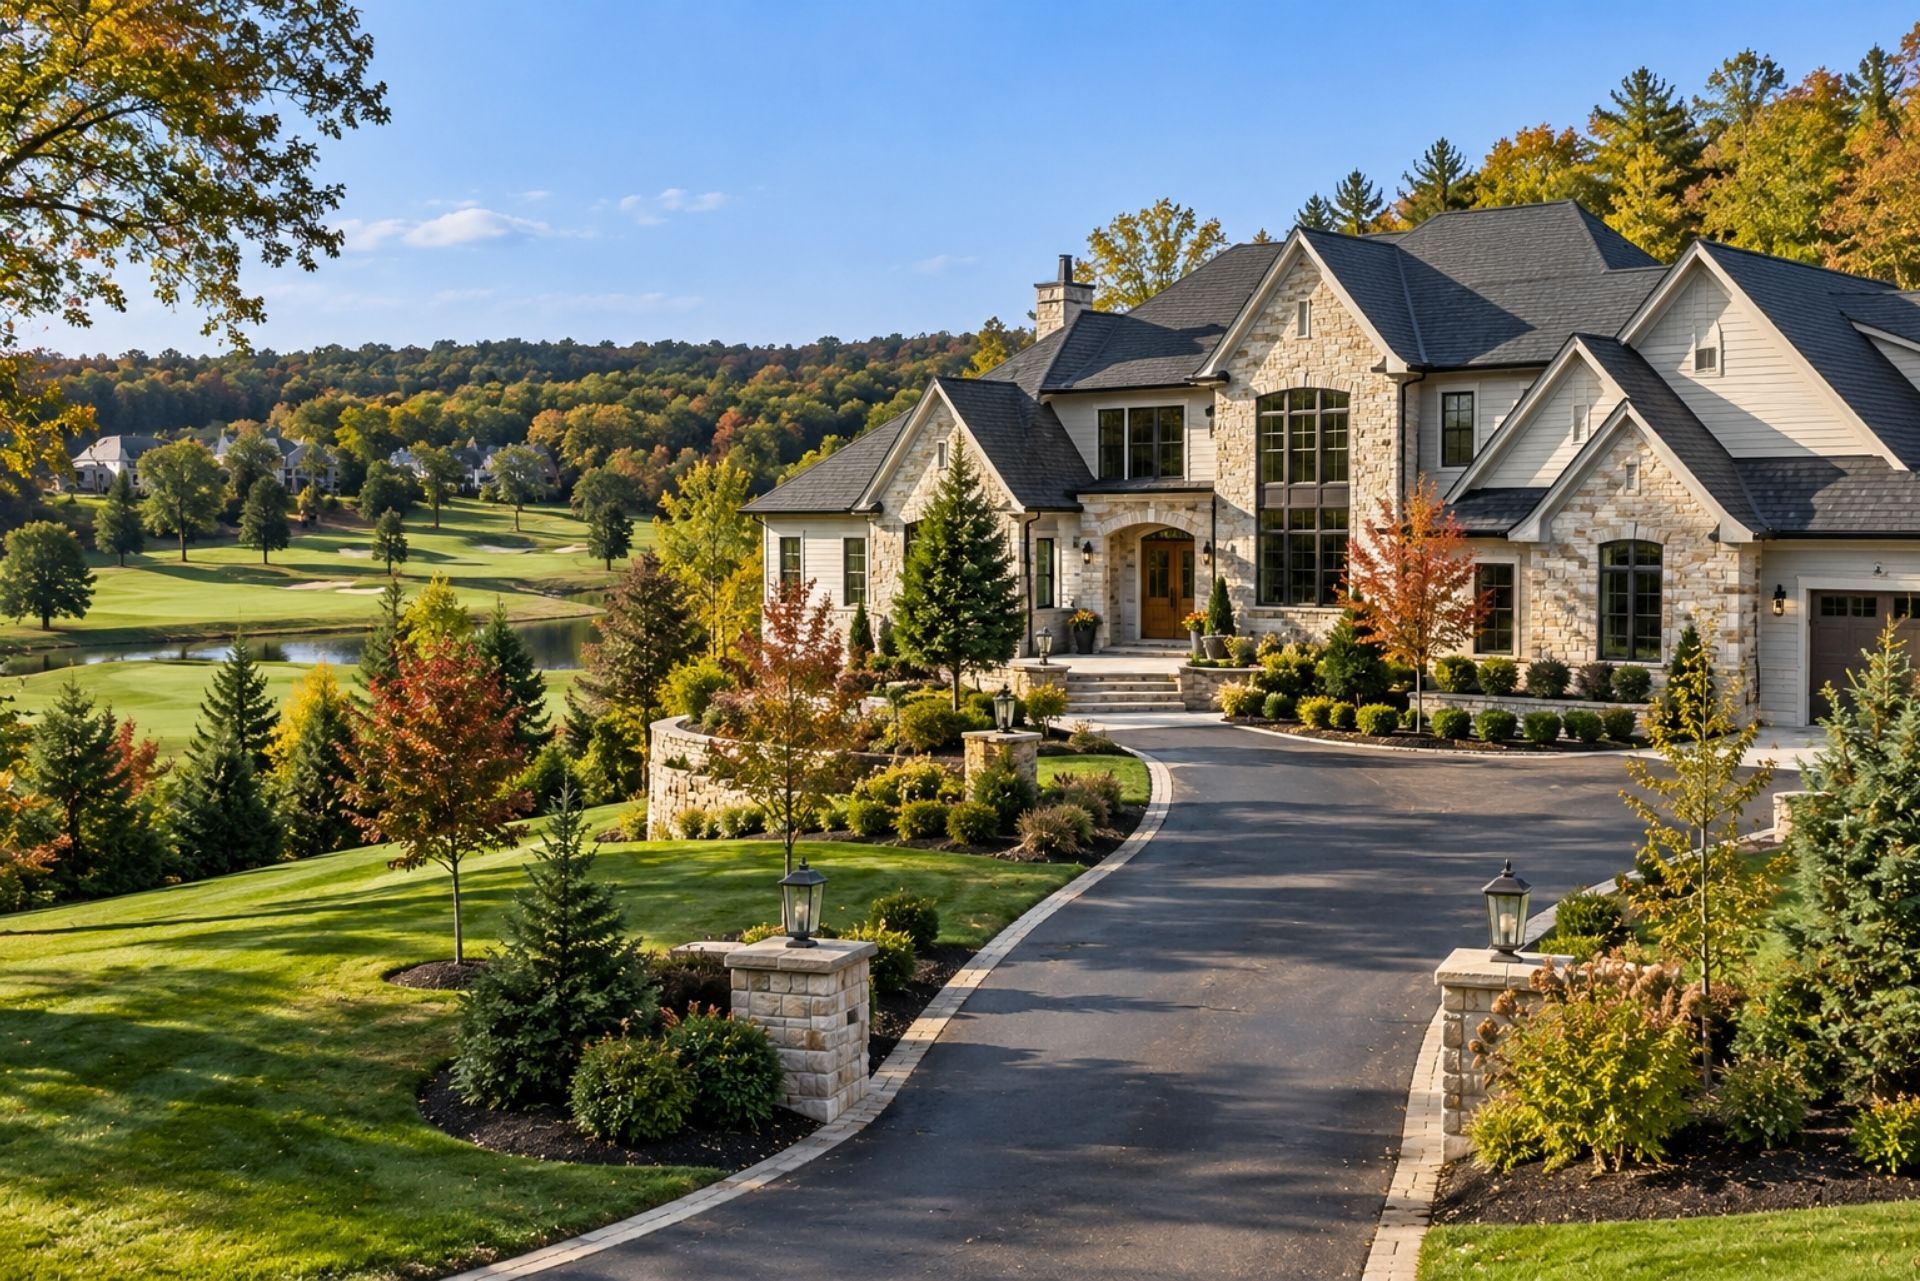
Wexford PA high value home insurance is built for homes that a standard policy undervalues: newer custom builds, finished lower levels, and families with significant assets to protect. If your home sits in Pine, Richland, Franklin Park, or Marshall, the right policy pairs true replacement cost with water backup protection and a high limit umbrella.
That pairing matters more than most homeowners realize. A standard homeowners form is written for a typical house, and a typical house in the North Hills does not have a walk-out basement with a wet bar, a home theater, and custom millwork throughout. The gaps tend to show up at the worst possible time: after a sump pump quits during a March thaw, or after a lawsuit lands from a guest injury.
Pennsylvania's market is also shifting. The state Insurance Department blocked $227.9 million in proposed property and casualty rate increases in 2025, including $16 million in homeowners and dwelling fire premiums. In April 2026, it moved to deregulate certain rate and form filings to encourage competition. More competition generally means more variation between policies, which makes careful comparison more valuable than ever.
Wexford PA High Value Home Insurance for Custom Estates
A Wexford mailing address does not tell an insurer which township you live in. Wexford addresses span Pine, Richland, Franklin Park, and Marshall townships, and each has its own building patterns, fire protection, and development history. That is why a custom estate here needs a policy designed around the actual house, not the zip code.
Specialized high value coverage differs from a standard policy in several practical ways. It typically settles dwelling claims on a replacement cost basis that can extend beyond the stated limit, offers higher limits for jewelry, art, and collections, and often includes cash settlement options if you choose not to rebuild. Many of these policies also come with pre-loss appraisals, so the dwelling limit reflects real construction costs instead of a software estimate.
We see a common mistake here: homeowners carry the dwelling limit their mortgage lender required at closing and never revisit it. A home purchased or built a few years ago may cost meaningfully more to rebuild today. You can read more about how these policies work on our high value home insurance in Pennsylvaniapage.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Nationally, manufactured home insurance typically runs $800 to $1,200 per year in 2026, though your price depends on the home's age, location, claims history, and deductible. A newer home in a low-risk area with a higher deductible can come in well under that range.
Policy filings in the state are also changing. In April 2026, the Pennsylvania Insurance Department issued Notice 2026-07 to modernize filing requirements while keeping strict oversight of personal risk insurance. For consumers, that means carriers still have to justify their manufactured home forms and rates to regulators.
MVP Insurance, founded in 2008 by Josh Medure and David Varrati, is an independent agency that works with carriers including Erie, Progressive, Foremost, and American Modern. Because we compare several companies side by side, we can match a newer home with a carrier that rewards its condition and place an older or unusual home with a carrier that specializes in it.
Insuring Newer Custom Builds in Pine and Franklin Park
Newer custom builds in Pine and Franklin Park need replacement cost coverage that accounts for their unique architectural features, not just square footage. A builder-grade estimate rarely captures the true cost of rebuilding a one-of-a-kind home.
Consider what makes these houses expensive to replace:
- Custom millwork and trim that requires skilled carpenters, not off-the-shelf moldings
- Stone and brick exteriors with specific masonry patterns
- Vaulted and coffered ceilings with complex framing
- High-end kitchens with custom cabinetry, stone counters, and professional appliances
- Smart home systems, integrated audio, and whole-house generators
When a fire damages part of a custom home, matching materials becomes the real issue. A good high value policy will pay to replace with materials of like kind and quality, and some will extend to matching undamaged areas so a repaired wall does not look patched next to the original.
Building code upgrades are another overlooked gap. Codes change, and a rebuild may require upgrades that a standard policy caps at a low percentage. For a home built recently, the gap may be smaller, but it still exists once you factor in future code cycles. Ask how your policy handles ordinance or law coverage and whether the limit fits your home's value.

Written By
David Varrati
Owner, MVP Insurance
On this page
Multiple carriers
We quote your home, auto and other policies across the carriers we represent, look at how they pair for discounts, and show you the differences in coverage, not just the price.
Liability and Property Risks in Golf Course Communities
Living in a Wexford golf course community brings two distinct exposures: property damage from stray golf balls and higher liability risk from increased foot traffic near your home. Both deserve attention when you set limits.
Stray balls crack windows, dent siding and gutters, and chip outdoor furniture. Homeowners often assume the golfer pays, but proving who hit the ball is usually impossible. In practice, your own homeowners policy typically responds to the damage, subject to your deductible. With a higher deductible, many small ball strikes simply come out of pocket, so it helps to know your numbers before choosing that deductible.
The liability side is less obvious. Course-side homes see golfers retrieving balls, walkers on cart paths, and neighbors cutting through yards. If someone trips on a patio step or gets hurt near a pool, you can be named in a claim even if they had no business being there. Pools, outdoor kitchens, and fire pits add to that exposure.
Check your HOA documents too. Some associations require specific liability limits or have rules about who maintains the strips of land between your lot and the course, which affects who is responsible for an injury there.
Protecting Finished Basements and Water Backup Coverage
Standard homeowners policies often exclude water backup entirely or cap it at a low amount, which is rarely enough for a finished basement in Wexford. Adding a water backup and sump pump failure endorsement with a realistic limit is the fix.
The math explains why. Finishing a basement in Pennsylvania in 2026 costs between $50 and $250 per square foot. A 1,200 square foot lower level finished at the upper end of that range can represent hundreds of thousands of dollars in drywall, flooring, cabinetry, built-ins, and electronics. A small sublimit barely covers removing the wet carpet.
Here is how the claim usually happens. Heavy rain or a fast snowmelt pushes groundwater toward the foundation, the power flickers, and the sump pump stops. Or the municipal sewer line backs up through a floor drain. Neither event counts as flood under most policies, and neither is covered under a standard water damage clause without the endorsement.
When you review your coverage, look at:
- The endorsement limit compared to the actual cost of your finished space
- Whether contents in the basement are included under that limit
- Whether a battery backup or water sensors could earn credits or reduce risk
Flood is a separate policy entirely. If your lot sits near a creek or low area, ask about flood coverage as well.
Bundling High Limit Umbrella Coverage for Total Asset Protection
A high limit umbrella sits on top of your home and auto policies and pays liability claims after their limits are exhausted. For families with significant assets, it is the layer that protects savings, investments, and future earnings from a single serious lawsuit.
The integration works like this: your auto policy might carry $500,000 in liability and your home policy something similar. If a teen driver causes a multi-car accident or a guest suffers a life-altering injury at your pool, a judgment can exceed those limits quickly. The umbrella picks up from there, often in increments of $1 million and beyond. Most umbrella carriers require minimum underlying limits, so the policies must be coordinated.
Bundling also affects price. Bundling home, auto, and umbrella in Pennsylvania typically yields premium savings ranging from 5% to 25%. Statewide data shows home and auto bundles alone can reach as much as 27% in savings with some insurers. One caution: carriers use bundling to keep customers, and moving a single policy often wipes out the multi-policy credit on everything else. Price the whole package before switching one piece.
Standard vs. High Value Coverage Comparison
| Feature | Standard Policy | High Value Policy |
|---|---|---|
| Dwelling settlement | Capped at stated limit | Often extended replacement cost |
| Cash settlement option | Rare | Commonly available |
| Jewelry and art limits | Low sublimits | Higher limits, broader coverage |
| Water backup | Often excluded or low | Higher endorsement limits |
| Home appraisal | Software estimate | On-site appraisal common |
| Umbrella coordination | Basic | Designed for high limits |
Frequently Asked Questions About Wexford Home Insurance
What does high value home insurance cover? It covers your dwelling, belongings, and liability like a standard policy, but with broader replacement cost terms and higher limits for valuables. It is built for custom homes and larger estates.
Do I need extra water backup coverage? If you have a finished basement, yes. Standard policies often exclude or limit sewer and sump pump backup, and a finished lower level can cost far more than that limit to repair.
Does a Wexford address affect my insurance? Your township matters more than the mailing address. Pine, Richland, Franklin Park, and Marshall can differ in fire protection and building patterns, which can affect pricing.
Who pays when a golf ball breaks my window? Usually your own homeowners policy, subject to your deductible, since finding the golfer responsible is difficult.
How much umbrella coverage do I need? A common starting point is enough to match your net worth plus future earnings. Families with teen drivers, pools, or rental properties often carry more.
Can I bundle an umbrella with my home and auto? Yes, and bundling typically lowers the combined premium while making sure your underlying limits meet the umbrella's requirements.
Request a Private Client Review with MVP Insurance
The right policy for a Wexford custom home comes down to a few decisions made well: a dwelling limit based on real rebuilding costs, a water backup endorsement that matches your finished basement, liability limits that reflect your golf course or pool exposure, and an umbrella coordinated with everything underneath it. Get those right and most of the painful surprises disappear.
MVP Insurance was founded in 2008 by Josh Medure and David Varrati as an independent agency, which means we compare options across multiple carriers and work for you rather than any one insurer. Explore our private client insuranceservices, then Request a Private Client Reviewto have your home, auto, and umbrella reviewed together. You can also call or stop by our Zelienople office at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122, or our New Springfield office at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055.
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293. A home you spent years designing deserves coverage that was designed just as carefully.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













