


Owner, MVP Insurance
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
Pennsylvania homeowners insurance covers the big, sudden losses: fire, windstorms, theft and liability. Western Pennsylvania homes face extra risks that a standard policy often leaves out, including mine subsidence, sewer backups and winter water damage. Knowing where those gaps sit, and why premiums have climbed so sharply, helps you buy coverage that actually pays when something goes wrong.
Most homeowners don't discover these gaps until a claim is denied. A basement fills with sewage after a heavy storm, or a crack runs up the foundation wall of a 1920s brick home in Allegheny County, and suddenly the fine print matters. The good news is that nearly every one of these gaps can be closed with the right endorsement or a separate policy. Many are surprisingly affordable once you know to ask for them.
Understanding Pennsylvania Homeowners Insurance Requirements and Risks
Pennsylvania doesn't legally require homeowners insurance, but your mortgage lender almost certainly does. A standard policy protects the structure, your belongings, additional living expenses and personal liability against named or open perils such as fire, wind, hail and theft. What it won't do is account for the specific hazards of living on top of old coal country through long freeze-thaw winters.
Cost is the other story. Pennsylvania premiums rose by an inflation-adjusted 28.9% between 2021 and 2025, the steepest increase in the Philadelphia Fed's Third District. Several factors are behind that jump:
- Rebuilding costs:lumber, labor and specialty materials cost far more than they did five years ago.
- Winter water claims: frozen pipes and ice dams produce frequent, expensive losses.
- Aging homes:older wiring, plumbing and roofs raise the odds of a claim.
- Severe weather:wind and hail events have pushed carrier losses higher.
State regulators do push back. The Pennsylvania Insurance Department saved residents $227.9 million in 2025by reducing or blocking excessive rate filings. Still, individual households feel the squeeze. MVP Insurance works with homeowners from offices in Zelienople, PA and New Springfield, OH. As an independent agency, MVP compares multiple carriers so clients aren't stuck with one company's pricing. You can see the full range of options on our Pennsylvania personal insurance page.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Mine Subsidence Coverage in Western Pennsylvania
Your homeowners policy almost certainly won't pay for mine subsidence damage, because standard policies exclude earth movement. That means you need a separate policy. Standard Pennsylvania policies almost universally exclude damage caused by mine subsidence, and the risk is far from rare. More than 1 million Pennsylvania buildings sit atop abandoned underground coal and clay mines.
Subsidence happens when old mine voids collapse and the ground above sinks. The damage shows up as cracked foundations, doors that suddenly stick, sloping floors and broken utility lines. It can come on slowly over months or appear almost overnight. The repairs are rarely small, since they often require stabilizing the soil beneath the home before any structural work can start.
One mistake we see often: homeowners assume that if they've lived somewhere 30 years without trouble, they're safe. Many of these mines were worked a century ago, and the voids don't announce themselves.
The Pennsylvania Mine Subsidence Insurance Fund
Coverage is generally sold through the Pennsylvania Mine Subsidence Insurance Fund, which the Department of Environmental Protection administers. The program is sizable. Total underwritten value reached about $18.7 billion by early 2025, and the average paid claim was roughly $134,000 in fiscal year 2023.
At its January 21, 2026 meeting, the fund's board confirmed the fund remains stable even though claim severities often top $100,000. To see whether your address falls in a mapped area, DEP offers interactive GIS layers showing "Confirmed" or "Possible" mining risk zones. If you're in Washington, Allegheny, Westmoreland, Beaver or Butler County, look it up. Policies are generally inexpensive compared with the size of a typical claim.

Written By
David Varrati
Owner, MVP Insurance
On this page
Multiple carriers
We quote your home, auto and other policies across the carriers we represent, look at how they pair for discounts, and show you the differences in coverage, not just the price.
Managing Ice Dam and Frozen Pipe Claims
Most homeowners policies cover sudden water damage from a burst pipe or an ice dam leak. They don't cover damage caused by neglect or slow seepage. Western Pennsylvania's freeze-thaw cycles produce a steady stream of these claims every winter. How the claim gets paid usually comes down to whether the loss looks sudden or preventable.
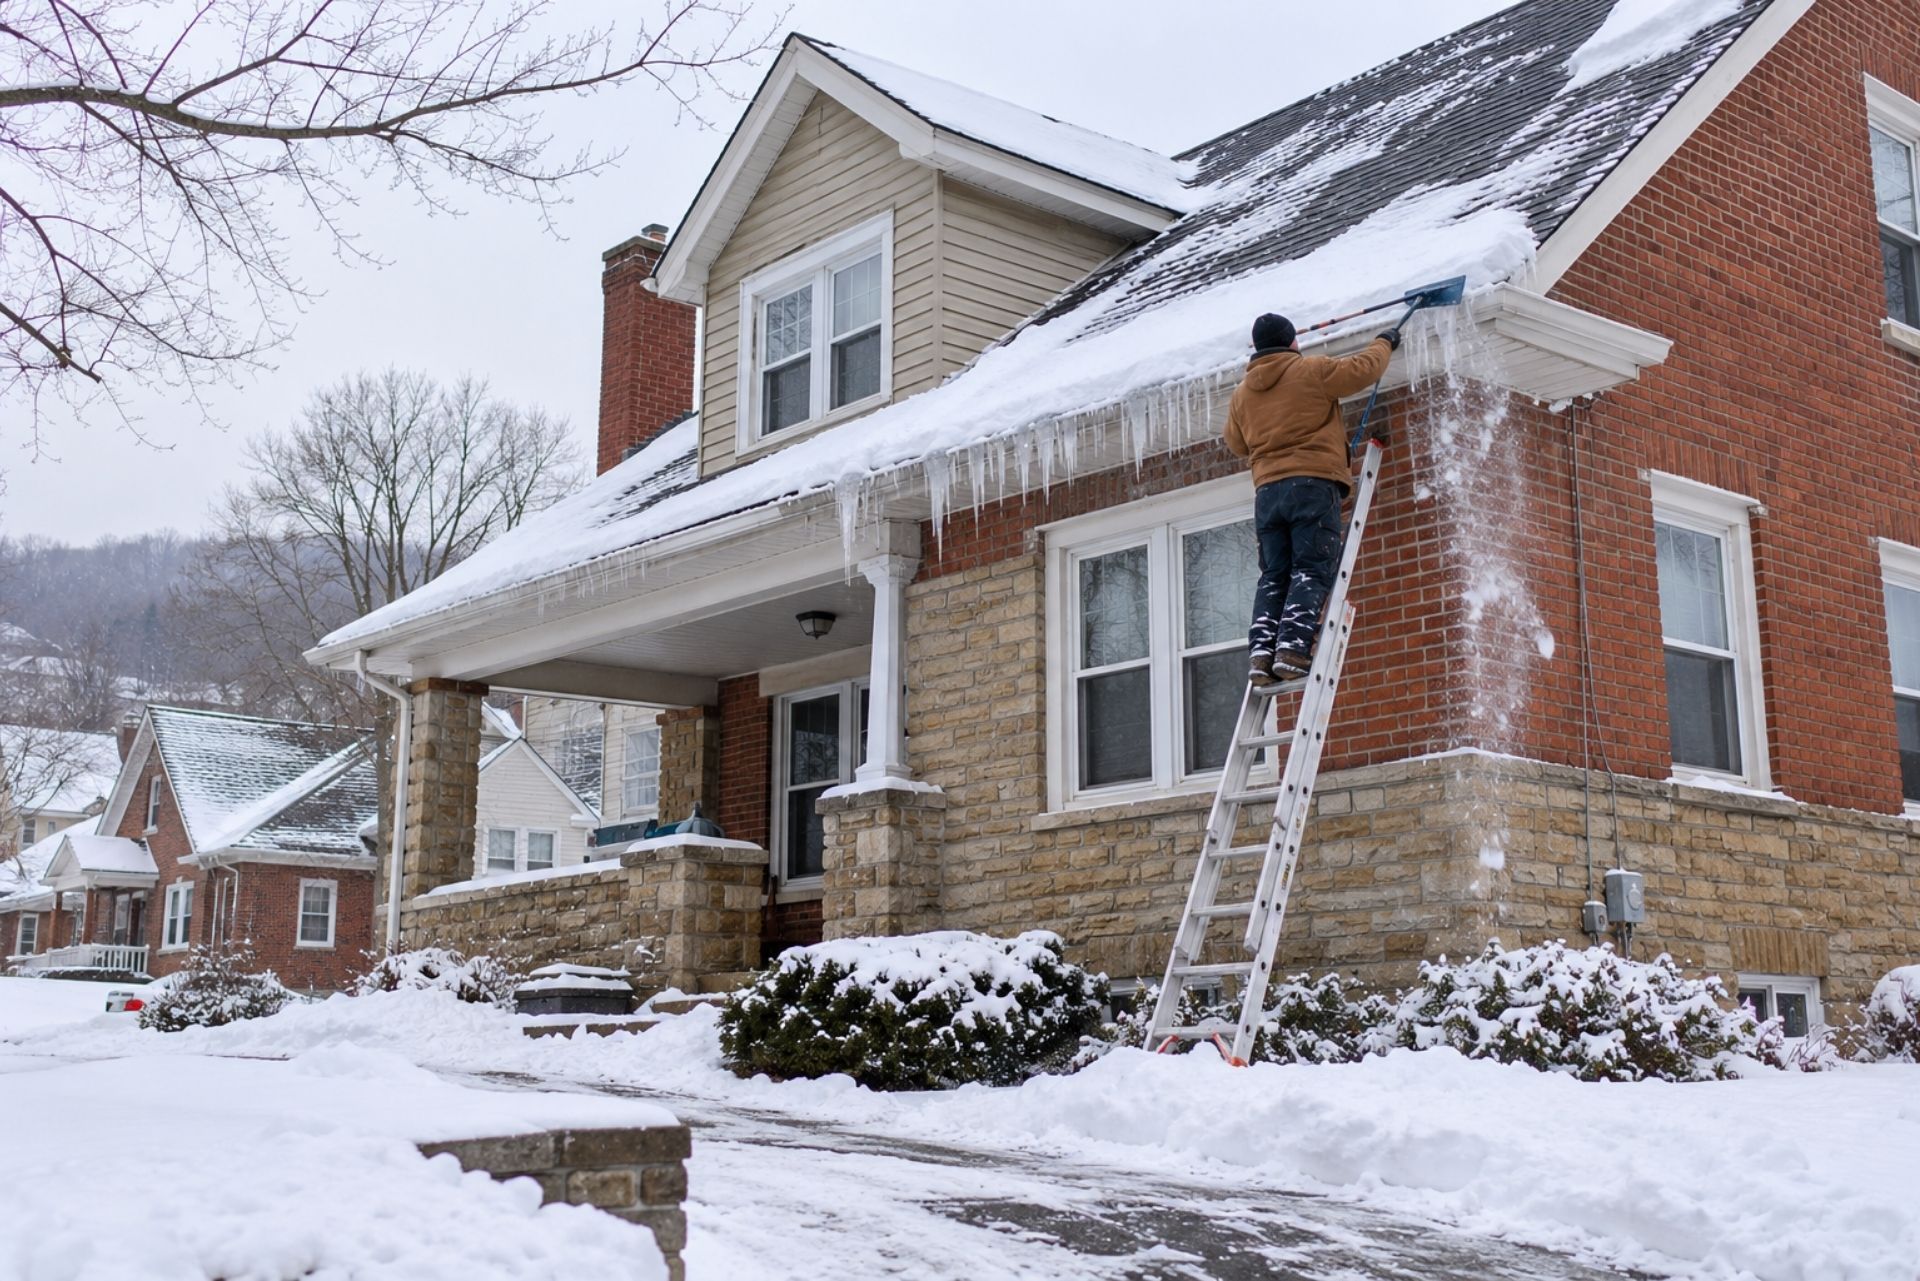
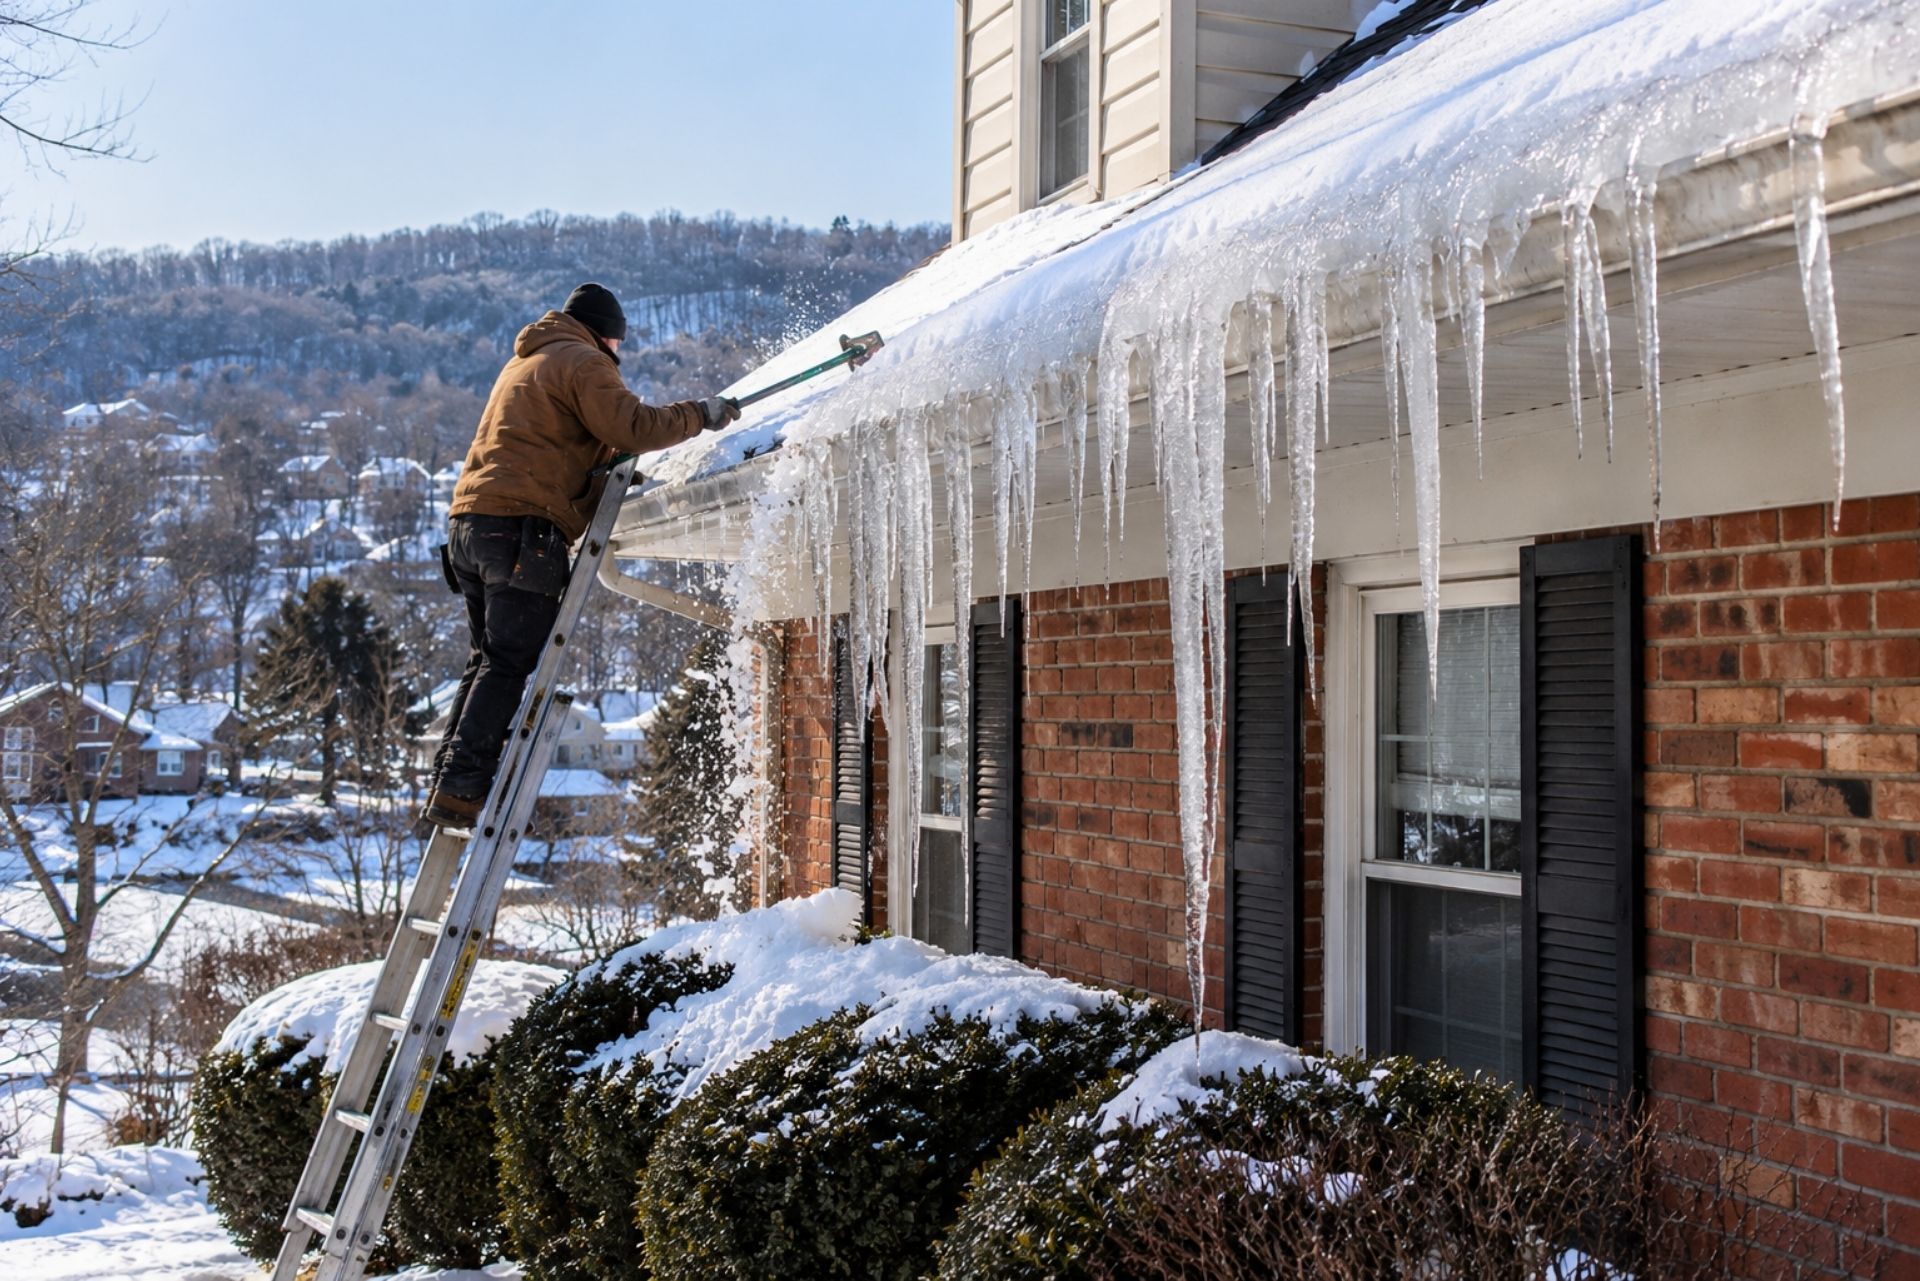
Ice dams form when heat escapes through the attic and melts snow on the roof. The meltwater runs down and refreezes at the cold eaves, then backs up under the shingles and into ceilings and walls. Frozen pipes tend to burst in exterior walls, crawl spaces and unheated garages, often while a family is away over the holidays.
Here's where claims get complicated:
- Vacancy clauses: many policies limit freeze coverage if the home sits unoccupied and you haven't kept the heat on or drained the system.
- Repeated leaks: a ceiling stain that's been growing for three winters reads as maintenance, not a sudden loss.
- The ice dam itself: policies generally pay for interior water damage, not for removing the ice.
Prevention is simple and inexpensive. Add attic insulation and ventilation, seal air leaks around fixtures and keep thermostats at 55°F or higher when you travel. Disconnect hoses before the first hard freeze. A smart water shutoff valve can stop a burst pipe within minutes, and some carriers credit the device on your premium.
Older Housing Stock and Replacement Cost Challenges
Older homes need replacement cost limits based on today's construction prices, not on market value or the original purchase price. Much of the Pittsburgh area housing stock was built before 1940. That means plaster walls, slate roofs, hardwood trim, stone foundations and custom millwork that modern contractors charge a premium to replicate.
The real danger is settling for actual cash value. ACV coverage subtracts depreciation from replacement cost, and on a 90-year-old structure that depreciation can be enormous. Picture a 1925 Mt. Lebanon colonial with a kitchen fire. Under ACV, the settlement might cover only a fraction of the cost to restore the original plasterwork and woodwork, leaving the owner with a large out-of-pocket bill.
A few protections worth asking about:
- Extended or guaranteed replacement cost: adds a cushion of 25% or more above your dwelling limit.
- Ordinance or law coverage: pays to bring old wiring and plumbing up to current code during a rebuild.
- Service line coverage: covers buried water and sewer lines. Underground repairs in cities like Pittsburgh typically run $3,000 to $10,000.
Review your dwelling limit every couple of years. Construction inflation has outpaced many policies that haven't been touched since closing.
Pennsylvania FAIR Plan as a Last Resort
Some older homes can't find coverage in the voluntary market because of age, condition or a past claim. For those homes, the Pennsylvania FAIR Plan generally serves as the state's market of last resort for basic property insurance. It typically offers narrower protection than a standard homeowners policy and often lacks liability coverage. Treat it as a bridge while you update the roof, electrical or plumbing, then shop the regular market again.
Water Backup Endorsements and Why You Need Them
Standard homeowners policies do not automatically cover water that backs up through sewers, drains or a failed sump pump. You need a separate endorsement for it. In a state full of finished basements, this is one of the most common coverage gaps we see.
Picture a summer storm overwhelming a municipal sewer line in Cranberry or Beaver Falls. Wastewater pushes up through the floor drain, soaking carpet, drywall, a furnace and a basement's worth of stored belongings. Without the endorsement, that entire claim is typically denied, even though the policy covers other kinds of water damage.
Water backup and sump discharge endorsements in Pennsylvania typically cost between $40 and $250 a year as of 2026, depending on the limit you choose. Pick a limit that matches what's actually downstairs. A $5,000 limit won't go far if you have a finished family room, a home office and a new HVAC system in the basement. Our blog covers water backup questions in more detail, along with roof replacement and fallen tree claims.
Keep in mind that backup coverage is not flood insurance. Surface water rising from a creek or river requires a separate policy, which you can read about on our Pennsylvania flood insurance page.
Comparing Pennsylvania Property Coverage Options
The coverages below fill the most common gaps in a Western Pennsylvania homeowners policy. Availability varies by carrier, home age and location, so this table shows general patterns rather than guarantees. MVP works with these carriers as an independent agent.
| Coverage | What It Protects | Included in Standard Policy? | Typical Source |
|---|---|---|---|
| Mine Subsidence | Damage from collapsed mine voids | No | PA Mine Subsidence Insurance Fund |
| Water Backup | Sewer, drain and sump overflow | No, endorsement needed | Erie, Westfield, Progressive |
| Replacement Cost (Dwelling) | Rebuild at today's prices | Usually, on dwelling | Erie, Westfield, Progressive |
| Extended Replacement Cost | Extra cushion above limit | No, optional | Erie, Westfield |
| Service Line | Buried utility lines | No, endorsement needed | Erie, Westfield, Progressive |
| Flood | Rising surface water | No, separate policy | Franklin Flood, NEXT, American Bankers |
| FAIR Plan Property | Basic perils for hard-to-place homes | Separate policy | Pennsylvania FAIR Plan |
Older or vacant homes that don't fit standard guidelines may find a home with specialty carriers like Foremost or American Modern.
Frequently Asked Questions About PA Home Insurance
Does my policy cover mine sinkholes? Generally no. Homeowners policies exclude earth movement, so you need a separate mine subsidence policy through the state fund.
Is water backup the same as flood insurance? No. Water backup covers sewer and drain overflow, while flood insurance covers rising surface water from outside the home.
Will insurance pay for a pipe that froze while I was away? Usually yes, as long as you kept the heat on or drained the plumbing. Many policies limit coverage for homes left vacant without either precaution.
Why did my homeowners insurance go up in Pennsylvania? Higher rebuilding costs, frequent winter water claims, aging homes and severe weather have all pushed premiums higher statewide.
Should I get replacement cost or actual cash value? Replacement cost is the safer choice, especially for older homes. ACV subtracts depreciation and can leave you paying a large share of repairs yourself.
What if no company will insure my old house? The Pennsylvania FAIR Plan typically provides basic property coverage when the regular market declines a home.
Protecting Your Western Pennsylvania Home
The pattern here is consistent: the risks most likely to hit a Western Pennsylvania home are the ones a basic policy leaves out. Mine subsidence needs its own policy. Basement backups need an endorsement. Older homes need replacement cost limits that reflect what plaster, slate and stone actually cost to restore today. Rates have climbed, but paying for a policy that fails at claim time costs far more.
An independent agent can compare these options across carriers in one conversation rather than making you call a dozen companies. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. If you'd like a fresh look at your coverage from our Zelienople or New Springfield office, start your quoteand we'll handle the comparison shopping. Spend a few minutes on it now, before the next hard freeze or summer storm.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













