


Fox Chapel PA High Value Home Insurance

Owner, MVP Insurance

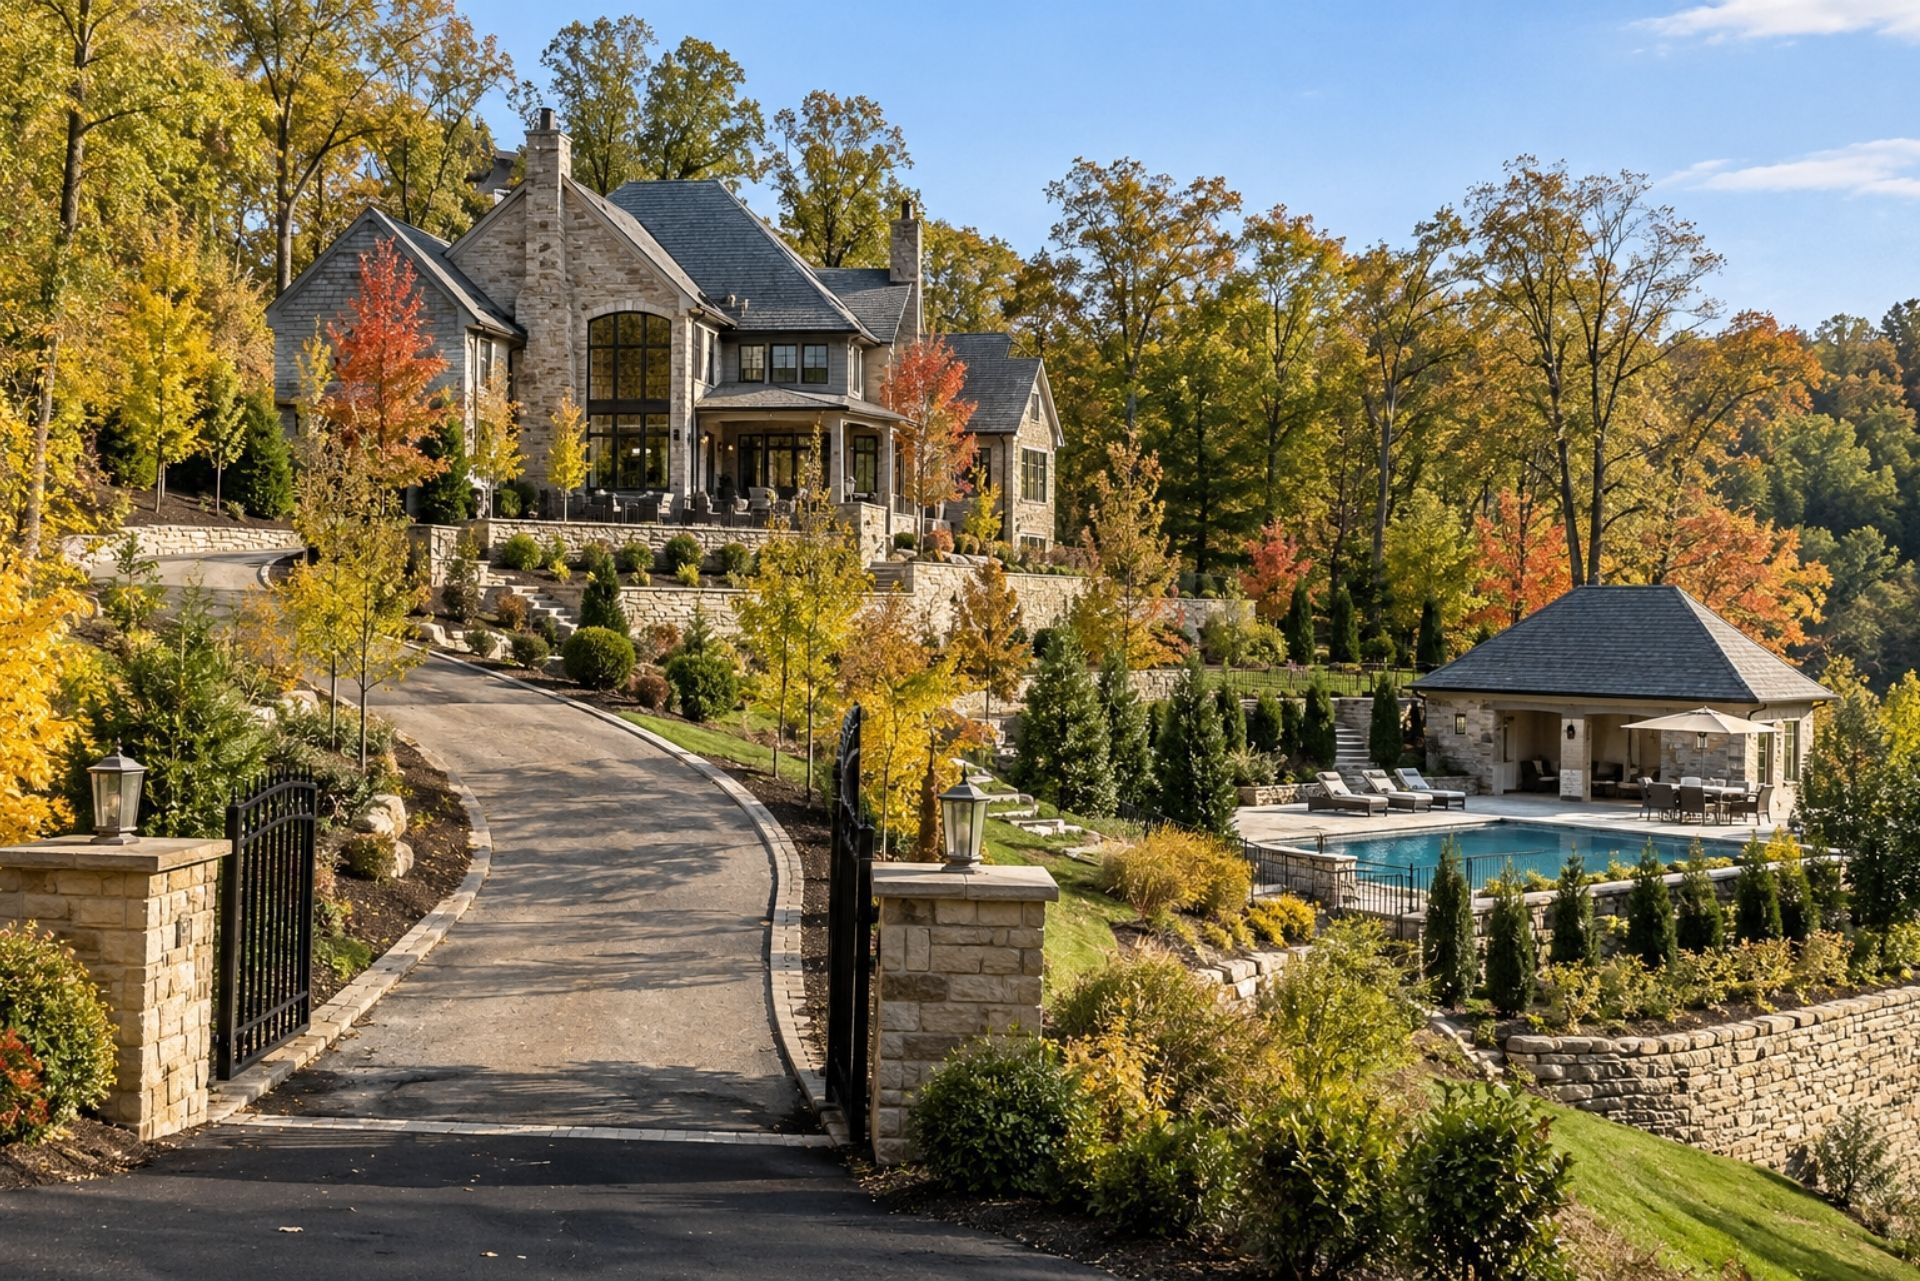
Fox Chapel homes need more than a standard homeowners policy. Wooded acreage, steep slopes, long private drives, pools and guest houses create exposures that basic coverage either excludes or underinsures. The right high value policy pairs accurate replacement cost with earth movement solutions, stronger Other Structures limits and liability protection sized to your net worth.


That's the short answer. The longer one depends on your property. A stone colonial set back 600 feet from Fox Chapel Road, surrounded by mature oaks on a hillside, carries very different risks than a typical suburban house. Insurance written for that typical house tends to show its gaps at the worst possible moment: after a storm, a slope failure or a lawsuit.


Rising costs make getting this right more urgent. Pennsylvania homeowners saw roughly a 44% cumulative premium increase between 2021 and 2024. Many estate owners responded by trimming coverage, and that is often the wrong lever to pull. Paying for the right coverage beats paying less for coverage that won't respond.

The Essentials of Fox Chapel PA High Value Home Insurance

Fox Chapel PA high value home insurance is built around specialized underwriting, because these estates don't fit standard rating models. A carrier writing an ordinary policy might plug square footage into a formula and produce a replacement cost that ignores slate roofs, custom millwork, hand-laid stone walls and the cost of hauling materials up a steep, wooded lot. That number can come in far short of what a rebuild actually costs.


High value policies typically offer features standard forms don't. These include guaranteed or extended replacement cost, cash settlement options if you choose not to rebuild, and higher sublimits for jewelry, art and wine. They also offer broader liability options. Our Pennsylvania high value home insurancepage walks through these in more detail.


The common mistake we see is a policy that was accurate when the home was purchased but never updated after renovations, a guest house addition or a new pool. MVP Insurance conducts Private Client reviews to catch exactly these gaps. Because we're independent, we compare options across multiple markets rather than fitting your estate into one carrier's mold.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Insuring Wooded Estates on Steep Lots

Wooded, sloped lots are part of what makes Fox Chapel beautiful, and they're also a real insurance challenge. Large wooded lots on steep terrain are typical here. The borough actively protects that character: at least 30% of a tract must be preserved as undisturbed common open space under Planned Residential Development rules. More trees mean more potential for falling limbs, root damage and storm debris.


Tree removal coverage is usually limited. Many standard policies pay to remove a fallen tree only if it hits a covered structure or blocks a driveway, and then often with a small per-tree cap. On a property with dozens of mature hardwoods, a single windstorm can produce cleanup bills that dwarf those limits. High value forms often offer higher landscaping and tree limits, which matters if your trees and plantings represent decades of growth.


Here's the critical gap: standard homeowners policies typically exclude damage caused by the weight or movement of earth, including slope instability. If a hillside shifts and cracks your foundation, or a retaining wall gives way under saturated soil, your policy may deny the claim entirely. The borough even uses geological hazard maps that flag high landslide-prone slopes in red and moderate risk areas in yellow, so your lot's classification is worth knowing before a claim ever happens.

Closing the Landslide and Earth Movement Gaps

As of this writing, landslide damage is generally excluded from standard homeowners policies, and high value policies usually follow the same pattern unless you add coverage. The shifting clay soils common across Western Pennsylvania make this one of the most overlooked exposures for Fox Chapel owners. State lawmakers have acknowledged the problem directly, noting that property owners cannot purchase insurance for landslides like they can for floods.


There is movement on that front. The Protecting Pennsylvanians from Landslides Act (House Bill 589) is designed to create a state-run program offering up to $150,000 in coverage for natural slope movement. For a multimillion dollar estate, though, that cap won't cover a full foundation and structural repair. Until such a program is fully in place, your options generally include:


  • Earth movement endorsements: Some high value forms can add limited coverage for earth movement or collapse.
  • Separate difference-in-conditions or earth movement policies: These are written outside the homeowners policy for specific perils.
  • Ensuing loss provisions: These cover resulting fire or water damage even when the movement itself is excluded.


Read the wording carefully. "Sinkhole" coverage and "landslide" coverage are not the same thing.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Risk Management for Pools and Guest Houses

Guest houses and luxury pools need higher Other Structures limits and stronger liability protection than most policies include by default. Standard forms usually set Other Structures at 10% of the dwelling limit. That might sound generous on a large home, but a finished guest house with a kitchen, a pool house, stone patios, a detached garage and fencing can easily exceed it.


High value policies typically let you schedule each structure at its true replacement cost, or raise the percentage significantly. They also tend to treat a guest house more like a dwelling, with broader coverage for its contents and systems. If a family member lives there, or you occasionally rent it, tell your agent. Rental use can change how the structure is rated and covered.


Pools raise the liability stakes. A drowning or diving injury at a summer party can generate claims well beyond the $100,000 to $300,000 personal liability limit often found in standard policies. Practical steps that help both safety and underwriting:


Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Unique Coverage for Long Driveways and Private Roads

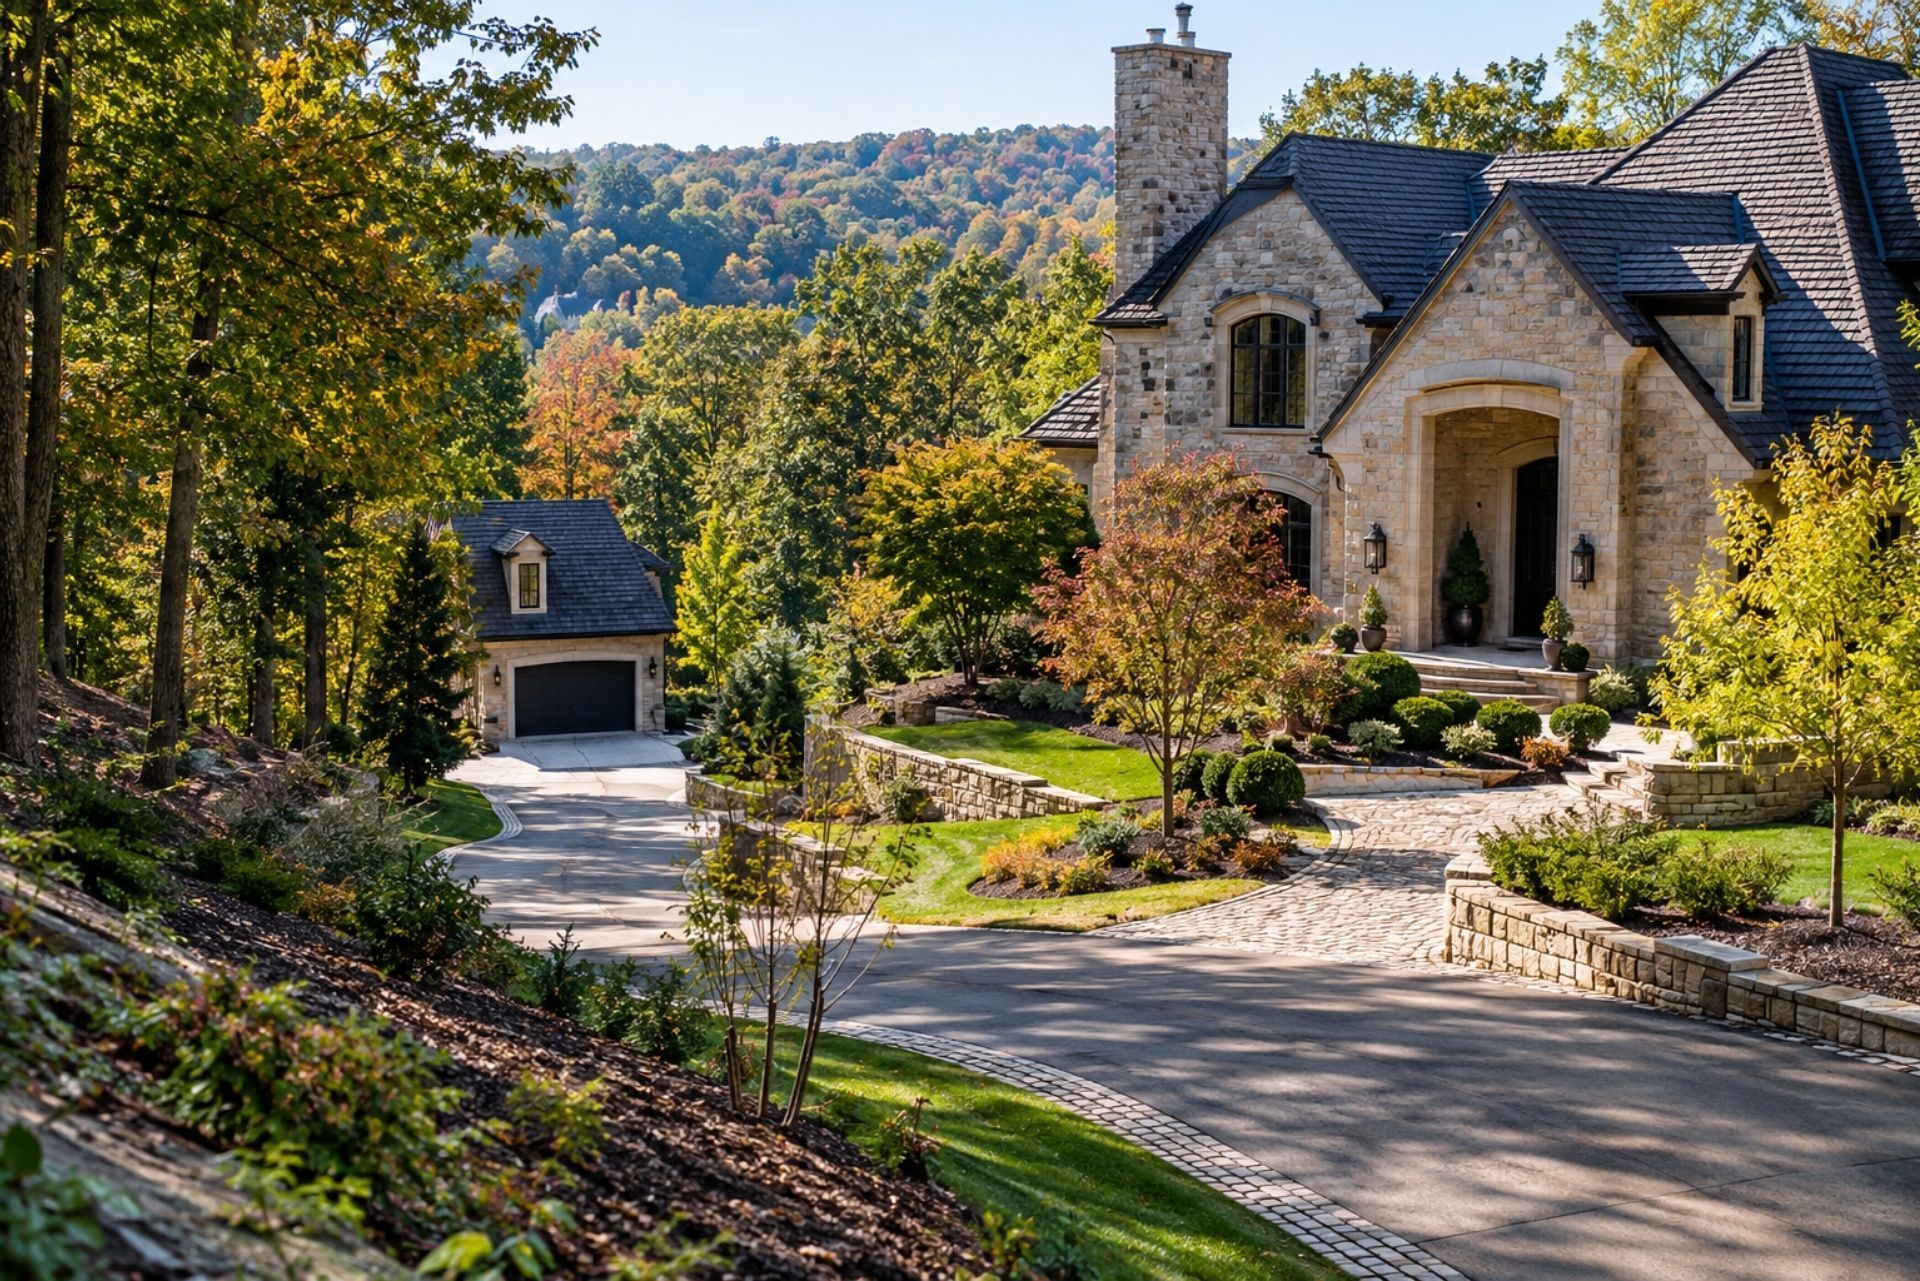
Long private driveways need their own attention because repairs and debris clearing often fall entirely on you. Under Pennsylvania's Private Road Act, homeowners on landlocked or long private drives are responsible for maintaining those roads. In Fox Chapel, where some estate entries wind several hundred feet through woods and down grades, that responsibility gets expensive fast.


Think about what a serious storm actually does. Downed trees block the drive, culverts wash out, and heavy equipment brought in for cleanup cracks the asphalt. Many owners assume their policy handles all of this, but standard limits for paved surfaces, debris removal and trees are often written with a short suburban driveway in mind.


High value policies generally give you more room through higher debris removal limits, broader Other Structures coverage that can include paved surfaces, gates and lighting, and fewer per-item caps. Shared private roads add a liability wrinkle too. If a neighbor or delivery driver is hurt on a poorly maintained section, you may be pulled into the claim. Document your maintenance and ask how your policy treats a shared road.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Why Fox Chapel Estates Require Higher Liability Limits

Your liability limits should reflect your household's total net worth, not just your home's value. A plaintiff's attorney looks at everything: investment accounts, business interests, other real estate and future earnings. Pools, guest houses, household staff, teen drivers and frequent entertaining all expand the ways a claim can start.


Umbrella policies fill that space. To qualify for high-limit umbrella coverage in 2026, carriers typically require an underlying personal liability limit of $500,000 to $1,000,000. Owners of estates exceeding $5 million are increasingly choosing umbrella limits between $10 million and $25 million, largely in response to so-called nuclear verdicts that have pushed jury awards far beyond historical norms.


A common mistake is buying a $1 million umbrella years ago and never revisiting it while assets grew tenfold. Another is mismatched underlying limits across home, auto and watercraft policies, which can leave an unexpected gap. Ask for a coordinated review. Our broader private client insuranceapproach is built around aligning every policy so coverage stacks cleanly.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Comparing High Value Policy Features

The clearest way to see the difference is side by side. Here's how a standard homeowners policy and a typical high value policy usually compare on the issues that matter most for Fox Chapel properties.

Feature Standard Policy High Value Policy
Dwelling settlement Replacement cost up to limit Extended or guaranteed replacement, cash option
Other Structures Usually 10% of dwelling Higher limits, scheduled structures
Tree and landscaping Low per-tree caps Higher limits, broader triggers
Earth movement Generally excluded Generally excluded; endorsements may be available
Debris removal Modest limit Higher limit
Valuables Low sublimits Higher sublimits, blanket options
Liability Often $100K to $300K $500K to $1M+, umbrella-ready

Notice the earth movement row. Even premium forms rarely solve that gap by default, which is why it deserves its own conversation during any review.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Coverage What It Protects Common Gap to Watch
Homeowners Dwelling, belongings, liability High wind/hail deductibles
Renters Belongings, liability, living costs Low liability limits
Auto Vehicle damage, injury liability State minimum limits only
Motorcycle Bike, gear, liability Custom parts excluded
Boat Hull, motor, liability on water Trailer or navigation limits
Umbrella Excess liability above other policies Underlying limits too low
Life Income replacement for family Only employer coverage

Frequently Asked Questions About Fox Chapel Home Insurance

Does homeowners insurance cover landslides in Pennsylvania? Generally, no. As of this writing, landslide and earth movement damage is typically excluded, so you'll need a specific endorsement or a separate policy.


What counts as a high value home? It usually means a home with a replacement cost well above average, often with custom features. The label matters less than whether your policy accurately reflects rebuild costs.


Will my policy pay to remove a tree that fell in my yard? Often only if it damaged a covered structure or blocked your driveway, and usually with a per-tree cap. High value policies tend to offer higher limits.


Is a guest house covered under my homeowners policy? Typically under Other Structures, which may be too low for a finished guest house. You can usually raise that limit or schedule the building separately.


How much umbrella coverage do I need? Enough to protect your total net worth, including investments and future income. Many estate owners carry $10 million or more.


Is my long driveway covered after a storm? Partially, in most cases. Debris removal and paved surface limits are often low for long estate drives.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Request a Private Client Review with MVP Insurance

The safest Fox Chapel estate policy is one built around your actual property: the slope behind the house, the trees along the drive, the guest house, the pool and everything you've built financially. Standard forms leave predictable gaps in earth movement, tree removal, Other Structures and liability, and closing them takes a careful, line-by-line look.


MVP Insurance was founded in 2008 by Josh Medure and David Varrati, and the agency has served Pennsylvania and Ohio families from its offices at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122, and 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. As an independent agency, MVP shops multiple markets on your behalf and backs you with 24/7 claims support. MVP is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


If your coverage hasn't been reviewed since your last renovation or market jump, now is the time. Request a Private Client Reviewand find out where your estate stands before the next storm or slope shift tests it.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania







