


Owner, MVP Insurance
Coverage
Home
A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.
Auto
Auto insurance covers injuries and damage you cause to others, and with collision and comprehensive, your own vehicle too. Ohio and Pennsylvania set different minimums and Pennsylvania adds a tort choice, so we walk you through both before you pick limits.
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
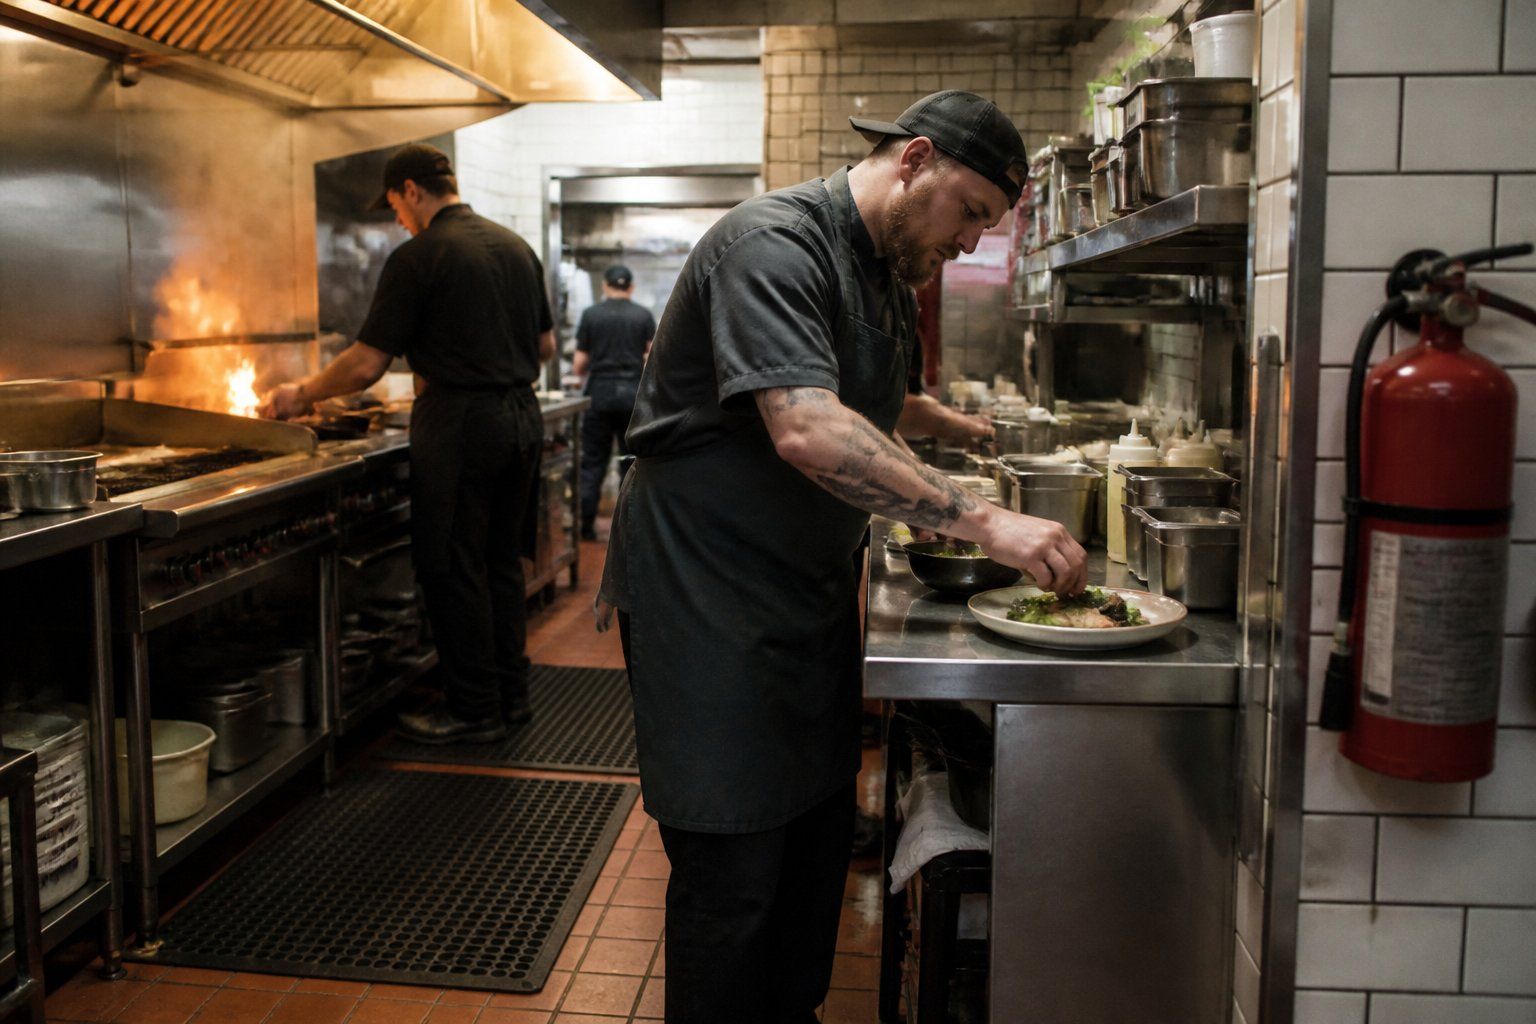
A Pennsylvania restaurant needs more than one policy. A complete package typically combines general liability, liquor liability, property coverage with spoilage and equipment breakdown, workers compensation, and hired and non-owned auto. Each one covers a different way a busy dining room, bar, or kitchen can produce a costly claim.
Most owners find this out after something goes wrong. A server pours one drink too many on a Friday night. A fryer flares up during the lunch rush. A storm knocks out power and takes $4,000 worth of proteins with it. A dishwasher slips on a wet floor mat. Each of these falls under a different coverage, and a missing piece can turn a bad week into a lawsuit you pay for yourself. The sections below explain where those risks come from, which policy responds, and where restaurant owners in western Pennsylvania most often leave gaps.
Essential Pennsylvania Restaurant Insurance Coverage
Pennsylvania restaurant insurance is a bundle of coverages built for food service. The core pieces are general liability, liquor liability, commercial property, and workers compensation, and many carriers sell them together as a business owners policy with endorsements added on. No single form covers everything a restaurant faces, which is why the bundle matters.
Food service carries risks that a retail shop or office does not. You have open flames, hot oil, alcohol, perishable inventory, crowded floors, and staff working long, fast shifts. A policy written for a generic small business often excludes or caps the claims restaurants file most often.
MVP Insurance is an independent agency founded in 2008 by Josh Medure and David Varrati. Because we are not tied to one carrier, we compare restaurant packages across several companies and match coverage to how your place actually operates, whether that means a full bar, BYOB, or delivery.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Liquor Liability Under the Dram Shop Law
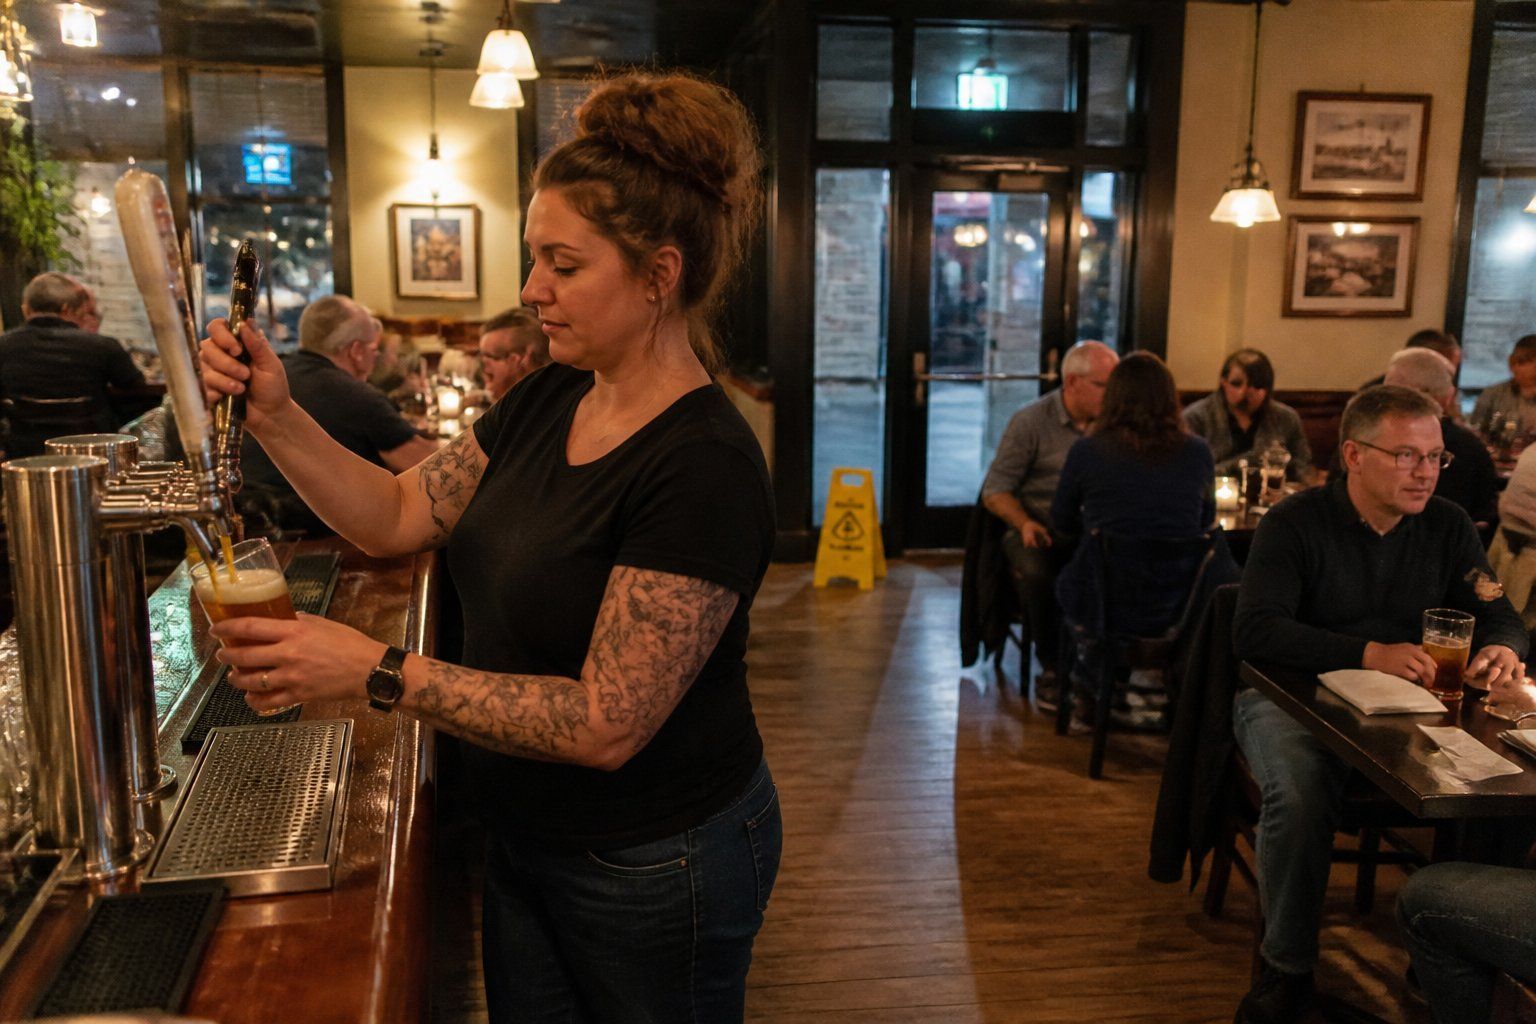
Pennsylvania's dram shop law generally makes liquor licensees liable when they serve a visibly intoxicated patron who then injures someone. If that guest leaves your bar and causes a crash, the injured party can come after your business. General liability policies usually exclude this, so licensed restaurants need a separate liquor liability policy.
Liquor licenses in the state are issued by the Pennsylvania Liquor Control Board, and the PLCB also offers RAMP, the Responsible Alcohol Management Program. RAMP certification trains servers to spot intoxication and refuse service properly. Underwriters view it favorably, and in a dram shop lawsuit it gives you evidence that you took reasonable steps.
Licensees have also faced regulatory shifts this year. On June 15, 2026, the state Supreme Court ruled that casino-style skill games are illegal, with a 120-day enforcement stay that ended October 14. Licensees still holding those machines now face criminal charges and PLCB citations, and a citation can complicate your liquor coverage at renewal.
Host Liquor Exposure for BYOB Establishments
Skipping a liquor license does not erase the risk. A BYOB restaurant that lets guests bring wine or beer still carries host liquor exposure. If a guest drinks too much at your table and hurts someone, a plaintiff's attorney will name your business. Host liquor coverage is often available as an endorsement on general liability, and it costs far less than defending a claim without it.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Protecting Against Kitchen Fires and Spoilage
The most common property claims for local eateries come from three sources: kitchen grease fires, equipment breakdown, and food spoilage after a power outage. A solid property policy needs to address all three, and standard forms do not always do that automatically.
Grease fires are the obvious one. Hood suppression systems and regular duct cleaning help, and many carriers expect documented inspections before they will write the policy. A fire claim should cover the building or your tenant improvements, equipment, inventory, and business income while you are closed.
Equipment breakdown is different. When a walk-in compressor or a combi oven fails from an electrical or mechanical problem, basic property coverage usually will not pay because nothing burned or flooded. You need an equipment breakdown endorsement.
Spoilage coverage pays for food lost when refrigeration fails or utility power goes out. Watch the details here. Some policies only cover outages that start on your premises, so a grid failure down the road leaves you uncovered unless you add off-premises utility service coverage.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Managing Slip-and-Fall Claims and General Liability
Slip-and-fall claims fall under general liability insurance. When a customer slips on a spilled drink, trips over a floor mat, or falls on an icy entrance in January, your GL policy pays for their medical bills, your legal defense, and any settlement or judgment up to your limit.
These are among the most frequent claims restaurants file, and they are rarely small. A broken wrist or hip can lead to surgery, lost wages, and a demand well into six figures. Courts look at whether you knew about the hazard and how quickly you responded, so a written floor-check log and wet floor signs help your defense considerably.
One mistake we see often: owners assume a GL policy also covers employees who fall. It does not. Staff injuries go to workers comp. You can read more about how general liability coverage in Pennsylvania works, or see how we handle other food and hospitality businesses on our industries page.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Workers Comp for Kitchen Staff
Pennsylvania requires most employers to carry workers compensation, and a commercial kitchen is a hard place to work. Line cooks get burned by fryers and flat tops. Prep cooks cut fingers on knives and slicers. Dishwashers slip on wet tile, and servers strain their backs hauling bus tubs. Workers comp pays medical bills and a portion of lost wages, and it generally shields you from being sued by the injured employee.
Rates depend on payroll and job classification. The state's employer assessment factor for the 2026 rating year dropped slightly, to 0.0218 from 0.0222. Base loss costs are only part of the price, though. Each carrier applies its own loss cost multiplier, which typically adds 20 to 50 percent for expenses, so two quotes on the same payroll can differ a lot. That spread is a strong reason to compare carriers.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Delivery Driver Exposure and Hired and Non-Owned Auto
If your employees deliver food in their own cars, your restaurant has hired and non-owned auto exposure. When a driver rear-ends someone during a delivery, the injured party will often sue the restaurant, since the driver was working for you at the time.
The driver's personal auto policy may not respond at all. Many personal policies exclude commercial use like food delivery, and even when they pay, limits are often low. Your GL policy almost certainly excludes auto claims.
Hired and non-owned auto (HNOA) coverage fills that gap. It protects the business, not the employee's car, against liability claims from accidents during work errands, including delivery runs and the manager's trip to the restaurant supply store. It is usually added to a business owners or commercial auto policy at modest cost. Anyone delivering for you should also carry their own coverage that allows delivery use.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Comparing Restaurant Coverage Limits and Carriers
Limits should reflect your seating, revenue, and how much alcohol you sell. The table below shows the limits restaurants commonly carry, though a lender, landlord, or the PLCB situation can push those higher.
| Coverage | What It Covers | Common Limits |
|---|---|---|
| General liability | Customer injuries, slip-and-falls | $1M per occurrence / $2M aggregate |
| Liquor liability | Dram shop claims | $1M per occurrence |
| Host liquor | BYOB guest incidents | Often matches GL limit |
| Property | Building, equipment, inventory | Replacement cost of assets |
| Spoilage | Food lost to outages | $10K to $50K |
| Workers comp | Employee injuries | Statutory, plus employers liability |
| HNOA | Delivery driver accidents | $1M combined single limit |
| Umbrella | Excess over GL, liquor, auto | $1M to $5M |
As an independent agency, we work with carriers including Erie, Westfield, Progressive, and Frederick Mutual. Each has different appetites. Some favor family restaurants with limited alcohol, while others write bars and late-night spots more comfortably, so the right fit depends on your menu and hours.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Frequently Asked Questions About Restaurant Insurance
Do I need liquor liability if I only sell beer and wine?
Yes. Pennsylvania's dram shop law applies to any licensee serving alcohol, regardless of what kind.
Does my BYOB restaurant need liquor coverage?
You need host liquor coverage, usually added to your general liability policy. BYOB guests can still create claims against your business.
Is RAMP certification required in Pennsylvania?
Requirements vary by license situation, but RAMP training is offered by the PLCB and generally helps with underwriting and in court.
Will insurance pay for food lost in a power outage?
Only if you carry spoilage coverage. Add off-premises utility coverage if you want outages that start away from your building covered too.
Who pays if my delivery driver crashes?
The injured party may sue your restaurant. Hired and non-owned auto coverage protects the business in that situation.
Does general liability cover employee injuries?
No. Employee injuries go through workers compensation.
Written By
David Varrati
Owner, MVP Insurance
On this page
Next step
What to have ready
Your address, the year, make and model of each vehicle, the drivers in the household, a rough list of valuables, and your current declarations pages if you have them. Contact either office or visit the Client Center if you already have a policy with us.
01
Tell us about your household
Your home, your vehicles, your drivers and anything else you want protected.
02
Import your current policies through Canopy or send your declarations
Use Canopy to share what you have today, or send us the declarations pages.
We shop and compare the carriers we represent
We compare coverage and price, then explain the differences in plain terms.
03
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Consult With an Independent Agent in Zelienople
Restaurant claims tend to arrive at the worst possible time: mid-rush, mid-storm, or at 1 a.m. after last call. The owners who come through them well usually set up their coverage before anything happened. That means liquor or host liquor protection that fits how alcohol moves through the building, property coverage that includes breakdown and spoilage, workers comp priced across several carriers, and HNOA for anyone driving on your behalf.
If you want a second set of eyes on your current policy, reach out to Josh Medure at our Zelienople office, 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122, or our New Springfield office at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. We will walk through your setup and compare restaurant packages from multiple carriers on your behalf. When you are ready, you can start your quote online in a few minutes.
MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
Joshua Medure
Owner, MVP Insurance
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto

Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.


Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.







