

Owner, MVP Insurance
Wexford PA business insurance usually starts with a Business Owners Policy for property and general liability, then adds professional liability, cyber coverage, workers' compensation, and commercial auto as your risks require. Medical offices, consultants, and Perry Highway retailers each need a different mix. An independent agent can compare carriers so the pieces fit together without gaps.
That short answer hides plenty of nuance. A physical therapy practice in a Pine Township office park faces different claims than a boutique near the Route 19 and Wexford Bayne intersection. A three-person accounting firm in Franklin Park may never see a slip-and-fall but could easily lose client tax files to ransomware. The coverage that protects one business can leave another exposed.
The good news is that 2026 is a reasonable year to shop. Many sectors of the commercial market are behaving like a buyer's market, with carriers competing for well-run small accounts even as rising jury awards push liability pricing up in some lines. That combination rewards owners who review their policies carefully instead of renewing on autopilot. The sections below break down what North Hills firms actually need, where common gaps appear, and how to build a program that holds up when a claim lands on your desk.
Wexford PA Business Insurance for North Hills Firms
Wexford business insurance protects companies in Pine, Richland, Franklin Park, and Marshall townships from the liability and property losses that can sink a small operation. Because the Wexford mailing address spans four townships, your actual location affects local permits, fire protection ratings, and sometimes the rates a carrier offers.
That four-township footprint trips people up more than you might expect. A business owner may describe the shop as "in Wexford" on an application when the property technically sits in Marshall or Richland. Carriers rate property based on the specific address, the responding fire department, and distance to hydrants, so accuracy matters. A mismatch can lead to a premium adjustment at audit or, worse, a dispute when a claim is filed.
The area's mix of businesses also shapes coverage needs. Wexford has a dense concentration of medical and dental practices, financial advisors, attorneys, engineering consultants, and retail shops serving families who moved to the North Allegheny and Pine-Richland school districts. Each of those groups carries its own risk profile:
- Healthcare and professional offices:malpractice and errors-and-omissions exposure, plus sensitive client data
- Retail along Route 19:customer injuries, inventory losses, and storefront damage
- Contractors and service businesses:vehicles, tools, and job-site liability
- Restaurants and food service:spoilage, liquor liability, and kitchen fires
MVP Insurance works with North Hills firms from offices in Zelienople and New Springfield, close enough to understand the Butler County and northern Allegheny County business climate. As an independent agency, MVP shops multiple carriers rather than pushing one company's product. You can read more about statewide options on the Pennsylvania business insurancepage, and if you also drive for work or need personal coverage, the Wexford car insurancepage covers local auto considerations.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
| Feature | DP-1 (Basic) | DP-3 (Special) |
|---|---|---|
| Covered perils | Named perils only | All risks, minus exclusions |
| Building settlement | Usually actual cash value | Usually replacement cost |
| Sudden water damage | Often excluded | Usually covered |
| Theft/vandalism | Optional, limited | Typically included |
| Loss of rent | Often optional | Usually included |
| Liability | Often an add-on | Add-on or included |
| Best fit | Older, low-value homes | Most modern rentals |
| PA legal requirement | None by state law | None by state law |
Coverage for Medical and Professional Offices
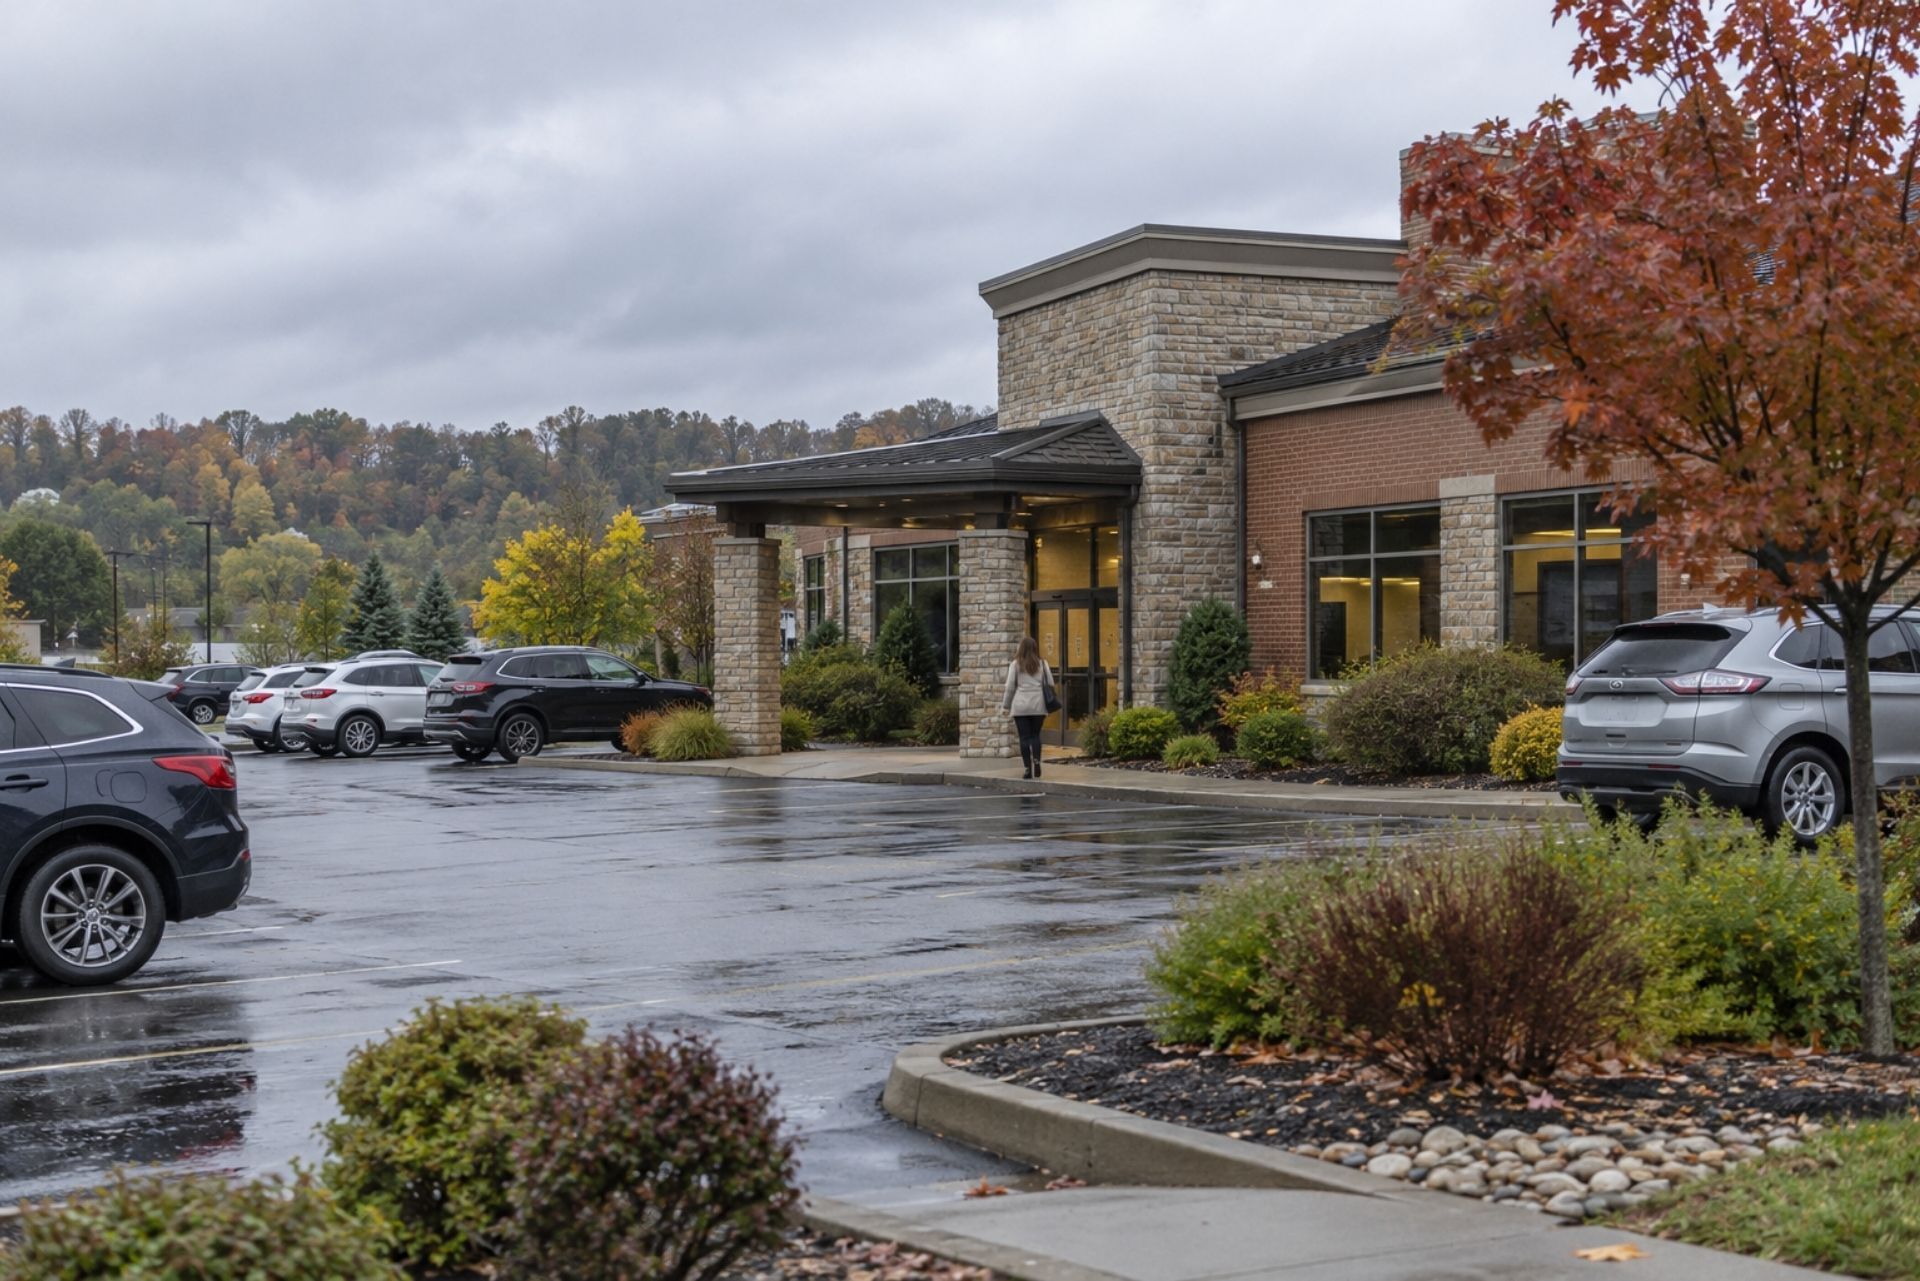
Medical and professional offices in the North Allegheny and Pine-Richland areas need policies built around patient data, specialized equipment, and the advice they give. A standard general liability policy covers a patient tripping in the waiting room, but it won't touch a claim that your diagnosis or recommendation caused harm.
Think about what actually sits inside a typical Wexford medical suite. A dental office may hold $150,000 or more in imaging equipment, sterilization units, and chairs. A dermatology practice might have lasers that cost as much as a house. Many owners insure these items at the building contents level without realizing that equipment breakdown, such as a power surge frying an X-ray unit, often requires a separate endorsement.
The other major issue is business income. If a burst pipe floods your suite in January, how long until you can see patients again? Specialized equipment can take weeks to replace, and medical build-outs require inspections. Business income coverage should reflect a realistic recovery period, not the default 30 or 60 days some policies include.
Leased space adds another wrinkle. Most office leases in the Wexford corridor require tenants to carry specific liability limits and name the landlord as an additional insured. Many also make tenants responsible for improvements they paid for, like custom cabinetry or plumbing for dental chairs. If your policy doesn't cover those tenant improvements, you could be paying twice: once to build them and again to rebuild after a fire.
Professional Liability for North Hills Practitioners
Professional liability, also called errors and omissions or malpractice coverage depending on the profession, pays for defense and settlements when a client claims your work caused them financial or physical harm. For physicians, the coverage is medical malpractice. For accountants, engineers, financial planners, and consultants, it's E&O.
A few nuances catch practitioners off guard:
- Claims-made versus occurrence: Most professional policies are claims-made, meaning the policy in force when the claim is filed responds, not the one in force when the work happened.
- Tail coverage: If you retire, sell your practice, or switch carriers, you may need an extended reporting period to cover claims that surface later.
- Prior acts: When changing carriers, confirm the new policy covers work you did before the switch.
- Defense inside limits: Some policies reduce your available limit as legal bills pile up.
The most common mistake we see is a consultant who goes independent and assumes their old employer's policy still protects them for past projects. It usually doesn't.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
HCertificates of Insurance for Pennsylvania Contracts
Canopy import
Share your current policies in a few clicks through Canopy. We see exactly what you have today, so the comparison is apples to apples.
Retail Insurance Along Perry Highway and Route 19
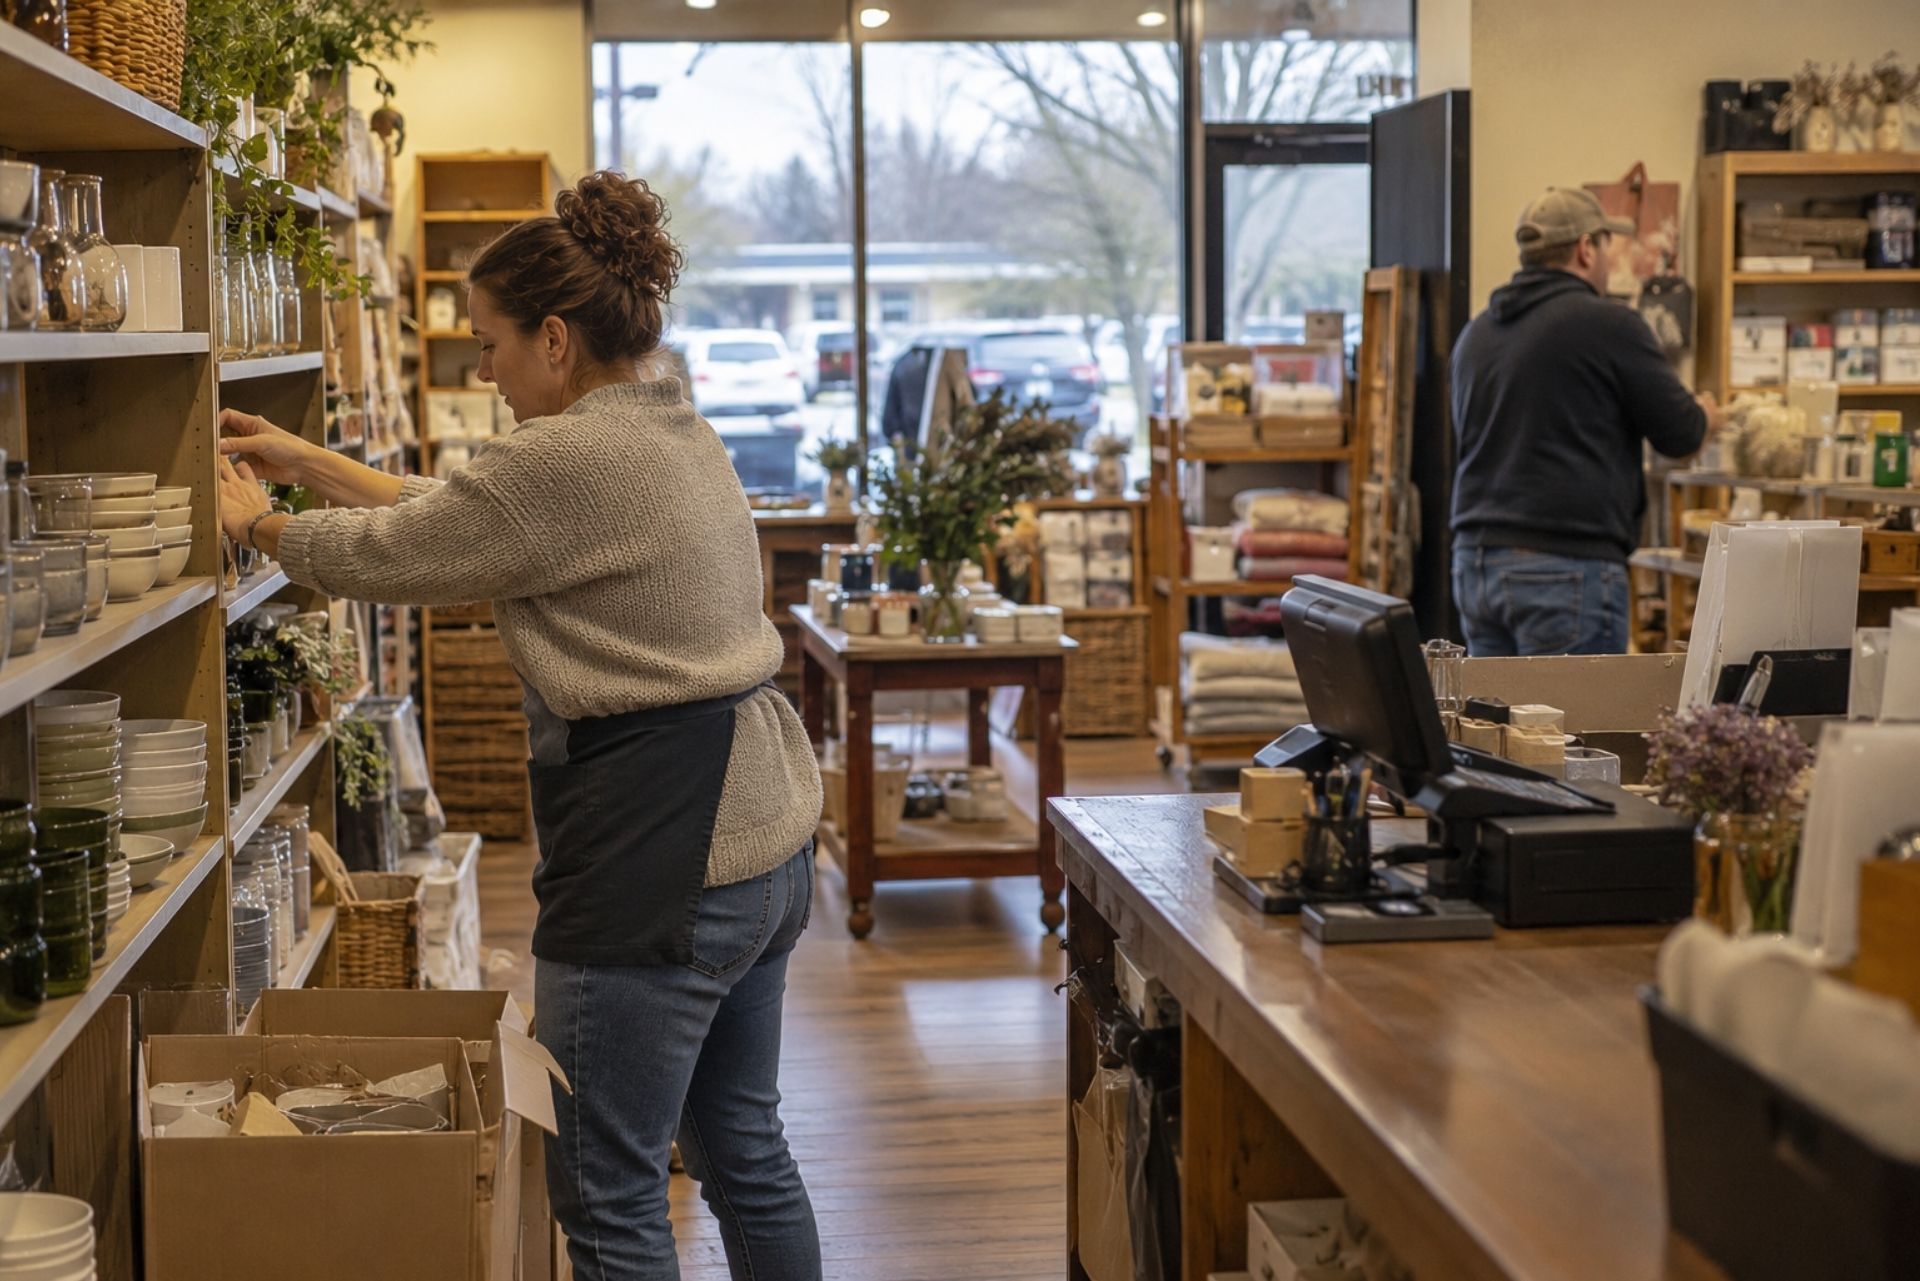
Retailers on Perry Highway need strong general liability for customer injuries, solid property coverage for inventory and storefronts, and business income protection for disruptions. The Route 19 corridor's traffic volume brings steady customers, but it also brings more chances for something to go wrong.
Foot traffic is the obvious exposure. A customer slips on melted snow tracked inside during a February rush, breaks a wrist, and files a claim for medical bills and lost wages. These premises liability claims make up a large share of retail losses, and they're why carriers ask about mats, signage, and cleaning schedules. Keeping a written snow and ice log for your entrance and parking area is one of the simplest ways to strengthen your defense.
Vehicle exposure is less obvious but real. Storefronts close to busy roads and parking lots occasionally take a hit from a car. Property coverage should include the glass, signage, and building improvements you're responsible for under your lease. Outdoor signs often have low sublimits unless you specifically schedule them, and a lighted pylon sign can cost thousands to replace.
Inventory deserves attention, too. Shops serving the growing residential populations of Marshall and Pine townships often see seasonal swings, carrying double their normal stock before the holidays or back-to-school season. A peak season endorsement temporarily raises your contents limit so a November fire doesn't leave you underinsured.
Other coverages worth discussing for Route 19 retailers:
- Crime and employee dishonesty for cash handling and inventory shrinkage
- Product liability if you sell private-label goods or import directly
- Spoilage for shops with refrigerated stock
- Hired and non-owned auto if employees run errands or make deliveries in personal cars
Understanding Business Owners Policies (BOP)
A Business Owners Policy bundles general liability and commercial property insurance into one package, usually with business income coverage included. For many Wexford small businesses, it's the most efficient way to buy foundational protection, often at a lower combined price than purchasing each piece separately.
Carriers design BOPs for small to midsize businesses with lower-risk operations: offices, small retailers, some restaurants, and service firms. If you have a large payroll, heavy manufacturing, or hazardous operations, you may not qualify and will need a standalone commercial package instead.
Pricing floors have moved this year. Penn National, a major regional carrier, raised its BOP minimum premium to $625 for one-year policies in 2026. That doesn't mean every BOP costs that much, since minimums vary by carrier, but it shows why comparing several markets matters. A very small office could pay noticeably different amounts depending on which carrier's minimums and rating rules apply.
The bigger risk is assuming a BOP covers everything. It doesn't include professional liability, workers' compensation, commercial auto, or, in most cases, meaningful cyber protection. Some carriers offer small cyber endorsements on a BOP, but the limits are often modest. Treat the BOP as your foundation and build on top of it.
Health benefits sit outside a BOP entirely, though many owners review them at the same time. Pennsylvania small group plans saw a requested average increase of 13% for 2026, driven by drug costs and expiring tax credits. Lawmakers also announced plans in May 2026 for a state tax credit for businesses with 50 or fewer employees that use ICHRA arrangements, though that proposal is legislation, not law, and its outcome should be checked before you plan around it.
Comparing Common Insurance Limits and Options
Here's a plain-language look at the coverages most North Hills firms consider. Limits shown are common starting points, not recommendations for every business.
| Coverage | What It Covers | Common Limits | Who Usually Needs It |
|---|---|---|---|
| BOP (liability + property) | Customer injuries, property damage, building contents | $1M per occurrence / $2M aggregate | Most offices and shops |
| Professional liability / E&O | Mistakes in advice or services | $1M / $1M to $2M / $3M | Consultants, CPAs, medical providers |
| Cyber liability | Data breaches, ransomware, notification costs | $250K to $1M | Anyone storing client data |
| Workers' compensation | Employee injuries on the job | Statutory in PA | Businesses with employees |
| Commercial umbrella | Extra liability above other policies | $1M to $5M | Higher-traffic retail, larger offices |
| Commercial auto | Business-owned vehicles | $500K to $1M combined | Delivery, contractors, mobile services |
Pennsylvania generally requires workers' compensation for businesses with employees, with limited exceptions. Lease agreements and client contracts frequently dictate liability limits, so pull those documents before shopping.
Cyber Coverage for Modern Business Operations
Cyber coverage pays for the costs that follow a data breach, ransomware attack, or funds transfer fraud: forensic investigation, customer notification, credit monitoring, legal defense, regulatory fines where insurable, and lost income during downtime. For Wexford professional offices handling patient or client records, it's become essential rather than optional.
Small firms often believe hackers target only big companies. In practice, small offices are attractive precisely because their defenses are thinner. A common scenario: an employee at a bookkeeping firm clicks a convincing invoice email, ransomware encrypts the server, and the firm can't access client files during tax season. The ransom demand is only part of the cost. Restoring systems, notifying clients, and handling lost billable hours often costs more.
Social engineering fraud is the other big one. A criminal impersonates a vendor or the practice owner and asks the office manager to wire payment to a "new" account. Many cyber policies exclude this or cap it at a small sublimit unless you add specific coverage. If your office ever sends wires or ACH payments, ask directly how your policy handles it.
Carriers now expect basic security controls before they'll quote. Expect questions about:
- Multi-factor authentication on email and remote access
- Offline or immutable backups tested regularly
- Endpoint protection on every device
- Employee phishing training
- Patching schedules for software and servers
Medical practices carry added weight because of HIPAA. A breach involving patient records triggers notification obligations and potential federal scrutiny. A solid cyber policy includes breach coach services, attorneys who walk you through those requirements step by step, which is often worth the premium on its own. If you currently rely on a cyber endorsement tucked inside your BOP, compare its limits against a standalone policy before renewal.
Frequently Asked Questions About Wexford Business Insurance
Wexford business owners usually ask the same handful of questions when they start shopping. Here are plain answers.
Is Wexford a town or a township for insurance purposes? Wexford is a mailing address, not a municipality. It covers parts of Pine, Richland, Franklin Park, and Marshall townships, and carriers rate your policy on the exact property location.
Does my school district affect my business insurance? Not directly. Whether you're in the North Allegheny or Pine-Richland school district matters for property taxes, but insurance pricing depends on the property address, fire protection, building construction, and your type of business.
Do I need business insurance if I work from home in Wexford? Usually yes. Homeowners policies typically exclude business property and liability, so a client injury or stolen work laptop may not be covered without a home business endorsement or separate policy.
Is workers' comp required in Pennsylvania for small businesses? In most cases, yes. Pennsylvania generally requires workers' compensation once you have employees, even part-time ones, with only narrow exceptions.
What's the difference between general liability and professional liability? General liability covers physical injuries and property damage, like a customer falling in your office. Professional liability covers financial harm caused by your advice or services, like an accounting error.
Can I bundle cyber coverage with a Business Owners Policy? Some carriers offer a cyber endorsement on a BOP, but limits are often small. Offices that store sensitive data usually benefit from a standalone cyber policy.
Contact MVP Insurance for Local Expertise
The right North Hills business insurance program is rarely one policy. It's a BOP as the foundation, professional liability for the advice you give, cyber protection for the data you hold, and workers' comp and auto where your operations call for them. The firms that get burned are usually the ones that bought a package years ago and never revisited it as they hired staff, added equipment, or moved suites.
MVP Insurance has helped Pennsylvania and Ohio business owners sort through those decisions since its founding in 2008 by Josh Medure and David Varrati. You can reach the Zelienople office at 108 E Grandview Ave, Zelienople, PA 16063, at (724) 453-1122, or the New Springfield office at 13823 Grant St, New Springfield, OH 44443, at (330) 707-9055. Because MVP is independent, the team compares policies from multiple carriers and offers 24/7 claims support when something goes wrong.
If your Wexford policy hasn't been reviewed against your current lease, contracts, and headcount, now is a good time. Bring your declarations pages and ask the team to look for gaps first, price second. When you're ready, start your quote and let MVP do the comparison work for you.
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

About the Author
Joshua Medure
Owner, MVP Insurance
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.