


Owner, MVP Insurance
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
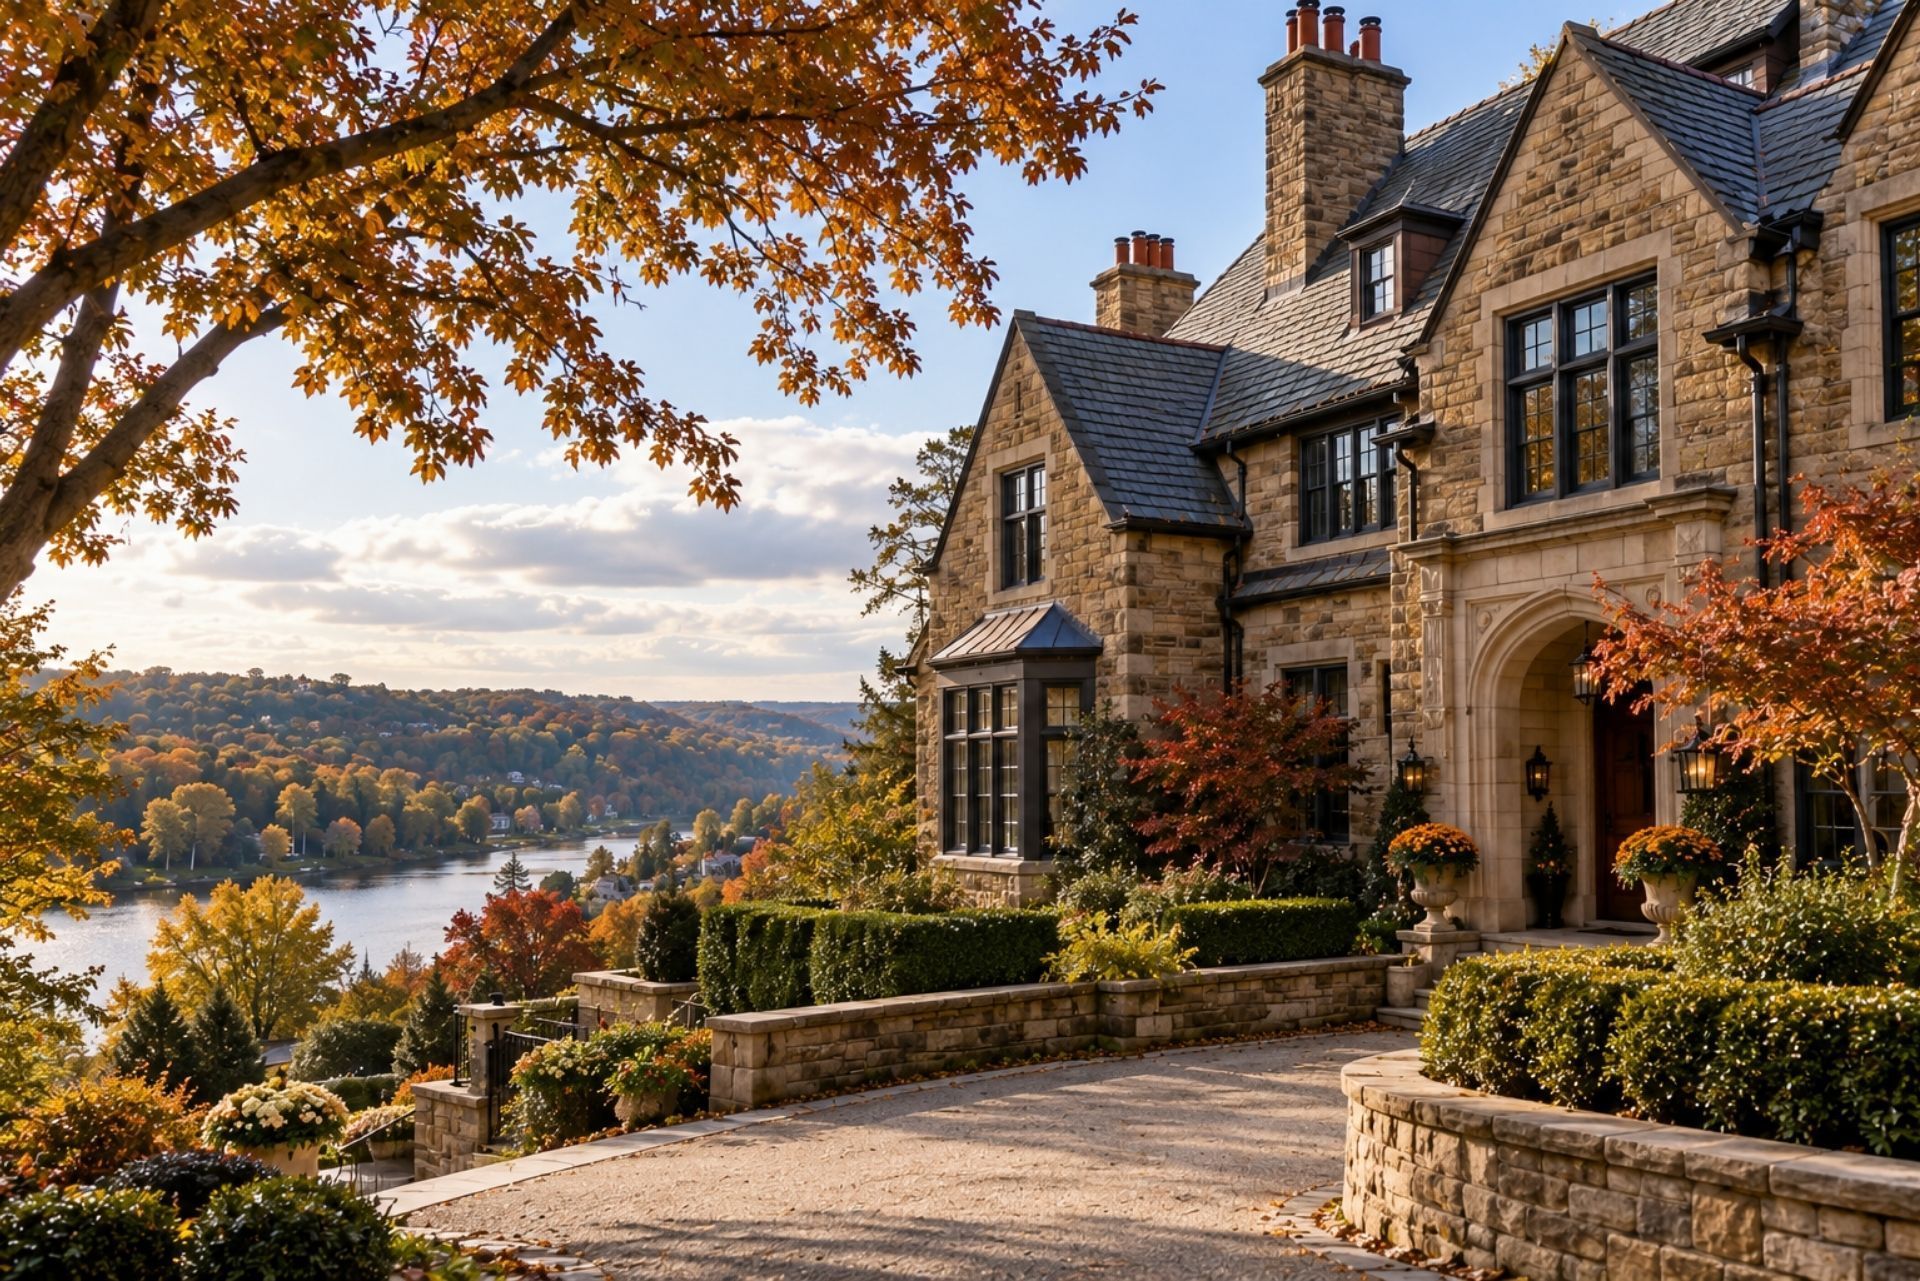
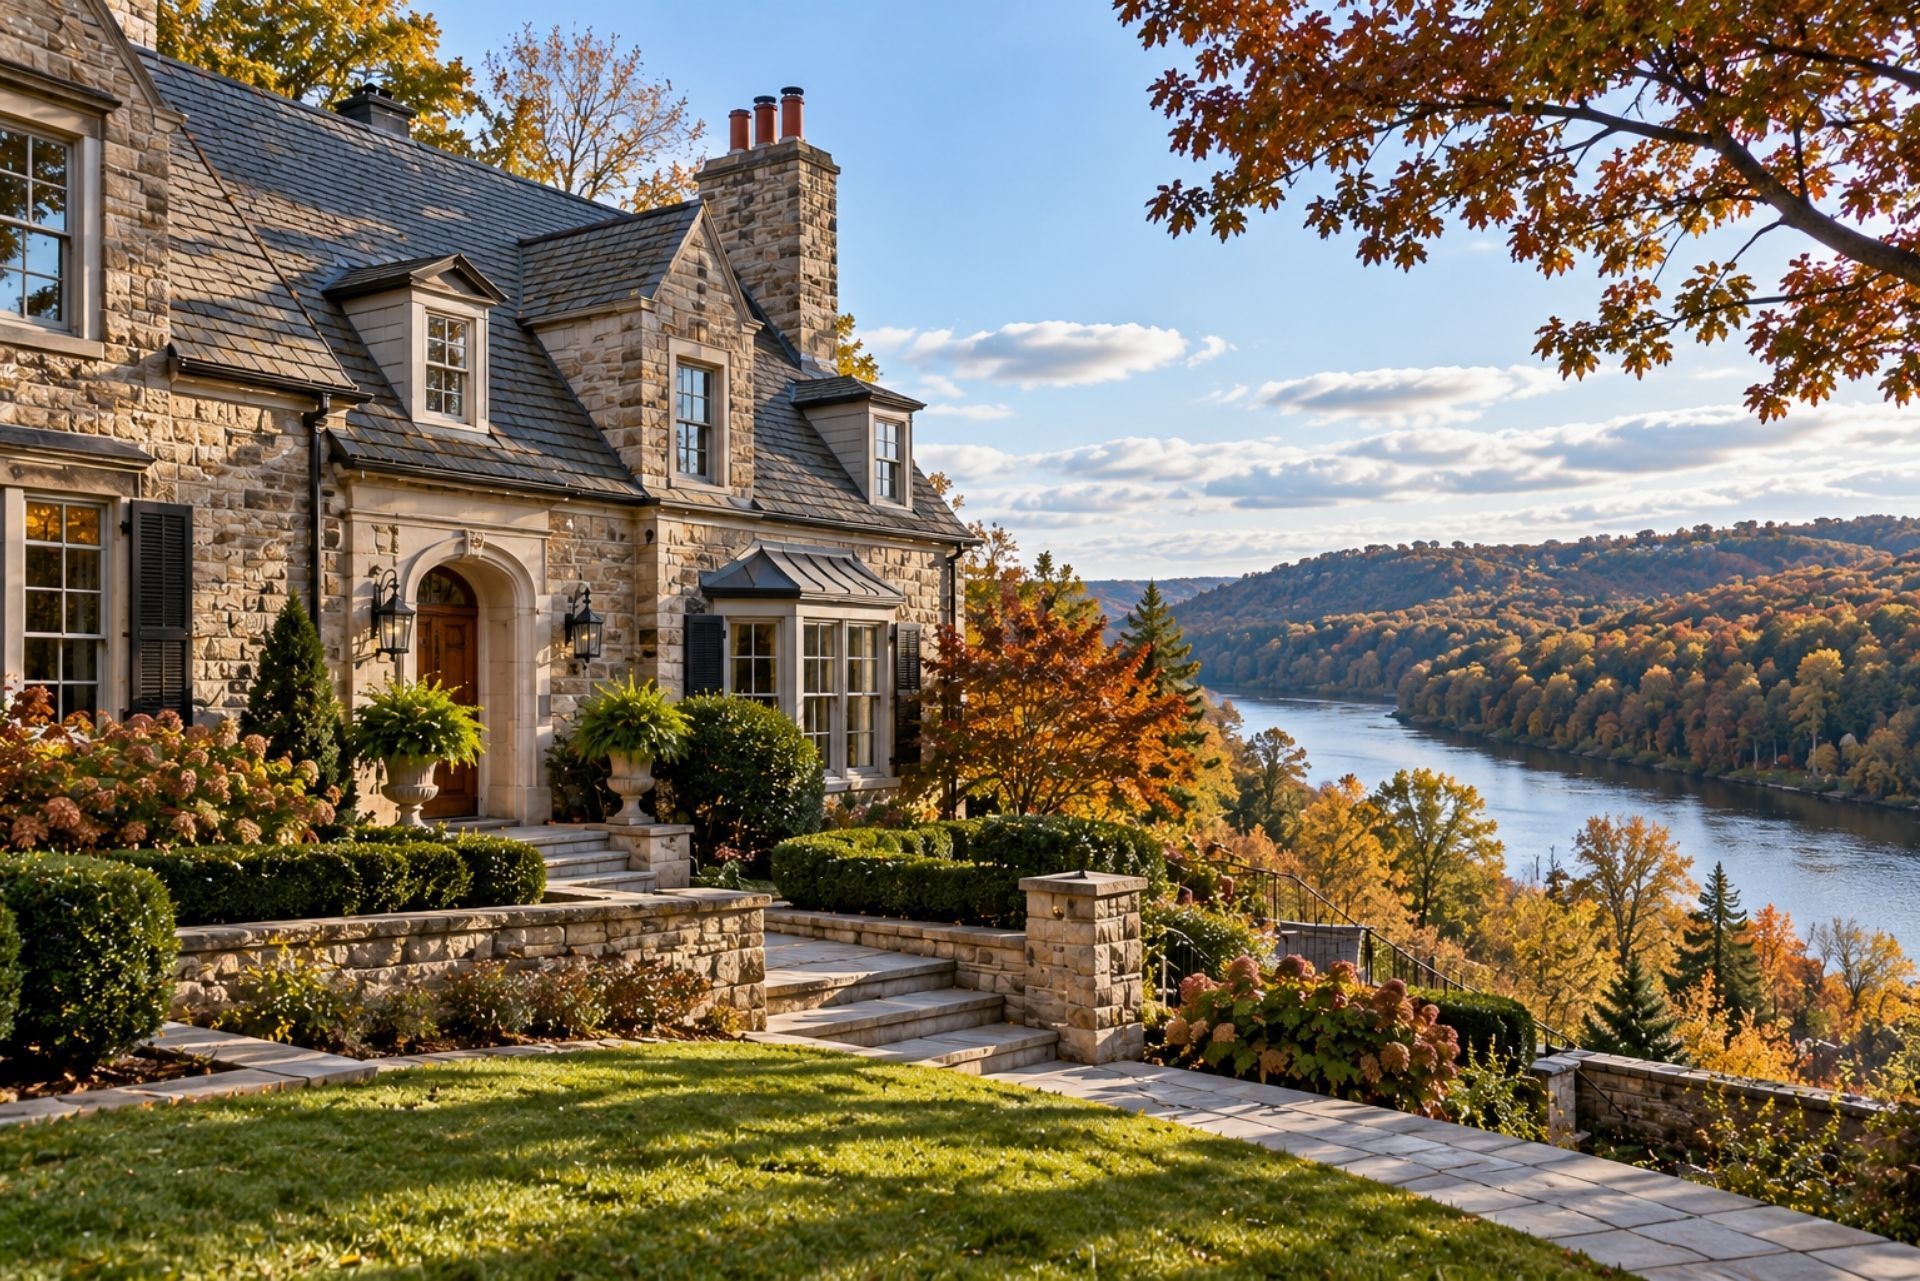
Sewickley homes rarely fit a standard homeowners policy. Between 1800s village houses with slate roofs and hand-carved trim, and Sewickley Heights estates spread across wooded acreage, most properties need high value home insurance built on accurate rebuild costs, earth movement planning, and separate protection for art and jewelry.
That is the short answer. The longer one depends on where your house sits, what it is made of, and what hangs on the walls inside. A Beaver Street Victorian and a gated estate off Blackburn Road share a zip code, but almost nothing else about how they should be insured. Owners often discover the gaps only after a claim. Those gaps include an underinsured slate roof, a hillside slip that no policy touches, or a necklace that went missing and was never scheduled.
Protecting Sewickley PA High Value Home Insurance Assets
Sewickley's market is unusual because value comes from craftsmanship and land, not square footage. A policy priced on a generic per-foot formula will almost always undershoot what it takes to rebuild a home here. Specialized private client carriers solve that with appraisal-based limits, broader replacement guarantees, and claims teams used to restoration work.
MVP Insurance was founded in 2008 by Josh Medure and David Varrati, with offices in Zelienople, PA and New Springfield, OH. As an independent agency, MVP compares multiple carriers rather than selling one company's product, which matters when only a handful of insurers write true high value homes well. You can read more about how the agency handles private client insuranceand the specifics of high value home insurance in Pennsylvania.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Nationally, manufactured home insurance typically runs $800 to $1,200 per year in 2026, though your price depends on the home's age, location, claims history, and deductible. A newer home in a low-risk area with a higher deductible can come in well under that range.
Policy filings in the state are also changing. In April 2026, the Pennsylvania Insurance Department issued Notice 2026-07 to modernize filing requirements while keeping strict oversight of personal risk insurance. For consumers, that means carriers still have to justify their manufactured home forms and rates to regulators.
MVP Insurance, founded in 2008 by Josh Medure and David Varrati, is an independent agency that works with carriers including Erie, Progressive, Foremost, and American Modern. Because we compare several companies side by side, we can match a newer home with a carrier that rewards its condition and place an older or unusual home with a carrier that specializes in it.
| Coverage | What It Covers | Typical Range or Option |
|---|---|---|
| Dwelling | The home itself | Based on replacement or market value |
| Other structures | Sheds, carports, decks | Often 10% of dwelling, adjustable |
| Personal property | Belongings inside | Often 50% to 70% of dwelling |
| Loss of use | Temporary housing costs | Percentage of dwelling or set limit |
| Personal liability | Injury or damage you cause others | Commonly $100,000 to $300,000 |
| Medical payments | Guest injuries, no-fault | Commonly $1,000 to $5,000 |
| Valuation | How claims are paid | Replacement cost or actual cash value |
Insuring Sewickley Village Historic Homes and Sewickley Heights Estates
Village homes and Heights estates both need specialized valuation, but for different reasons. In the Village, the risk is dense historic construction. In the Heights, it is scale, distance, and outbuildings.
Sewickley Village packs Victorian, Queen Anne, and Colonial Revival houses onto tight lots near Broad Street. Fire can spread between closely spaced structures, and local historic review may dictate what a rebuild has to look like. Insuring historic properties requires specialized knowledge of local preservation mandates, and a policy without strong ordinance or law coverage can leave you paying the difference out of pocket.
Sewickley Heights works differently. Estates sit on many acres with long private drives, carriage houses, pool houses, barns, and stone walls. Each of those structures needs its own adequate limit, not a flat percentage of the main dwelling. Fire department response times and hydrant distance also affect pricing. Owners there often benefit from monitored alarms and backup generators, which some carriers reward with credits.

Written By
David Varrati
Owner, MVP Insurance
On this page
Multiple carriers
We quote your home, auto and other policies across the carriers we represent, look at how they pair for discounts, and show you the differences in coverage, not just the price.
Managing Ohio River Hillside Exposure and Land Stability
The views over the Ohio River come with a real exposure: earth movement. Standard homeowners policies, including many high value forms, generally exclude landslide, subsidence, and soil shifting. That surprises a lot of hillside owners.
Western Pennsylvania's steep, clay-heavy slopes slide after heavy rain, and the problem has reached Harrisburg. House Bill 589, the Protecting Pennsylvanians from Landslides Act, passed the House in late 2025 and is under Senate consideration as of this writing. The bill would create a state-run Landslide and Sinkhole Insurance Program to fill the gap private policies leave.
Until something like that exists, hillside owners should focus on what they can control:
- Drainage and retaining walls: maintain them, and document repairs with dates and photos.
- Water backup coverage: add it, since heavy rain often overwhelms drains on sloped lots.
- Flood review: properties near the river or Little Sewickley Creek may need separate flood coverage through a provider like Franklin Flood or American Bankers.
- Collapse wording: read how your policy treats sudden collapse versus gradual movement.
Reconstruction Costs for Slate Roofs and Original Millwork
Slate roofs and original millwork push rebuild costs far above standard construction, so your dwelling limit needs guaranteed or extended replacement cost behind it. Without that feature, a total loss can leave a six-figure shortfall.
The numbers are steep. Replicating 19th-century craftsmanship can cost 3 to 5 times more than modern construction. Authentic restoration of period-matching millwork and plaster is estimated at $310 per square foot or higher, compared to roughly $180 per square foot for commodity materials. On a 5,000 square foot house, that difference alone exceeds $650,000.
Slate adds its own complications. Matching salvaged or quarry-specific slate takes time, and few roofers in the region still do traditional installation. A common claim mistake is accepting asphalt shingles on a partial loss because the policy only pays "like kind and quality" at a modern standard. Private client forms typically pay to restore with original materials and methods. Some go further and will replace undamaged sections so the roof matches.
Comprehensive Collections Coverage for Fine Art and Jewelry
Valuables need their own scheduled coverage with agreed value. A standard homeowners policy caps jewelry theft at a small sublimit and treats art like any other contents.
Scheduled valuable articles coverage provides all-risk protection, including mysterious disappearance. If a ring simply vanishes, a standard policy generally won't pay, but a scheduled item typically will. Agreed value means you and the carrier set the payout up front, based on an appraisal, so there's no depreciation fight after a loss.
Features worth asking about for a serious collection:
- Blanket coverage for unscheduled pieces below a per-item threshold
- Newly acquired property coverage for 60 to 90 days after a purchase, typically
- Pair and set clauses that pay full value when one earring of a pair is lost
- Breakage coverage for ceramics, glass, and sculpture
- Worldwide coverage for pieces that travel or go out on loan
Update appraisals every three to five years. Art and gold markets move, and an outdated schedule quietly underinsures you.
Comparing Standard vs. Private Client Insurance Features
Private client policies fill gaps a standard form leaves open, especially for older, larger homes. Here is how the two typically compare:
| Feature | Standard Policy | Private Client Policy |
|---|---|---|
| Dwelling payout | Replacement cost up to limit | Guaranteed or extended replacement |
| Cash-out option | Usually must rebuild | Cash settlement without rebuilding, typically |
| Deductible waiver | Rare | Often waived on large losses |
| Jewelry theft | Low sublimit | Scheduled, agreed value |
| Mysterious disappearance | Excluded | Covered on scheduled items |
| Historic materials | Modern equivalents | Original materials and methods |
| Ordinance or law | Limited percentage | Higher limits |
| Valuation | Formula estimate | On-site appraisal |
The cash-out option matters more than people expect. After a total loss, some Heights owners decide not to rebuild on the same lot. A private client policy generally lets you take the settlement and move on.
Frequently Asked Questions About Sewickley Home Insurance
Do I need high value home insurance in Sewickley? If your rebuild cost is roughly $750,000 or more, or your home has historic materials, a private client policy is usually the better fit. Smaller or newer homes often do well with standard carriers.
Which carriers handle standard homes in Sewickley? For typical homes, carriers like Erie, Westfield, and Frederick Mutual are common choices. MVP compares these alongside other options.
Does homeowners insurance cover landslides in Pennsylvania? Generally no. Earth movement is excluded on most policies, which is why HB 589 is being considered.
Is my jewelry covered if I lose it? Only if it's scheduled with all-risk coverage. Standard policies typically exclude items that are simply lost.
How often should I update my home's value? Every few years, or after any renovation. Construction costs for historic trades rise faster than general inflation.
Do I need flood insurance near the Ohio River? Possibly. Standard and high value homeowners policies exclude flood, so riverside and low-lying properties should consider a separate policy.
Request a Private Client Review for Your Sewickley Property
A Sewickley home deserves a policy that understands slate, plaster, hillside soil, and the collection inside. Getting appraisal-based limits, guaranteed replacement, and properly scheduled valuables now is far easier than arguing over a shortfall after a fire or a slide.
MVP Insurance shops multiple carriers on your behalf and reviews your current coverage line by line. Request a Private Client Reviewto see where your protection stands. You can also call the Zelienople office at (724) 453-1122 or New Springfield at (330) 707-9055. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













