


Cincinnati OH Car Insurance

Owner, MVP Insurance

Cincinnati drivers need more than Ohio's legal minimum. Hamilton County's I-71/I-75 interchange traffic, steep hillside streets that ice over, and ongoing theft risk all call for higher liability limits, comprehensive and collision coverage, and uninsured motorist protection. A sensible starting point for most households is 100/300/100, adjusted to what you own and need to protect.


That answer covers the basics, but the details matter. A driver in Clifton who parks on the street faces different risks than a commuter crossing the Brent Spence Bridge every morning from Covington. This guide walks through the local hazards that drive claims in the Cincinnati area and how each one should shape your policy. It also covers when the state minimum stops being enough.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

The Risk of I-75 and I-71 Interchange Traffic

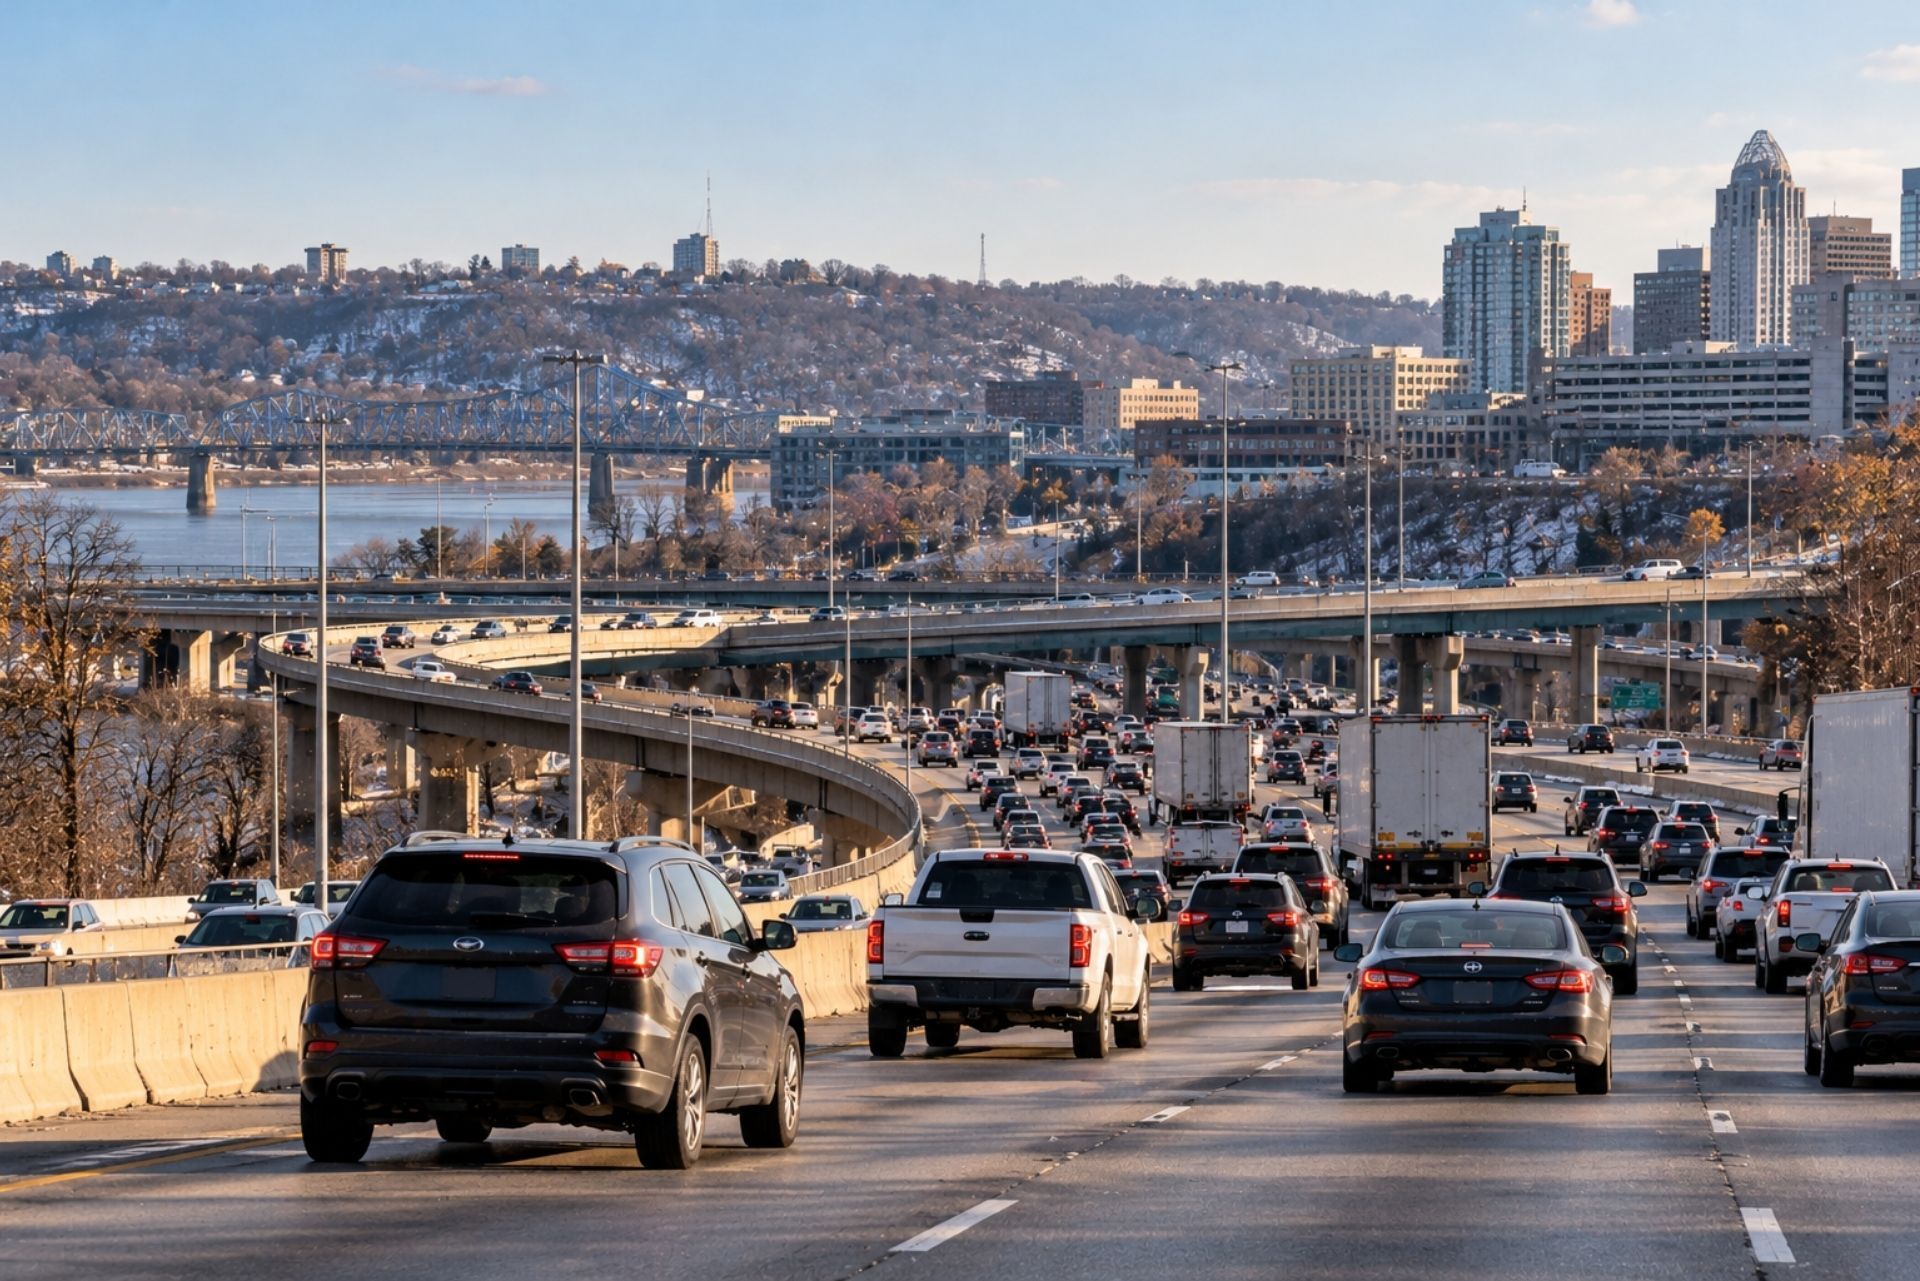
The I-71/I-75 convergence near the Brent Spence Bridge is one of the most claim-prone stretches in the region. The reasons are tight merges, sudden stops and heavy truck volume. The interchange is ranked the #9 truck bottleneck in the United States in the 2026 ATRI report. A rear-end collision with a loaded tractor-trailer involved can quickly turn into a six-figure liability claim.


Congestion makes things worse. Cincinnati drivers lose an average of 33 to 46 hours a year to traffic, and peak morning speeds downtown average around 18 mph. Stop-and-go traffic produces the classic chain-reaction claim. One distracted driver taps the car ahead, and that car pushes into the next.


Construction adds another layer in 2026. The $4.4 billion Brent Spence Bridge Corridor project is in an active demolition phase that includes removing the 1960s addition to Longworth Hall and the Second Street ramp. On October 16, 2026, I-75 South closed at the Freeman Avenue exit so crews could install girders for the new Linn Street overpass. Work on the Second Street ramp is expected to continue into spring 2027. Shifted lanes, surprise detours and drivers unfamiliar with new patterns all raise the odds of a crash where fault gets disputed.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Managing Hillside Winter Ice and Road Hazards

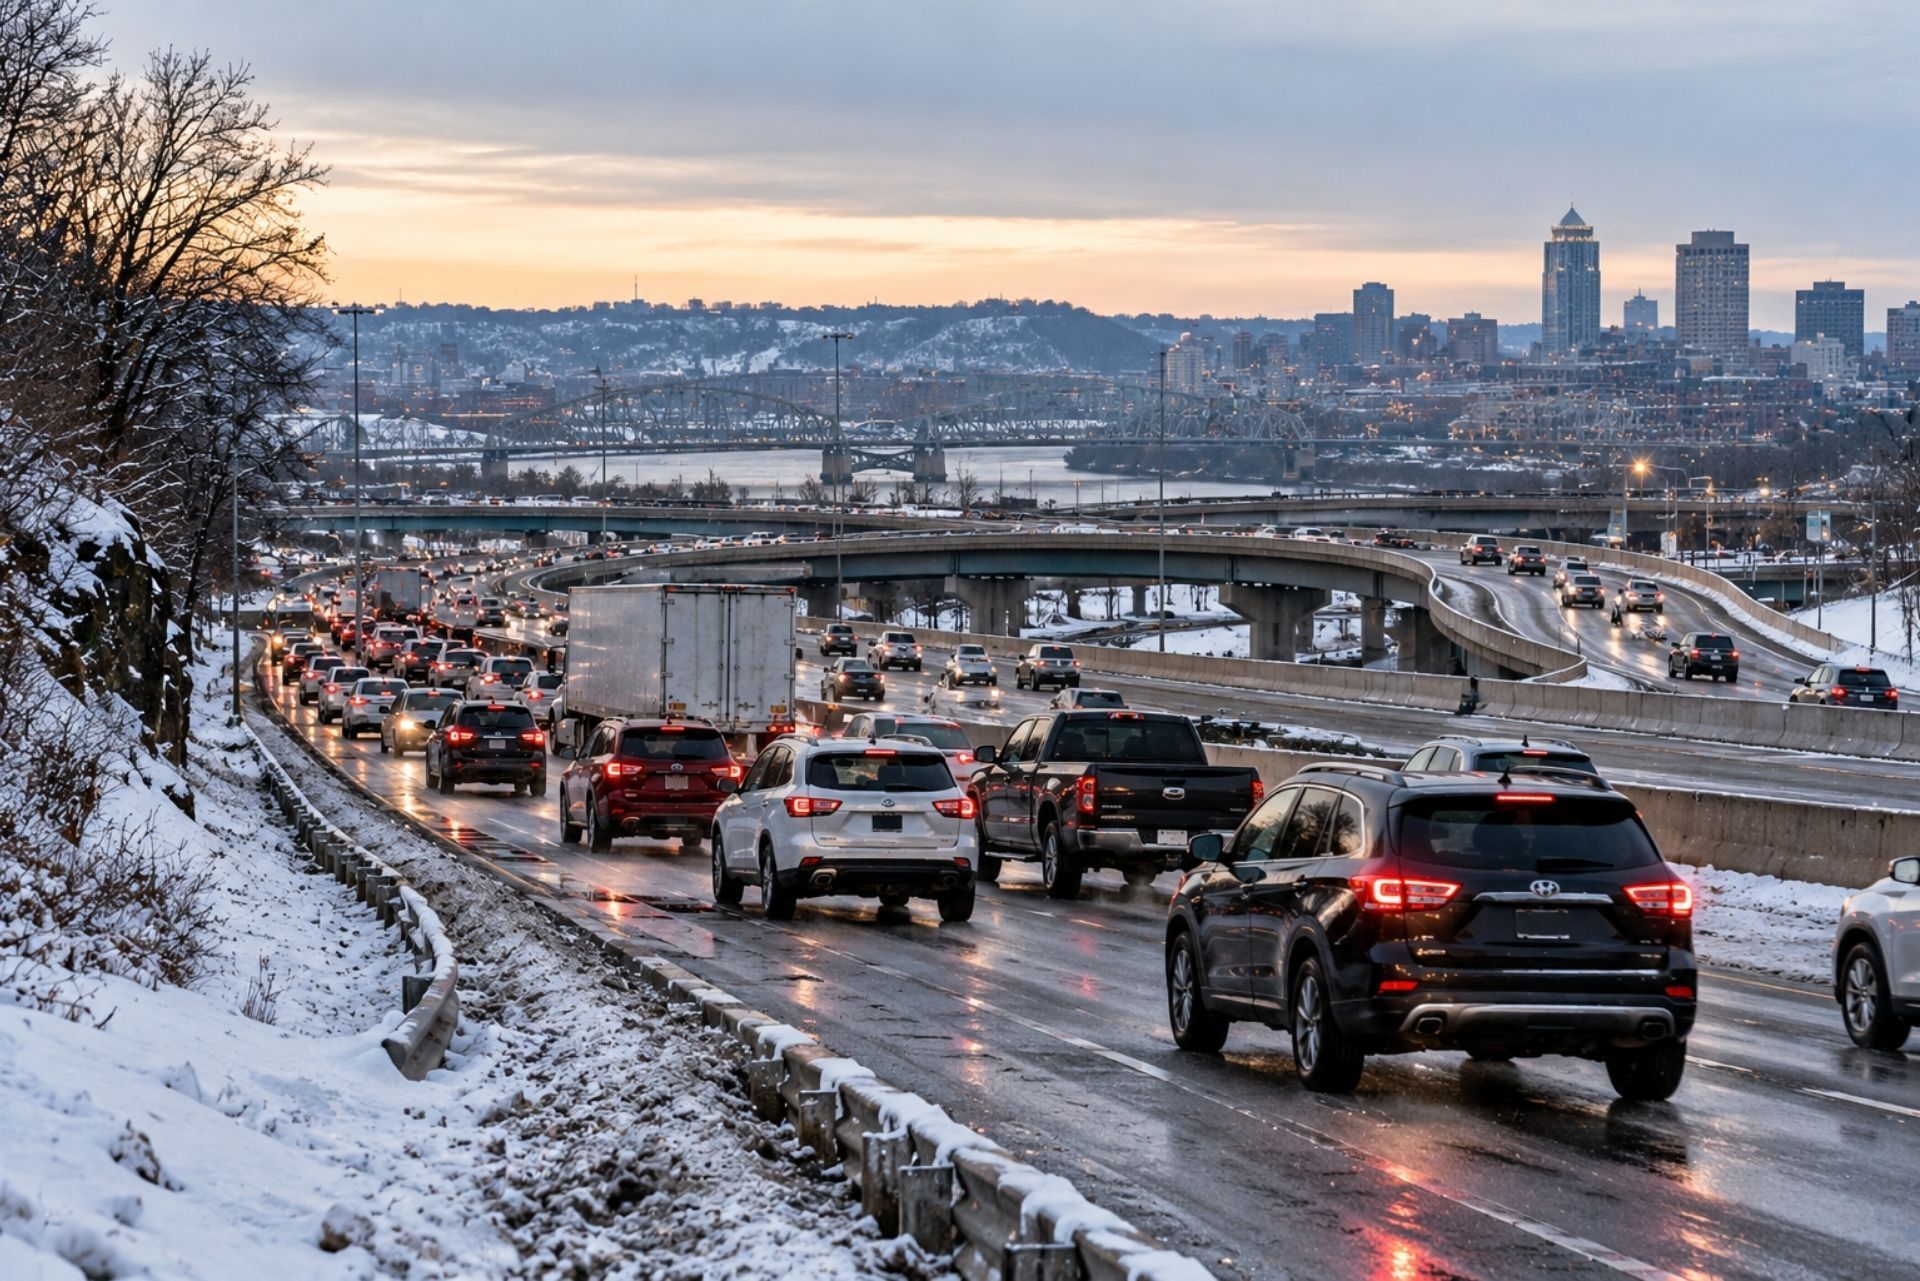
On Cincinnati's steep streets, collision coverage pays to repair your car after an ice slide, and comprehensive covers things like falling limbs. Neighborhoods such as Mount Adams, Price Hill and Clifton have grades that turn treacherous after freezing rain. Even careful drivers lose traction going downhill.


The city works hard on this. The Department of Public Services manages 3,112 lane miles, and its 2026-2027 Snow and Ice Control Plan prioritizes steep hills and bridges. Still, plows can't be everywhere at once. Side streets and driveways often stay slick for hours after a storm.


Typical hillside winter claims look like this:


  • Sliding into a parked car: Your liability covers their car. Your collision covers yours.
  • Hitting a pole, wall or guardrail: This is a single-vehicle collision claim. No other driver means no one else's insurer pays.
  • A parked car rolling or getting hit: Collision or the other driver's liability may apply, depending on fault.
  • Ice-laden branches falling on the roof: This is usually a comprehensive claim.


One coverage gap shows up often in winter. People drop collision on an older car to save money, then slide into a retaining wall. If your car would be a real hardship to replace out of pocket, keep collision and consider raising the deductible instead.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Addressing Recent Theft Claims in Hamilton County

Comprehensive coverage is what pays when your car is stolen, stripped or vandalized. Liability alone covers nothing in these situations. Vehicle and parts theft remain an ongoing concern across the metro area, from catalytic converters cut off in apartment lots to targeted thefts of models with weak factory anti-theft systems.


The details of your policy matter here. Comprehensive pays the actual cash value of a stolen car, not what you still owe on it. If you financed recently, gap coverage can cover the difference between the payout and your loan balance. Rental reimbursement is worth a few dollars a month, because theft claims can take weeks to settle while the insurer waits to see if the car turns up.


A few practical steps help both your claim and your premium. Photograph your car and any aftermarket equipment, keep receipts for upgrades, and ask whether your policy covers custom parts, since many cap that coverage at a low amount. Report a theft to police right away, because the insurer will ask for the report number. Off-street or garage parking can also lower your comprehensive rate with some carriers.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Home

A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.

Choosing Liability Limits Above Ohio Minimums

Most Cincinnati drivers should carry at least 100/300/100 in liability coverage. Ohio's 25/50/25 minimum can be exhausted by a single injury. A multi-car pileup on I-71 can generate medical bills, lost wages and vehicle damage for several people at once, and anything your policy doesn't pay can become your personal debt.

Comparing State Minimums vs Recommended Limits

The numbers make the case quickly. The average represented Ohio injury claim settles for roughly $48,000, nearly double the $25,000 per-person minimum. Local recommendations call for at least 100/300/100 because of commercial truck traffic on the I-75 corridor.

Coverage Ohio Minimum Suggested for Cincinnati
Bodily injury per person $25,000 $100,000+
Bodily injury per accident $50,000 $300,000+
Property damage $25,000 $100,000+
Uninsured motorist Optional Match your liability
Comprehensive/collision Optional Yes, unless car is low value

Uninsured motorist coverage is especially important in Ohio. An estimated 17.1% to 18.5% of Ohio drivers are uninsured, which puts the state among the top 10 nationally. If one of them hits you on Fort Washington Way, your own UM coverage pays your medical bills. The cost difference between minimum and higher limits is usually smaller than people expect, often a modest monthly increase rather than a doubling.

Protecting Assets with Umbrella and Homeowners Policies

Once you own a home or have meaningful savings, auto coverage alone isn't the full picture. An umbrella policy adds a layer, often $1 million, that kicks in after your auto or home liability runs out. Most umbrella carriers require you to carry certain underlying auto limits first, which is another reason to move above the minimum.


Pairing your Ohio car insurancewith homeowners coverage in Ohiobuilds a stronger safety net and often unlocks multi-policy savings. It also means one agent can see your whole picture and spot gaps between policies. A common example is a teen driver added to the auto policy without anyone checking whether the umbrella still covers them.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Common Cincinnati Auto Insurance Questions

How much is car insurance in Cincinnati? Full coverage in Cincinnati averaged roughly $82 to $137 a month as of September 2026 (verify at publish). Your rate depends on your ZIP code, driving record, vehicle and the limits you choose.


Are Ohio car insurance rates going down? The Ohio Department of Insurance reported that the auto market began stabilizing in late 2026, and some carriers announced rate cuts. That makes now a good time to compare quotes.


Who pays if I slide into a car on an icy hill? Ice doesn't remove fault, so your liability coverage usually pays for the other car. Your collision coverage pays for your own repairs, minus your deductible.


What insurance does Hamilton County require? Hamilton County follows Ohio's statewide minimum liability requirement of 25/50/25. Lenders also require comprehensive and collision coverage on financed or leased cars.


Does car insurance cover a stolen catalytic converter? Yes, if you carry comprehensive coverage. Liability-only policies won't pay for theft.


Is uninsured motorist coverage worth it in Ohio? For most drivers, yes. With roughly one in six Ohio drivers uninsured, it protects you when the at-fault driver can't pay.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Coverage What It Protects Common Gap to Watch
Homeowners Dwelling, belongings, liability High wind/hail deductibles
Renters Belongings, liability, living costs Low liability limits
Auto Vehicle damage, injury liability State minimum limits only
Motorcycle Bike, gear, liability Custom parts excluded
Boat Hull, motor, liability on water Trailer or navigation limits
Umbrella Excess liability above other policies Underlying limits too low
Life Income replacement for family Only employer coverage

Contact MVP Insurance for a Local Review

Cincinnati's risks are specific: truck-heavy merges at the I-71/I-75 interchange, construction detours around the Brent Spence Bridge, icy hillside streets and steady theft activity. Coverage built only to satisfy the state minimum leaves gaps in every one of those scenarios. Higher liability limits, uninsured motorist protection and comprehensive coverage are where real protection starts.


MVP Insurance is an independent agency, so the team shops multiple carriers on your behalf and offers 24/7 claims support when something goes wrong. For a personalized consultation with Josh Medure or David Varrati, call the Zelienople, PA office at (724) 453-1122 or the New Springfield, OH office at (330) 707-9055. If you'd rather start online, you can request your quote here and get a side-by-side comparison of your options.


MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. A short review now costs far less than learning your limits were too low after a crash on I-75.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








