


Owner, MVP Insurance
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
Older houses, a creek that rises fast, and oak trees that predate the Civil War make insuring a home in Poland different from insuring a newer build in a subdivision. If you own one of these properties, the details in your policy matter more than the premium on the front page.
Protecting Assets with Poland OH Homeowners Insurance
Poland OH homeowners insurance often needs more than a standard policy. Historic homes need endorsements for replacement cost and ordinance or law coverage. Homes near Yellow Creek need a separate flood policy, because standard coverage excludes rising water. Mature trees on the lot also call for careful attention to windstorm and debris removal limits.
MVP Insurance is an independent agency founded in 2008 by Josh Medure and David Varrati. We work from offices in Zelienople, PA and New Springfield, OH. New Springfield sits right next door to Poland, so the village's mix of century homes, creek-side lots and heavy tree cover is familiar ground for us. We shop multiple carriers and compare policies so you don't have to call five companies yourself.
If you're comparing statewide options first, our page on homeowners insurance in Ohiocovers the basics. Many Poland households also bundle with car insurance in Poland,which can simplify billing and claims.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Insuring Historic Homes in Poland Village
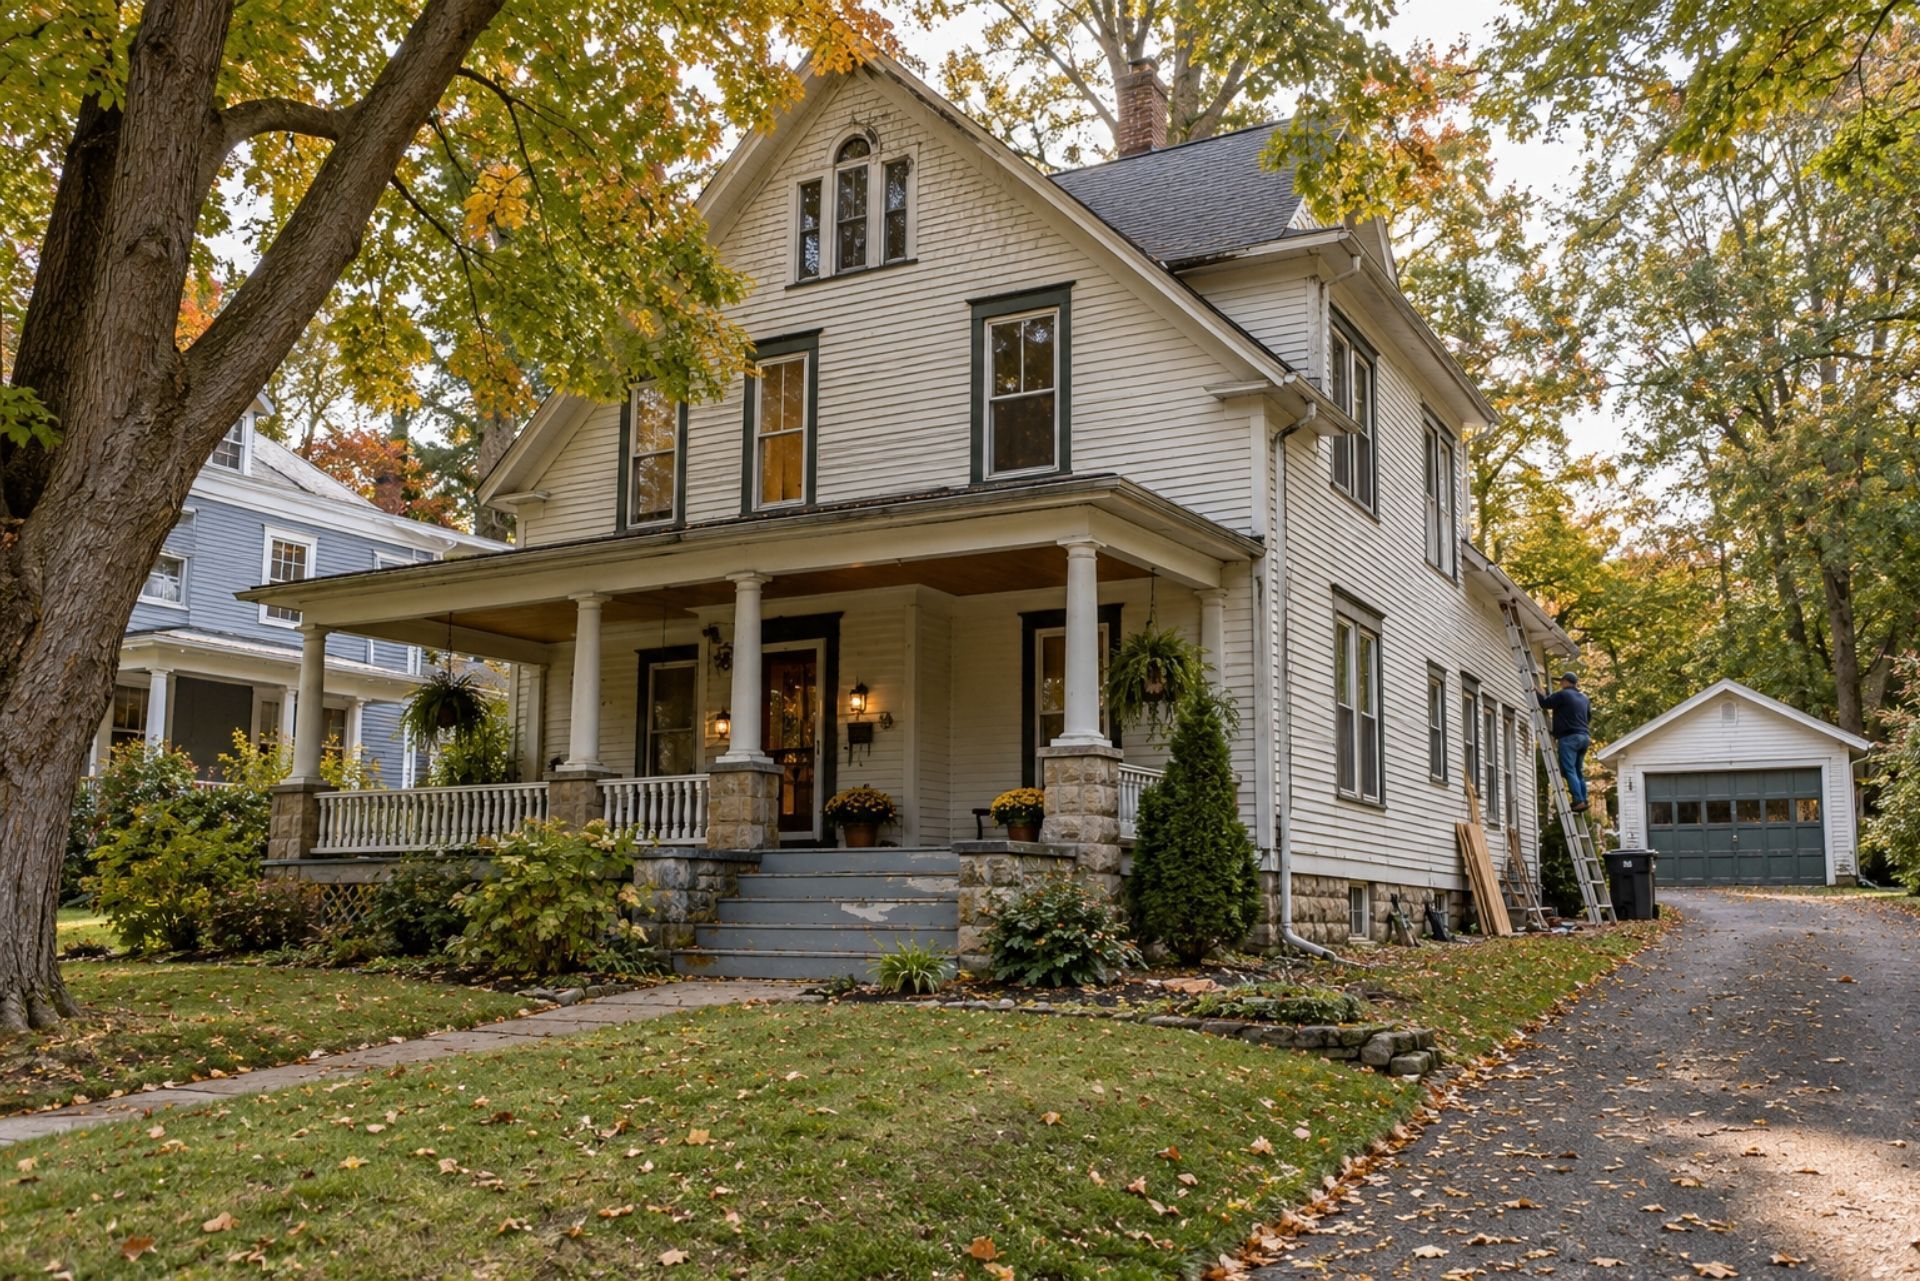
A historic Poland home usually needs a policy written around its actual construction, not a generic per-square-foot estimate. Poland Village has a recognized historic district (confirm current boundaries with the village before relying on a designation). Many of the older homes clustered around the village center and near Poland Seminary High School date back well over a century.
These houses were built by hand. Think plaster over wood lath, old-growth timber framing, hand-cut stone foundations, wavy glass windows and custom millwork that no big-box store stocks. A standard policy might pay to repair a damaged parlor wall with drywall and stock trim. That repair would be covered on paper, but your home would lose part of what makes it a local landmark.
The most common mistake we see is a historic home insured like a 1990s colonial. Here is what to ask about:
- Ordinance or law coverage: Pays for code-required upgrades after a loss, like bringing knob-and-tube wiring up to current code.
- Functional vs. like-kind replacement: Know which one your policy uses before you need it.
- Inspection requirements: For homes built before 1950, most 2026 insurers require an exterior and interior inspection within 60 days of binding to verify updated wiring and plumbing.
Keep a file of photos, past restoration invoices and contractor names. That paper trail makes valuation and claims much easier.

Written By
David Varrati
Owner, MVP Insurance
On this page
Multiple carriers
We quote your home, auto and other policies across the carriers we represent, look at how they pair for discounts, and show you the differences in coverage, not just the price.
Understanding Replacement Cost on Older Construction
Actual cash value falls short for a 19th-century home because it subtracts depreciation, and on a house that old, depreciation can consume most of the claim. ACV pays what the damaged item was "worth" in its aged condition. Replacement cost pays what it takes to rebuild. For a historic property, the gap between those two numbers can be enormous.
Here's a simple contrast. A modern build uses dimensional lumber, vinyl windows, drywall and laminate. Older construction in Poland often features chestnut or oak trim, plaster walls, slate roofs, and heart-pine floors. Rebuilding with those materials costs far more, and it requires tradespeople who know the old methods.
Guaranteed or extended replacement cost endorsements add a cushion above your dwelling limit when rebuild costs come in higher than expected. That cushion matters when a specialty plasterer or slate roofer has a waitlist and their rates reflect it.
Watch your roof terms too. Many Ohio carriers in 2026 are moving to ACV settlements for roofs over 15 years old. That shift can turn a $15,000 roof claim into a $5,000 payout. Read the roof section of your declarations page, not just the dwelling line.
Written By
David Varrati
Owner, MVP Insurance
On this page
Pennsylvania FAIR Plan as a Last Resort
Some older homes can't find coverage in the voluntary market because of age, condition or a past claim. For those homes, the Pennsylvania FAIR Plan generally serves as the state's market of last resort for basic property insurance. It typically offers narrower protection than a standard homeowners policy and often lacks liability coverage. Treat it as a bridge while you update the roof, electrical or plumbing, then shop the regular market again.
Yellow Creek Flood Exposure and Coverage Options
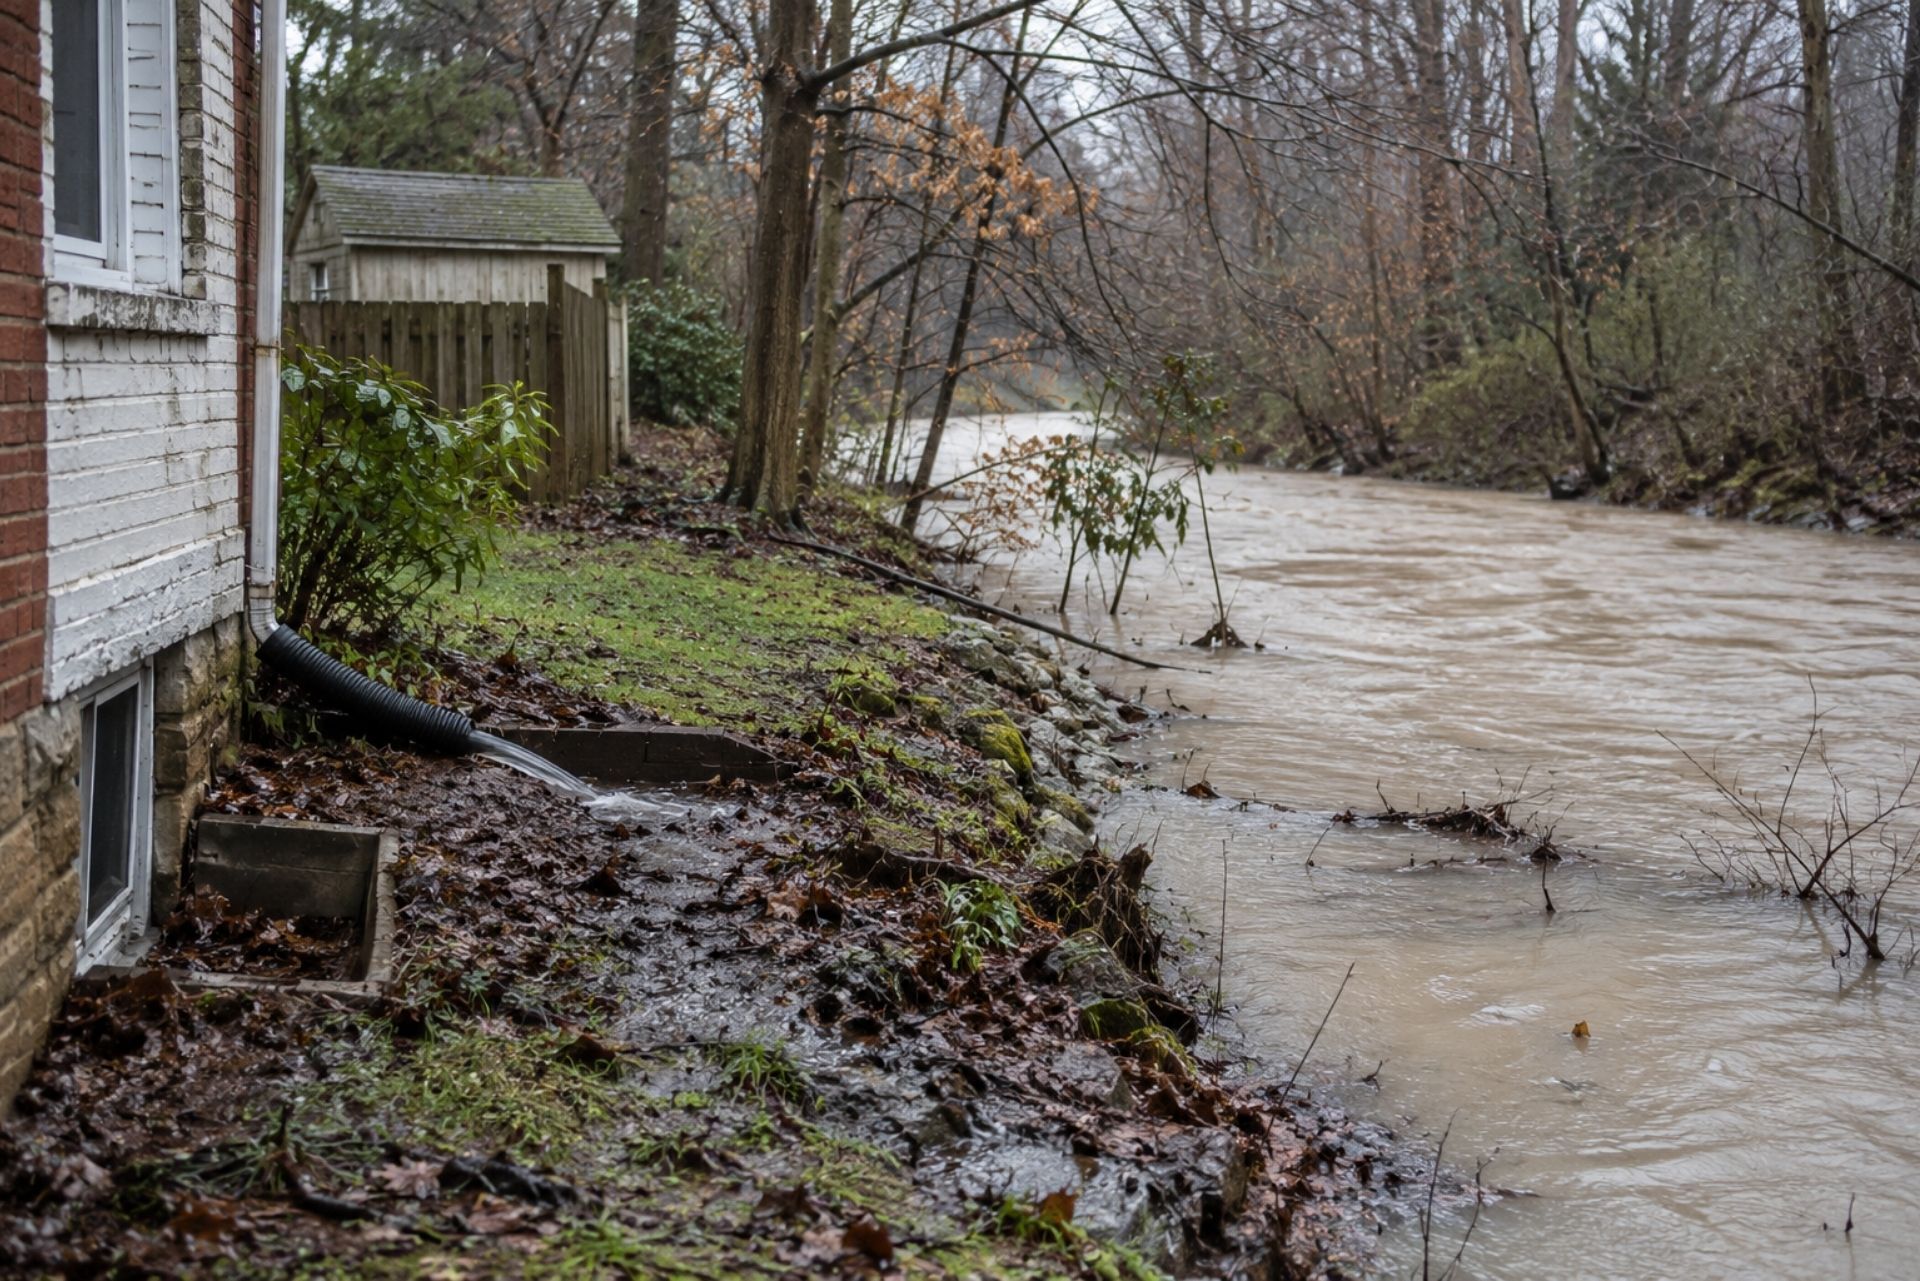
Your standard homeowners policy does not cover flooding from Yellow Creek. Rising surface water is excluded across virtually every home policy, so properties near the creek need a separate flood policy.
The risk isn't theoretical. A watershed study found that development and lawn runoff in Poland and Boardman Townships are increasing the erosive power of the Yellow Creek watershed. More pavement and turf means water reaches the creek faster, which raises flood risk for homes along the banks.
Then came July 2026. A macroburst and slow-moving thunderstorms caused significant flash flooding across Mahoning County, and the county declared a state of emergency. Some homeowners discovered after the storm that their policies had no flood protection at all.
Two coverage gaps tend to surprise people:
- Flood insurance is a separate policy, through the NFIP or a private flood carrier. Most new flood policies have a waiting period before they take effect, so buy it before the forecast turns.
- Water backup coverage handles sewer or sump pump overflow. Most 2026 policies in Poland exclude it unless you add it as an endorsement.
Living outside a mapped flood zone doesn't mean you're safe. Flash flooding doesn't check FEMA maps first.
Mature Trees and Wind Damage Risks
Windstorm coverage on a standard Ohio homeowners policy generally pays for roof and structural damage when a tree falls on your house. It also usually pays for removal of the tree from the structure, up to a set limit. Poland Village's big, old trees are part of its character, but they turn into serious hazards during severe storms.
The same July 2026 weather brought straight-line winds up to 90 mph that toppled an estimated 1,000 trees in Mahoning County. Many residents were still recovering months later. A single mature oak through a slate roof can create a five-figure claim before anyone touches the interior.
Here's how coverage typically breaks down:
- Tree hits the house or garage: Damage and removal are usually covered, subject to your deductible.
- Tree falls in the yard and hits nothing: Removal often isn't covered, or only a small amount is paid.
- Neighbor's tree falls on your home: Your policy usually responds first, unless the tree was visibly dead and the neighbor ignored it.
- Debris removal limits: These are often capped as a percentage of the dwelling limit, so check yours.
Check your wind or hail deductible, too. Some policies use a percentage of dwelling value instead of a flat dollar amount. And have an arborist look at large trees close to the house every few years. Insurers can deny claims tied to obvious neglect.
Comparing Coverage Limits for Poland Properties
Your coverage limits should match what it costs to rebuild and replace, not what you paid for the house. Here's how the main parts of a policy apply to a typical older Poland home.
| Coverage | What It Covers | Poland Consideration |
|---|---|---|
| Dwelling (A) | The house itself | Base on rebuild cost with historic materials; add extended replacement cost |
| Other Structures (B) | Detached garages, carriage houses, fences | Older carriage houses may need more than the default 10% |
| Personal Property (C) | Furniture, clothing, belongings | Choose replacement cost; schedule antiques separately |
| Liability (E) | Injuries or damage you're responsible for | Consider higher limits or an umbrella for large lots and old trees |
| Flood (separate) | Rising water damage | Needed for homes near Yellow Creek |
| Water Backup (endorsement) | Sewer and drain overflow | Usually excluded unless added |
One more note on Personal Property: antique furniture and heirloom pieces often face sub-limits. A scheduled personal property rider lists them individually, so a claim pays their appraised value.
Common Questions About Poland Home Insurance
Does my insurance cover Yellow Creek flooding? No. Standard homeowners policies exclude flooding from rising water, so you need a separate flood policy.
How do I insure a historic house in Poland Village? Start with replacement cost coverage based on historic materials and add ordinance or law coverage. An independent agent can compare carriers that handle older homes well.
Will my insurer inspect my old house? Probably. For homes built before 1950, most insurers in 2026 require an inspection within 60 days of binding to check wiring and plumbing.
Is tree removal covered after a storm? Usually, if the tree damaged a covered structure. Trees that fall without hitting anything often aren't covered.
Why did my roof claim pay so little? Your policy may settle older roofs at actual cash value. Many Ohio carriers now apply ACV to roofs over 15 years old.
Do I need water backup coverage? If you have a basement or sump pump, it's worth adding. Most Poland policies exclude it by default.
Securing Your Poland Home with MVP Insurance
Owning a historic or high-value home in Poland means paying attention to things a basic policy skips. Those include replacement cost that reflects real craftsmanship, a separate flood policy if Yellow Creek is nearby, and wind and debris limits that fit the trees on your lot. The July 2026 storms showed how quickly these gaps turn into out-of-pocket bills.
For a personalized review, call our New Springfield office at (330) 707-9055, just next door to Poland. You can also reach our Zelienople office at (724) 453-1122. As an independent agency, we compare multiple carriers and work for you, not the insurer. We also offer 24/7 claims support for when a storm hits at 2 a.m.
When you're ready, start your quoteand we'll handle the comparison work. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













