


Owner, MVP Insurance
Pennsylvania collector car insurance is a specialty policy for vehicles that hold or gain value over time. It typically pays an agreed value instead of a depreciated one, expects careful storage and limited hobby use, and works alongside PennDOT's antique and classic registration rules. It also covers car shows, club events, and restoration projects in progress.
If you own a '67 Camaro, a pre-war Ford, or an air-cooled Porsche sitting under a cover in your garage, a standard auto policy probably undervalues it. Most owners discover this the hard way, after a fire or a garage collapse, when the adjuster's number comes back far below what the car would bring at auction. Below we explain how these policies work in Pennsylvania, what the state expects from antique and classic plate holders, and how to protect a car that's still on jack stands.
Understanding Pennsylvania Collector Car Insurance
Collector car insurance is built for vehicles that appreciate, or at least hold steady, rather than lose value every year like a commuter sedan. Standard auto carriers price policies around depreciation and daily driving risk. A collector policy assumes the opposite: low mileage, careful ownership, and a car that may be worth more next year than it is today.
These policies are usually written through specialty carriers. At MVP Insurance, we typically place collector vehicles with Hagerty and J.C. Taylor, two companies that focus on classic and collectible cars. As an independent agency, we compare options for you instead of steering you toward one company's product.
Eligibility goes beyond the car itself. Carriers commonly require that every licensed driver in your household have a regular daily driver insured on a standard auto policy. That proves the classic isn't your main transportation. You can talk through your collection with our team at the Zelienople, PA office or the New Springfield, OH office. If you landed here from our old Collector Car page, this guide replaces it.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
How Agreed Value Coverage Protects Your Investment
Agreed value coverage pays the full amount you and the insurer settled on when the policy was written if the car is totaled. No depreciation is subtracted and there's no argument over comparable sales after the fact. That certainty is the main reason collectors buy these policies.
Standard auto insurance usually pays actual cash value, which factors in depreciation when calculating a total loss. For a 1970 Chevelle SS, that can mean the adjuster values it like an old Chevy rather than a numbers-matching muscle car. The gap can easily run into tens of thousands of dollars.
Here's how the two approaches compare:
| Feature | Actual Cash Value | Agreed Value |
|---|---|---|
| Payout on total loss | Market value minus depreciation | Full amount set at policy start |
| Valuation timing | Decided after the claim | Decided before the claim |
| Fits appreciating cars | Poorly | Well |
| Documentation needed | Little upfront | Photos, appraisals, receipts |
The most common mistake we see is setting the value once and never revisiting it. Classic values move. Review your agreed value each renewal, especially after a strong auction season or a major mechanical upgrade.

Written By
David Varrati
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Mileage and Storage Rules for Specialty Vehicles
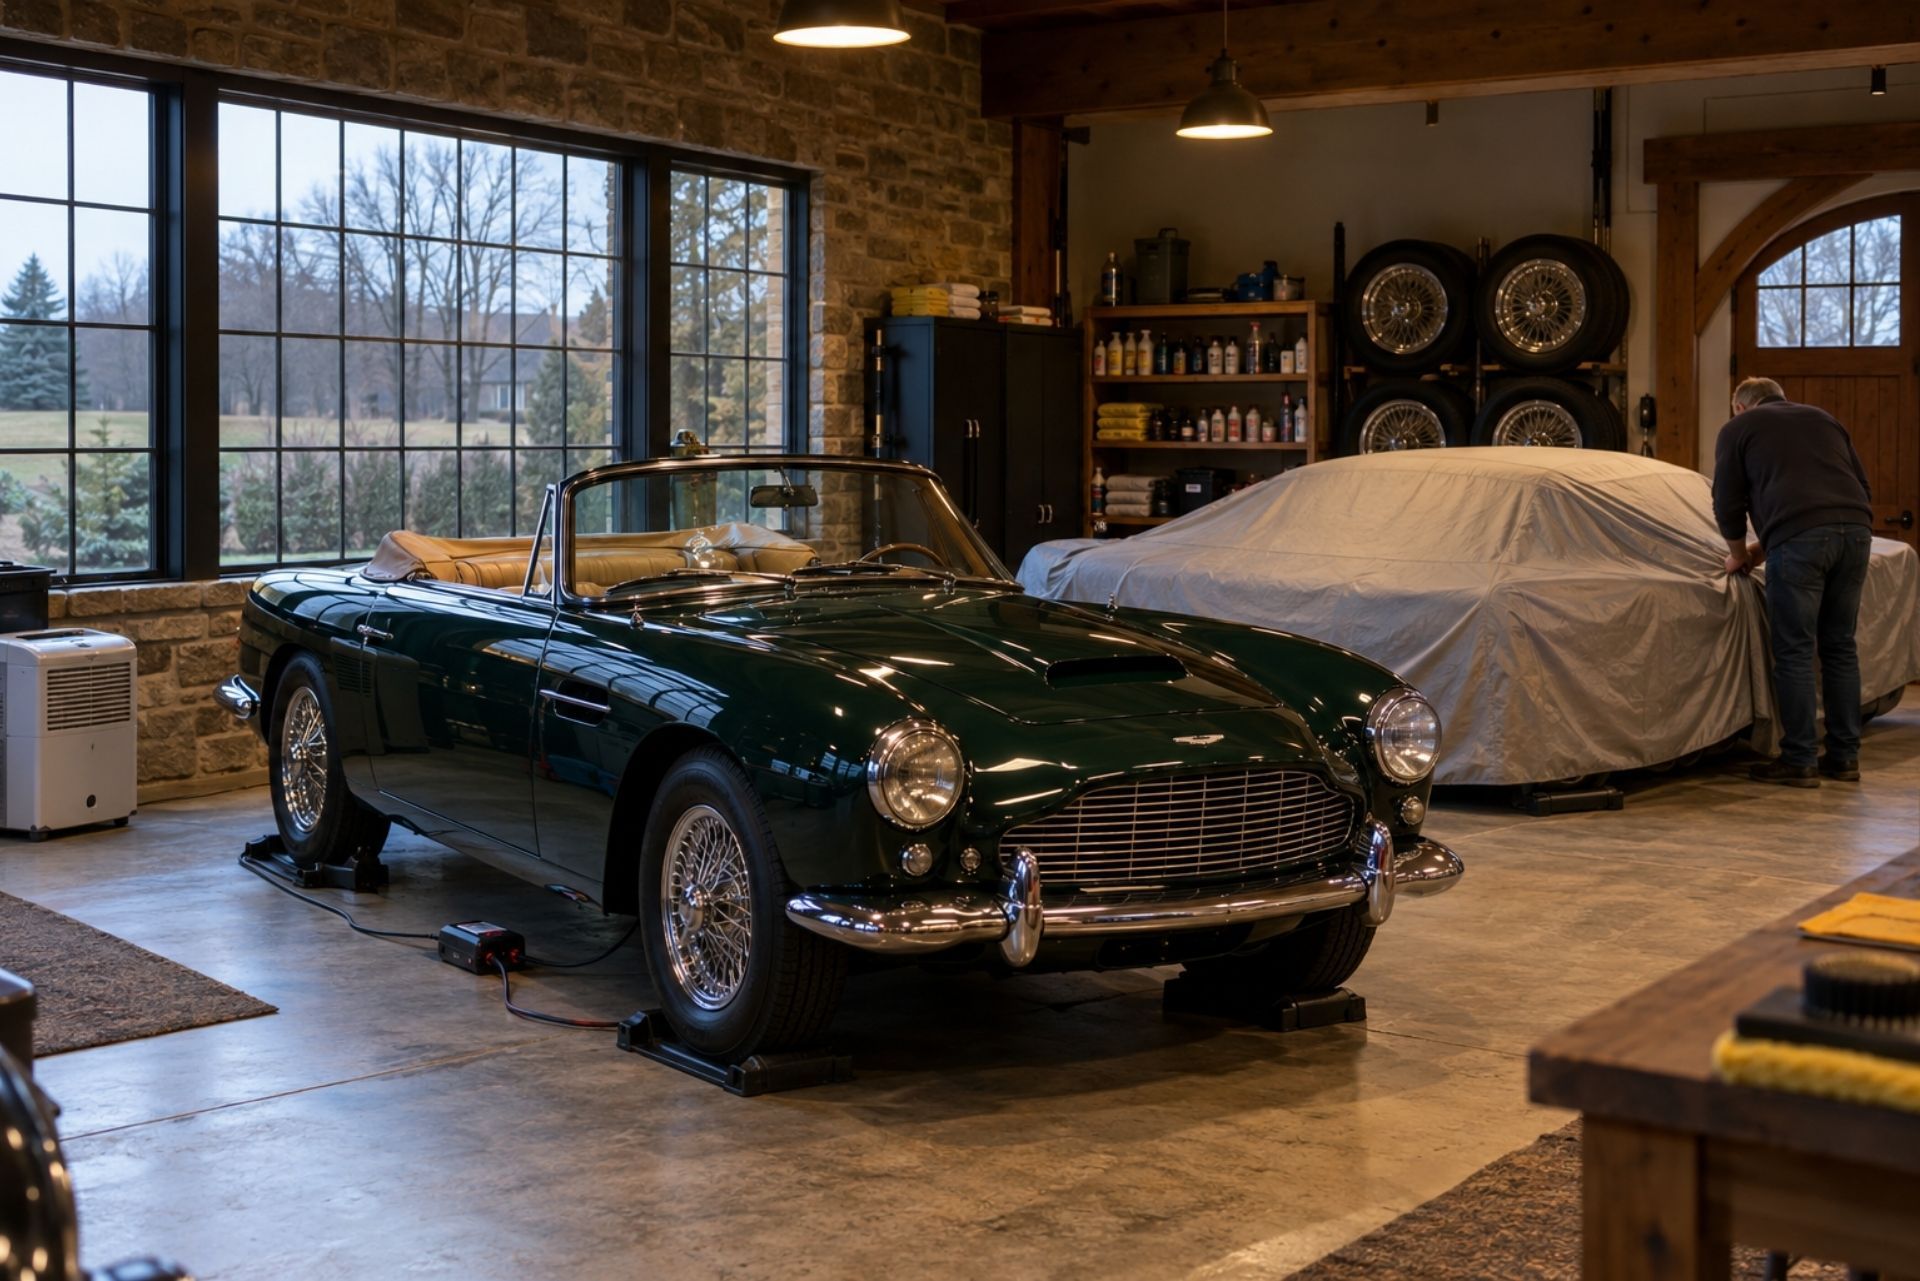
Collector policies generally require the vehicle to live in a fully enclosed, locked garage. They also expect it to be used mainly for hobby driving rather than commuting, errands, or work. These conditions keep premiums lower, and carriers take them seriously.
Storage rules exist because most collector car losses happen while the car is parked. Theft, hail, falling trees, and vandalism are far less likely behind a locked door. A carport, a tarp in the driveway, or a shared barn with an unlocked side door often won't qualify. If you store the car in a rented unit, ask your agent before signing the lease.
Usage limits vary by carrier and plan. Some policies set an annual mileage cap, while others allow flexible pleasure driving as long as the car isn't your daily transportation. A few practical habits help keep coverage clean:
- Log your drives. A simple notebook in the glovebox showing dates and destinations helps if a claim is questioned.
- Skip the commute. Driving the GTO to the office "just this once" can create a coverage dispute after an accident.
- Tell us about moves. Relocating the car to a new garage or a winter storage facility can affect your eligibility.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan

Antique and Classic Registration With PennDOT
PennDOT offers special plates for antique, classic, and collectible vehicles, and each comes with usage limits stricter than a standard registration. Under PennDOT definitions, antique vehicles must be at least 25 years old and classic vehicles at least 15 years old. Collectible vehicles have their own separate eligibility rules.
Usage is restricted. Antique and classic vehicles are limited to club activities, exhibits, and occasional transportation, defined as no more than one day per week. Additional conditions, such as limits on nighttime driving, can apply depending on the plate type and the vehicle's equipment. Owners should read their plate's terms carefully.
Legislators are also looking at these rules. Pennsylvania House Bill 368, reported as committed on October 5, 2026, seeks to clarify that these vehicles can carry people or property to permitted events without breaking registration rules. That matters if you haul trophies, parts, or passengers to a show.
If you want period correctness, owners can display a Pennsylvania plate issued between 1906 and 1976 that matches the vehicle's model year by filing Form MV-11V. More details are on PennDOT's vintage plate application page. It's a nice contrast to the Liberty Bell style standard plate PennDOT moved to in June 2025.
Comparing PennDOT Plate Requirements
| Requirement | Antique | Classic |
|---|---|---|
| Minimum age | 25 years | 15 years |
| Safety inspection | Generally exempt | Generally required |
| Emissions testing | Generally exempt | Generally exempt |
| Permitted use | Club events, exhibits, occasional use | Club events, exhibits, occasional use |
| Permanent plate fee | $102 as of this writing | $102 as of this writing |
A $72 title fee may also apply if a new title is needed. Registration is filed on Form MV-11. Keep in mind that your plate's limits and your insurer's usage rules are separate. You need to follow both.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Coverage for Show and Club Events
Collector insurance is built for the way enthusiasts actually use their cars: exhibitions, parades, cruise nights, and club tours. Coverage typically includes liability if your car injures someone or damages property during an event. It also includes physical damage protection if the car is hit, scraped, or vandalized while on display.
Think about a typical fall weekend in western Pennsylvania. The Summit Mountain Early Iron Car Club hosted a classic car show in Uniontown on October 21, 2026, the kind of event where hundreds of cars park inches apart on grass. A spectator leaning on a fender with a belt buckle, a kid's bike tipping into a door, or a fellow exhibitor backing into your bumper are all realistic claims.
Parades raise different risks. Slow driving with crowds close to the curb increases the chance of a liability claim. Ask your agent a few questions before event season. Does the policy cover the car on a trailer heading to the show? Is spare parts or tool coverage included? Is roadside help or flatbed towing part of the plan? Small gaps like an uncovered trailer can turn a minor mishap into an expensive one.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Insuring Restoration Projects in Progress
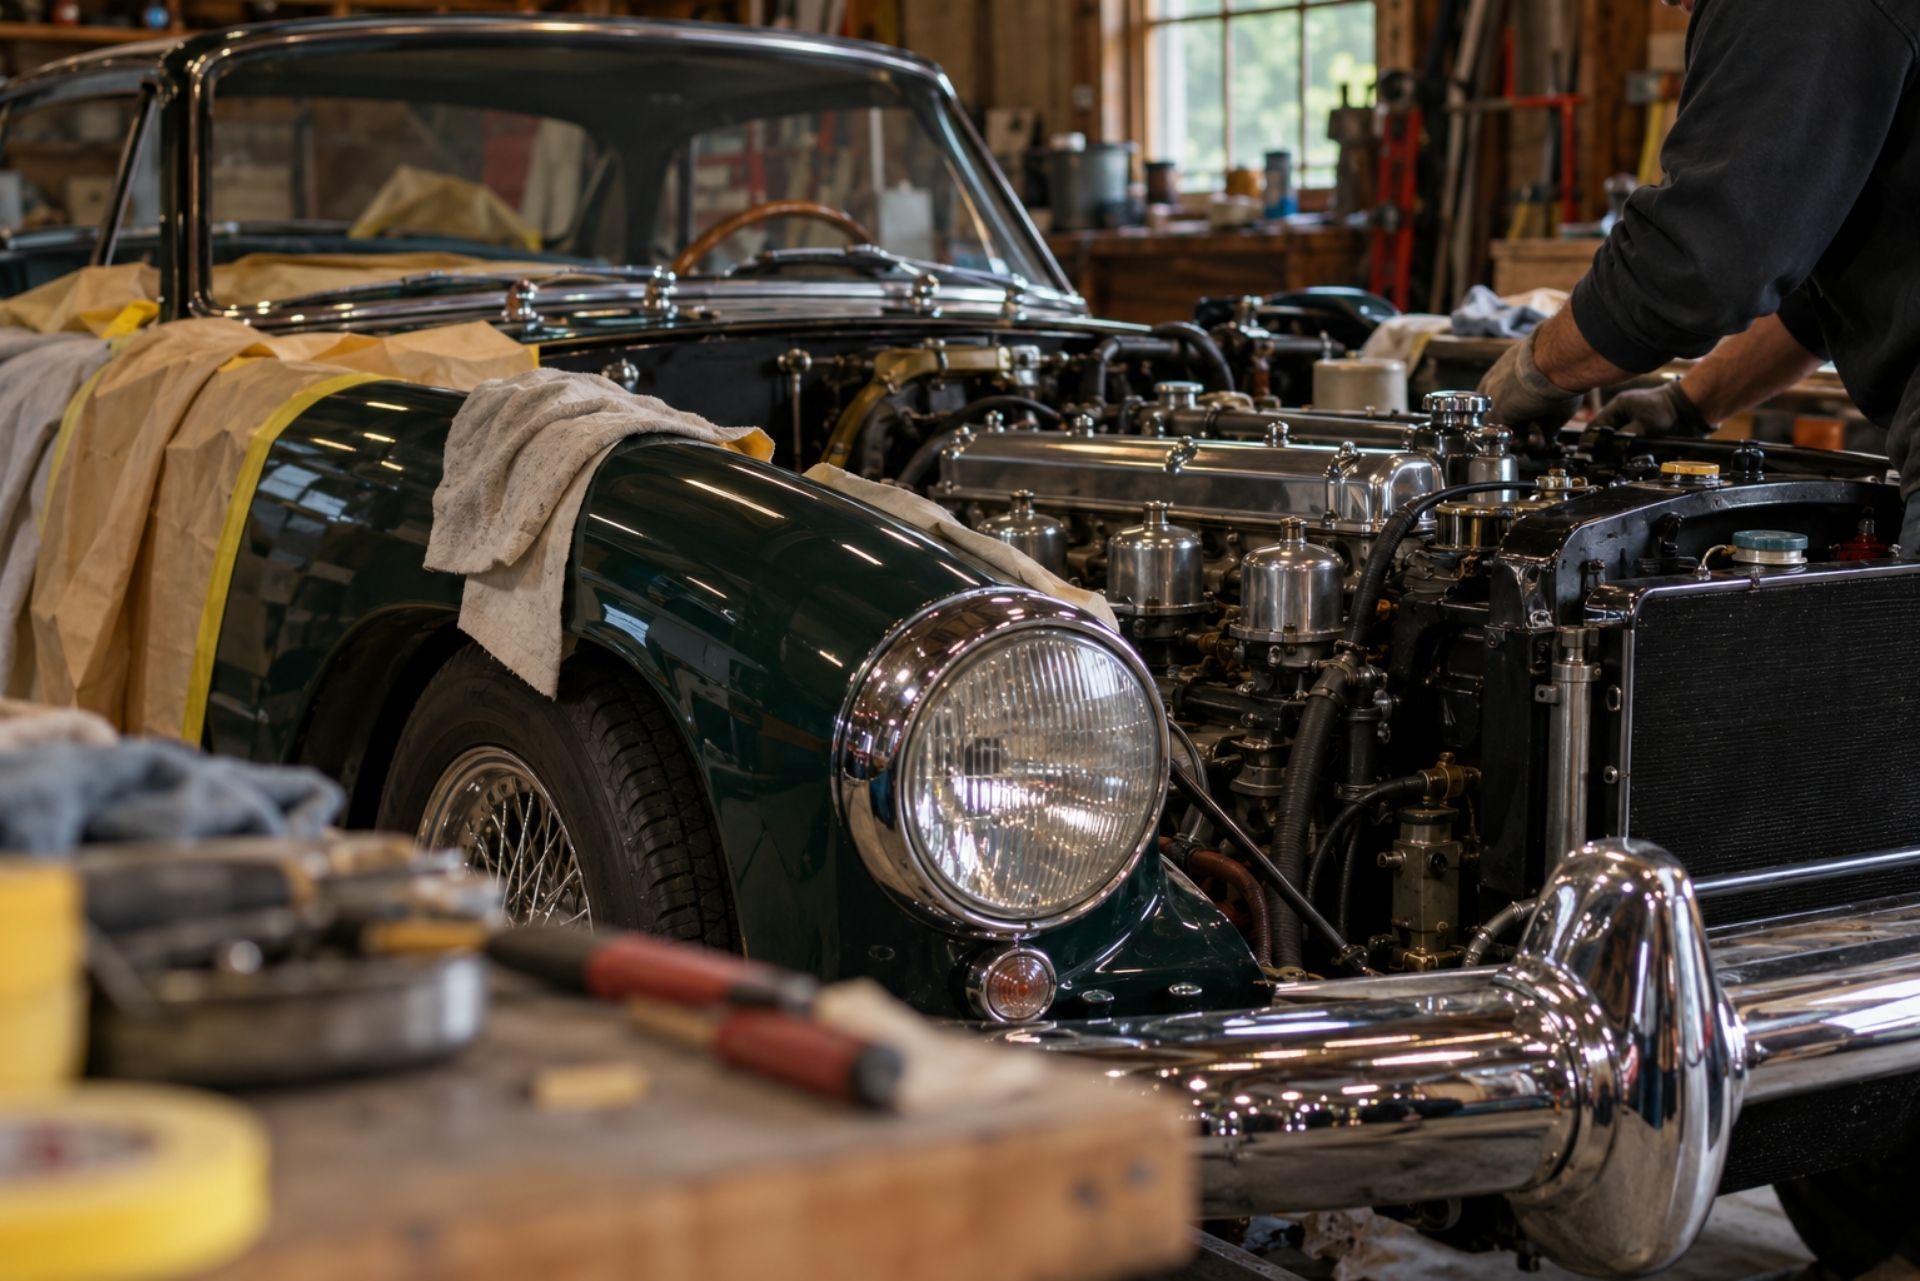
A car in pieces can still be insured. Many collector policies let you cover a restoration project at its current value, then raise the limit as work progresses and the car becomes worth more. That protects you during the riskiest stretch, when parts are scattered across the garage and the shell sits on a rotisserie.
Here's a realistic scenario. You buy a rusty 1965 Mustang fastback for $18,000 and plan to spend two years on bodywork, paint, and an engine rebuild. Insuring it at $18,000 makes sense on day one. By the time fresh paint is curing, the car may be worth double, and a shop fire at the old value would leave you badly short.
To keep coverage current through the project:
- Photograph each stage. Before, during, and after shots support a value increase.
- Save every receipt. Parts, labor, and machine shop invoices document the money invested.
- Call at milestones. Paint completion and final assembly are natural points to raise your limit.
- Ask about off-site coverage. Cars at a body or upholstery shop may need confirmation that they're protected away from your garage.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Private Client Services for High Value Collections
Serious collectors usually have more than one valuable car, and often a home, jewelry, or art collection that needs equal attention. That's where MVP's private client insuranceservices come in. We coordinate coverage across your assets so limits, deductibles, and liability protection work together instead of overlapping or leaving holes.
A common gap appears when someone keeps a $250,000 collection in a detached garage that their homeowners policy barely recognizes. Pairing collector auto coverage with high value home insurance in Pennsylvaniaaddresses the building, its contents, and the liability exposure of hosting club gatherings on your property. An umbrella policy can then sit on top of everything.
Because we're 100% independent, we work for you, not a carrier. We shop options from specialty markets like Hagerty and J.C. Taylor alongside your other coverage. Our 24/7 claims support also means you're not waiting until Monday if something happens on a Saturday show weekend. To get started, contact Josh Medure or David Varrati to Request a Private Client Review.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Common Questions About Pennsylvania Collector Car Insurance
Can I drive my classic car to work on a collector policy? Generally, no. Collector policies are meant for hobby use, and commuting can put a claim at risk. Your PennDOT antique or classic plate also limits occasional use to no more than one day per week.
How old does my car need to be for an antique plate in PA? PennDOT requires antique vehicles to be at least 25 years old. Classic vehicles must be at least 15 years old.
Do I need a separate daily driver to get collector insurance? Usually, yes. Carriers typically expect every licensed driver in the household to have a regular car insured on a standard policy.
Can I insure a car that doesn't run yet?Yes. Restoration projects can be insured at their current value, and you can raise the limit as work moves forward.
Are antique cars exempt from inspection in Pennsylvania? Antique-registered vehicles are generally exempt from both annual safety and emissions inspections. Classic vehicles are generally exempt only from emissions testing.
What happens if my collector car is totaled?With agreed value coverage, you receive the full amount set when the policy was written, without depreciation deducted.
The right collector policy comes down to three things: an agreed value that keeps up with the market, storage and usage habits that match your policy terms, and registration that fits how you actually drive. Get those aligned and you can enjoy show season without wondering whether a bad day would cost you the car. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. When you're ready, reach out to our Zelienople or New Springfield team to
start your quote. We'll compare collector options so your car is covered for what it's actually worth.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.












