


Owner, MVP Insurance
Erie PA car insurance works best when it is built around winter. That means solid liability limits for pileups on I-90 and I-79, comprehensive coverage for snow and ice damage, a deliberate choice between Limited and Full Tort, and the right garaging setup for Gannon and Mercyhurst students. A bare minimum policy rarely covers what a real Erie February can do.
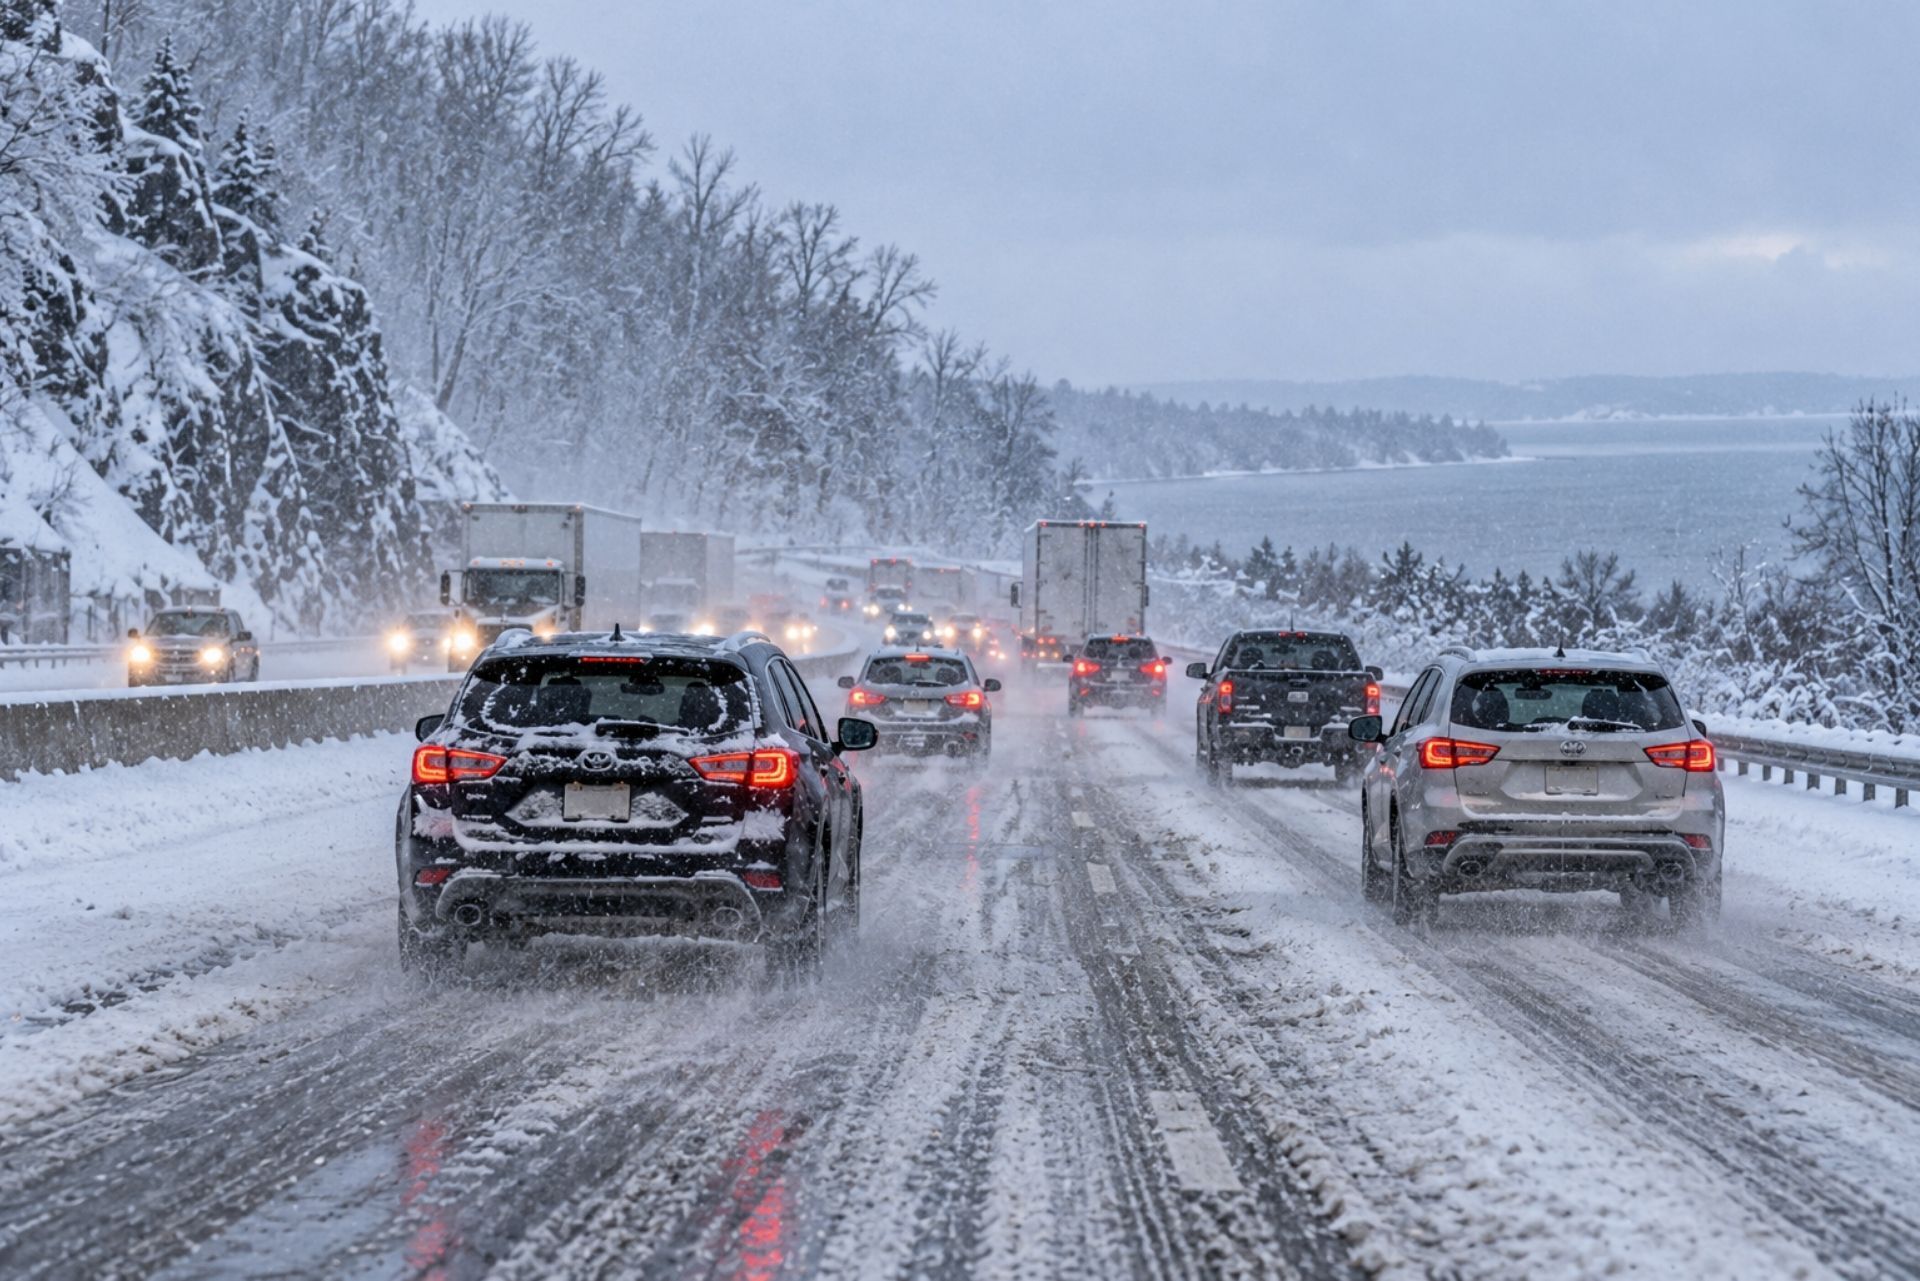
Anyone who has driven the Bayfront Parkway during a squall knows the lake decides how your commute goes. The forecast says two inches, and an hour later you can't see the taillights in front of you. Insurance in this corner of Pennsylvania should reflect that, and many policies don't.
Erie PA Car Insurance for Winter Driving and Local Students
A good Erie policy protects you from three things: other drivers in bad weather, weather itself, and the legal choices Pennsylvania asks you to make up front. If you only think about the monthly payment, you'll likely miss one of them.
Erie sits right on the lake effect snow belt, and I-90 carries steady traffic through the worst of it. That combination produces chain-reaction crashes, the kind where your car gets hit and then hits someone else. On top of that, Pennsylvania's tort system forces every driver to pick between Limited and Full Tort, a decision that shapes what you can recover after an injury.
Then there are the students. Gannon and Mercyhurst bring thousands of young drivers to the city every fall, many of them on a parent's policy from Pittsburgh, Ohio, or out of state. Where that car actually sleeps at night matters to the insurer. Statewide, the average cost of car insurance in Pennsylvania runs about $1,401 per year, but local risk factors like weather and parking density push Erie rates in their own direction. For a statewide look at requirements, see our guide to car insurance in Pennsylvania.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
| Coverage | PA Minimum | Common Recommendation |
|---|---|---|
| Auto bodily injury | $15,000 / $30,000 | $250,000 / $500,000 |
| Auto property damage | $5,000 | $100,000 |
| Medical benefits (auto) | $5,000 | $10,000 or more |
| Home personal liability | None required | $300,000 to $500,000 |
| Umbrella | None required | $1 million or more |
Navigating Lake Effect Snow and Winter Collisions on I-90 and I-79
Lake effect snow raises your odds of a multi-vehicle crash, and higher liability limits are the main protection when one happens. Erie averages heavy lake effect snow each winter (verify current seasonal totals at publish), and the bands can drop visibility to near zero in minutes.
Whiteouts are the real danger. Drivers heading toward Presque Isle State Park or along the I-90 corridor east of the city can go from clear pavement to a wall of white with almost no warning. When one car brakes hard, three or four behind it often can't stop. I-79, which funnels traffic in from the south, sees similar backups where it meets I-90.
Here's the coverage gap we see most often in these claims: a driver with low liability limits causes a chain collision involving several vehicles. Their property damage limit gets used up on the first two cars, and the remaining damage and injury claims come after them personally. In a pileup, total damages can climb fast, especially if a newer SUV or a commercial truck is involved.
A few practical steps help:
- Raise liability limits before winter, not after a close call
- Add uninsured and underinsured motorist coverage in case the driver who hits you carries only the minimum
- Carry collision coverage on any vehicle you couldn't afford to replace out of pocket

Written By
David Varrati
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Comprehensive Coverage for Weather Damage and Falling Ice
Comprehensive coverage pays for damage that isn't caused by a collision, which in Erie often means snow and ice. Without it, a crushed roof or shattered windshield from a weather event usually comes out of your own pocket.
The claims we see in this region are specific. A sheet of ice slides off an apartment roof downtown and caves in a hood. A heavy, wet snow load brings down a tree limb onto a car parked in the driveway. Hail cracks a windshield in early spring. None of these involve another car, so collision coverage won't help, and liability never covers your own vehicle.
One common mistake: people drop comprehensive on an older car to save a few dollars, then park it under the same icy eaves every winter. If the car is worth more than a few times your annual comprehensive premium, keeping the coverage usually makes sense. Pick a deductible you could actually pay in January, not one that looks good on paper.
Falling ice can also damage property beyond the car. If it comes off your house, your homeowners policy may come into play, so it's worth reviewing your Erie homeowners insurancealongside your auto coverage.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Life Insurance
Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.
Understanding Pennsylvania Tort Options for Erie Residents
Pennsylvania makes you choose between Limited Tort and Full Tort, and that choice decides whether you can sue for pain and suffering after a crash. Full Tort keeps that right open. Limited Tort lowers your premium but restricts those claims to serious injuries.
This sits inside Pennsylvania's choice no-fault system, which also requires every driver to carry at least $5,000 in medical benefits coverage. That medical coverage pays your bills regardless of fault. The tort option covers something different: compensation for pain, lost enjoyment of life, and similar non-economic harm.
With Limited Tort, if another driver slides into you on I-90 and you walk away with a painful neck injury that heals over a few months, you may have no right to recover for that suffering. The law generally reserves those claims for injuries that meet a "serious" threshold, and the definition gets argued over constantly.
Our honest take: the savings from Limited Tort tend to be modest, and the rights you give up can be significant. In a region where winter crashes are routine, Full Tort is the option we'd want most families to at least price out before deciding.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Coverage for Gannon and Mercyhurst Students
Students at Gannon University or Mercyhurst University should confirm their policy lists the correct garaging location. If the car lives in Erie during the school year, the insurer needs to know.
Garaging matters because rates are set partly by where the car is parked overnight. A policy rated for a quiet suburb doesn't reflect downtown street parking near Gannon or a crowded lot on Mercyhurst's hillside campus. If a claim happens and the insurer learns the car has been in Erie for nine months, that mismatch can create headaches.
The flip side is good news for some families. If a student leaves the car at home and attends school more than a set distance away, many carriers offer away at school credits. Students from outside the area who don't bring a car might qualify. Those who bring one should plan for:
- Urban parking risk: door dings, hit-and-runs, and break-ins on city streets
- Winter driving inexperience: many students have never driven in lake effect snow
- Good student credits: often available for strong grades
- Clean driving record benefits: worth protecting all year
Parents should also confirm whether the student is listed as a driver on the right vehicle.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Life Insurance
Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.
Pennsylvania Minimum Coverage vs Recommended Limits
State minimums keep you legal, not protected. For Erie winters, MVP Insurance recommends looking at limits well above the floor, especially for liability and uninsured motorist coverage.
| Coverage | Pennsylvania Minimum | Recommended for Erie Winters |
|---|---|---|
| Bodily injury liability | State minimum required (verify current limits) | 100,000 per person / 300,000 per accident |
| Property damage liability | State minimum required (verify current limits) | 100,000 per accident |
| Medical benefits | $5,000 | Higher limit based on your health coverage |
| Uninsured/underinsured motorist | Optional | Match your liability limits |
| Comprehensive | Optional | Recommended, with an affordable deductible |
| Collision | Optional | Recommended for vehicles you can't easily replace |
| Tort option | Limited or Full | Price out Full Tort |
These recommended figures are a starting point, not a universal rule. Homeowners and people with savings to protect may want an umbrella policy on top. You can also lower total costs by bundling home and auto, keeping a clean record, or completing a defensive driving course.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Frequently Asked Questions About Erie PA Car Insurance
Is car insurance more expensive in Erie than elsewhere in Pennsylvania? It can be, depending on your neighborhood, vehicle, and driving history. The statewide average is about $1,401 per year, but local weather and traffic patterns affect Erie rates.
Does car insurance cover snow damage to my car? Yes, if you carry comprehensive coverage. It handles non-collision damage like falling ice, heavy snow, and fallen tree limbs.
Should I choose Limited Tort or Full Tort? Full Tort keeps your right to sue for pain and suffering after any injury. Limited Tort costs less but restricts that right to serious injuries, so compare the actual price difference before choosing.
Do college students in Erie need their own policy? Not always. Many stay on a parent's policy, but the insurer should know the car is garaged in Erie during the school year.
What happens if I cause a pileup on I-90? Your liability coverage pays the other drivers' damages up to your limits. Anything beyond that can become your personal responsibility, which is why higher limits matter here.
What is the minimum medical coverage in Pennsylvania? Every driver must carry at least $5,000 in medical benefits.
Winter in Erie tests every part of a policy at once: liability in a whiteout, comprehensive under a falling ice sheet, and the tort choice you made months earlier. As an independent agency, MVP Insurance shops multiple carriers for you so the coverage fits how you actually drive and park. Call our Zelienople office at (724) 453-1122 or our New Springfield office at (330) 707-9055 to speak with Josh Medure or David Varrati, or start your quote here. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













