


Owner, MVP Insurance
Coverage
Home
A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.
Auto
Auto insurance covers injuries and damage you cause to others, and with collision and comprehensive, your own vehicle too. Ohio and Pennsylvania set different minimums and Pennsylvania adds a tort choice, so we walk you through both before you pick limits.
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
Pennsylvania plumbers generally need four core protections: general liability for water damage and resulting damage claims, completed operations coverage for leaks that show up after you leave, commercial auto plus tool coverage for your van and equipment, and workers comp once you hire. Licensing comes from your municipality, not the state, so local rules matter too.
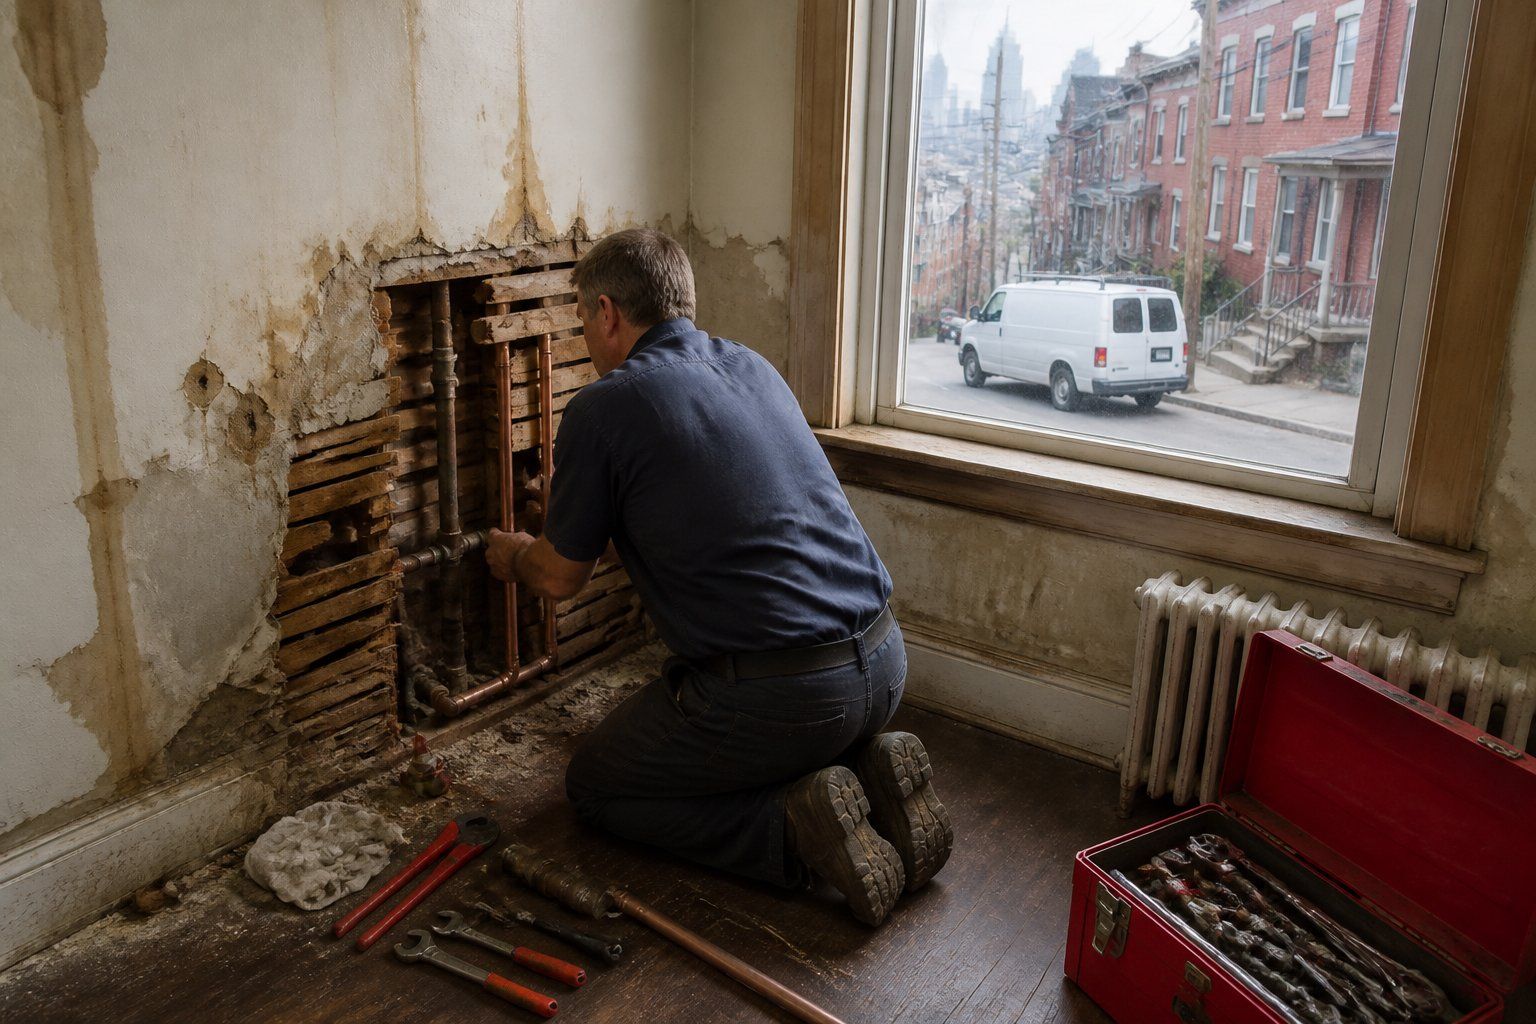
That's the short version. The longer version matters because plumbing claims don't look like other contractor claims. A carpenter's mistake usually stays put. A plumber's mistake travels through drywall, subfloors, finished basements, and sometimes into the condo unit downstairs. One weeping compression fitting behind a vanity can turn a $40 part into a five-figure loss before anyone notices a stain on the ceiling.
Plumbers in Pittsburgh, Cranberry, Butler, and the rest of western Pennsylvania also deal with a patchwork of local licensing rules, aging housing stock, and lead service line work that has its own regulatory weight. All of that shapes what your policy needs to do. The sections below walk through each piece of coverage, the claims we see most often, and the gaps that catch contractors off guard, so you can tell whether your current setup actually fits the work you do.
Essential Pennsylvania Plumber Insurance Coverage
A solid plumbing insurance program in Pennsylvania combines general liability, commercial auto, and workers compensation, each built around the two biggest risks in the trade: water damage and job site injuries. Most shops also add inland marine coverage for tools. None of these policies overlap much, so dropping one leaves a real hole.
MVP Insurance has been helping contractors put these pieces together since Josh Medure and David Varrati founded the agency in 2008. As an independent agency, we can quote Pennsylvania plumber insurance through carriers like Erie, Westfield, and Frederick Mutual, then compare how each one handles water damage exclusions, completed operations, and pricing for your class code. That comparison work is where many owners save money without giving up coverage. If you run other trades alongside plumbing, our contractors insurance options in Pennsylvania cover the broader picture.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Municipal Licensing in Pittsburgh and Allegheny County
Pennsylvania has no statewide plumbing license. Licensing happens locally, and in Allegheny County plumbers are generally licensed through the Allegheny County Health Department, while Pittsburgh and other municipalities may set their own requirements for registration and permits. Before you pull a permit in a new township, find out what that specific borough expects.
As of this writing, Allegheny County Master Plumbers face a $265 examination fee and a $375 annual renewal, while Journeymen pay $133 to test and $125 to renew. Residential contractors doing home improvement work also typically register under the state's HICPA program, where the registration fee rose to $100 every two years for applications processed after April 24, 2026.
Lead line work deserves special attention. The ACHD Plumbing Division now requires full replacement of lead water service lines with approved materials, with partial repairs prohibited. Many municipalities also ask for a certificate of insurance before issuing permits, so keep your COI current.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Water Damage and Resulting Damage Claims
Water damage and resulting damage claims after a failed joint or fitting are the most common plumbing liability loss, full stop. Your general liability policy is built to pay for the property damage the leak causes, not to replace the faulty pipe or redo your own work.
Here's how that plays out. Say you install a new supply line in a Mt. Lebanon kitchen, and a fitting lets go overnight. The homeowner wakes up to warped hardwood, ruined lower cabinets, and water in the finished basement. Your liability policy typically responds to the floors, cabinets, drywall, and contents. The fitting itself, and the labor to redo your connection, usually fall under the "your work" exclusion.
A few things we see trip plumbers up:
- Low limits: A $300,000 policy can disappear fast on a multi-unit building.
- Water damage sublimits: Some policies cap water losses well below the main limit. Read the endorsements.
- Late reporting: Waiting weeks to report a small leak can complicate the claim.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
The Role of Completed Operations Coverage
Completed operations covers claims that arise after the job is finished and you've left the site. For plumbers, this is arguably the most important part of the liability policy, because new installs rarely fail on day one.
A water heater connection might hold for three months before corrosion at a dielectric union starts dripping. A PEX crimp done slightly off can take a full heating season to fail. By then the homeowner has signed off, paid the invoice, and forgotten your name, until the ceiling stains. Without completed operations coverage, that claim lands on you personally.
Most contractor liability policies include products and completed operations under a separate aggregate limit. Look at that number, not just the per-occurrence limit. General contractors and property managers often require it on their certificates, sometimes with an additional insured endorsement that extends to completed work. If you're bidding commercial jobs, ask your agent whether your form includes that extension before you sign the subcontract.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Van and Tool Coverage for Plumbing Contractors
Your work van needs a commercial auto policy, and your tools need inland marine or dedicated tool coverage. Personal auto and standard property policies are not designed for either job, and both gaps show up constantly in claims.
Commercial Auto for Plumbing Vans
A personal auto policy can deny a claim if the vehicle is primarily used for business, carries an employee, or hauls equipment between job sites. Plumbing vans do all three every day. Commercial auto covers liability, physical damage, and hired or non-owned exposure when an employee drives their own truck to pick up parts. If your van is titled to the business, it needs commercial coverage, period. Carriers like Progressive write a lot of contractor vehicles, and pricing varies widely by driver history.
Inland Marine and Tool Floaters
Tools stolen from a van at a supply house aren't covered by commercial auto, and a business property policy usually only covers items at your shop. Inland marine, often called a tool floater, protects equipment in transit and on job sites. Plumbing tool policies typically run between $300 and $1,200 per year, depending on values and deductibles. Keep a list of serial numbers and photos: drain cameras and press tools are theft targets.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Workers Comp Requirements in Pennsylvania
Pennsylvania law requires any plumbing business with employees to carry workers compensation. It pays medical bills and lost wages for injured workers and generally shields your business from injury lawsuits by those employees.
Plumbing comes with real injury exposure: back strain from hauling water heaters, cuts, burns from soldering, and falls in crawlspaces. For 2026, the state's maximum weekly benefit is capped at $1,394.00, and workers earning $774.43 or less per week receive 90% of their average weekly wage for injuries on or after January 1, 2026.
Premiums are based on payroll. The 2026 published loss cost for plumbing (Class 0663) is $1.650 per $100 of payroll, and typical premiums land around $2.47 per $100 after carrier multipliers. A common mistake: misclassifying office staff or helpers, which inflates premiums or triggers audit surprises. Treating helpers as 1099 subcontractors when they function as employees is another expensive error.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Comparing Pennsylvania Plumber Insurance Options
Each coverage solves a different problem, and the table below shows how they line up for a typical Pennsylvania shop.
| Coverage | What It Covers | Common Limits | PA Requirement |
|---|---|---|---|
| General Liability | Water damage to client property, injuries to third parties | $1M per occurrence / $2M aggregate | Often required for permits and contracts |
| Completed Operations | Claims after the job is finished | Separate aggregate, often $2M | Frequently required by GCs |
| Commercial Auto | Work vans, drivers, liability on the road | $500K to $1M combined | State minimum auto liability applies |
| Inland Marine | Tools in transit and on job sites | Based on equipment value | Not required, strongly advised |
| Workers Comp | Employee injuries, medical, lost wages | Statutory | Required with employees |
Limits above reflect common contract requests, not legal minimums. Larger commercial jobs may require an umbrella policy on top. You can see how we approach other trades on our industries page.
Written By
David Varrati
Owner, MVP Insurance
On this page
Extra protection

Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
Boat, motorcycle, RV and ATV
Recreational vehicles need their own coverage for liability, physical damage and the gear that travels with them. A standard auto policy will not cover a boat on the water or an ATV on the trail.
Frequently Asked Questions About Plumbing Insurance
Do I need a license to be a plumber in PA?
There's no statewide plumbing license in Pennsylvania. Licensing is handled locally, such as through the Allegheny County Health Department, and individual municipalities may add their own rules.
What does completed operations cover?
It covers injury or property damage caused by your work after the job is done and you've left. A leak that appears months after an install is a classic example.
Does general liability pay to fix my bad fitting?
Usually not. It pays for the damage the leak causes, like floors and drywall, but not the cost to redo your own work.
Can I use my personal truck for plumbing jobs?
If the vehicle is used mainly for business, you need commercial auto. Personal policies often exclude business use.
Am I required to carry workers comp as a sole owner?
Pennsylvania requires it once you have employees. Sole proprietors without employees are generally not required to cover themselves, though some contracts ask for it.
How much does plumber insurance cost in Pennsylvania?
It depends on payroll, revenue, vehicles, and claims history. Tool coverage alone typically runs $300 to $1,200 a year.
Written By
David Varrati
Owner, MVP Insurance
On this page
Next step
What to have ready
Your address, the year, make and model of each vehicle, the drivers in the household, a rough list of valuables, and your current declarations pages if you have them. Contact either office or visit the Client Center if you already have a policy with us.
01
Tell us about your household
Your home, your vehicles, your drivers and anything else you want protected.
02
Import your current policies through Canopy or send your declarations
Use Canopy to share what you have today, or send us the declarations pages.
We shop and compare the carriers we represent
We compare coverage and price, then explain the differences in plain terms.
03
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Securing Your Quote with MVP Insurance
The right plumbing program covers the leak, the damage it leaves behind, the van that got you there, the tools in the back, and the crew doing the work. Most problems we find in existing policies are gaps between those pieces: a missing completed operations aggregate, a personal auto policy on a business van, or tools nobody insured.
Since 2008, MVP Insurance has shopped carriers like Progressive, Liberty Mutual, and Municipal Mutual on behalf of contractors across western Pennsylvania and eastern Ohio. Reach out to Josh Medure at our Zelienople office, 108 E Grandview Ave, (724) 453-1122, or our New Springfield office, 13823 Grant St, (330) 707-9055, for a review of your current policy. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
If you'd like a second set of eyes on your coverage before the next job, start your quote and we'll compare options for you. The time to find a gap is before the ceiling stains, not after.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
Joshua Medure
Owner, MVP Insurance
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto

Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.


Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.







