

Owner, MVP Insurance
Youngstown homeowners insurance works best when the policy matches the house you actually own: an older home with possible wiring issues, a basement that can back up, and a rebuild cost that often runs far above its sale price. The right coverage adds water backup protection, sets realistic theft limits, and insures for replacement cost.
That sounds simple on paper. In practice, plenty of Youngstown homeowners carry policies written as if they lived in a 2015 build in the suburbs, with limits based on what Zillow says the house would sell for. The gaps show up at the worst possible time: after a storm overwhelms the city sewers, after a fire starts in a 90-year-old junction box, or after a break-in clears out the garage.
The good news is that most of these gaps are fixable before a claim ever happens. A few endorsements, an honest look at your wiring, and a replacement cost estimate built on real construction numbers can change how a policy performs. The sections below walk through each risk that shows up again and again in Mahoning County homes, what insurers look for, and the mistakes worth avoiding when you shop.
Youngstown OH Homeowners Insurance for Older Housing Stock
Older homes need a policy written with their age in mind, because insurers price and underwrite them differently. Youngstown is the Mahoning County seat, and much of its housing stock predates 1950. That history gives the city real character, from the brick foursquares near Youngstown State University to the bungalows scattered along the I-680 loop, but it also means many homes carry original systems that underwriters scrutinize closely.
When an insurer reviews an older house, it usually asks about four things: the roof's age, the plumbing material, the heating system, and the electrical service. A home with a 1940s frame and a 2019 roof, PEX plumbing, and a modern panel looks very different on paper than the same frame with galvanized pipes and a fuse box. Two houses on the same street can get wildly different quotes for exactly this reason.
One common mistake is assuming the previous owner handled updates and having no proof. If you can't document when the roof was replaced or the panel was upgraded, some carriers will assume the worst. Keep receipts, permits, and contractor invoices in one folder (or a phone album) so you can answer underwriting questions on the spot.
MVP Insurance works with homeowners across the Youngstown area to match older properties with carriers that are comfortable with them. As an independent agency, MVP can compare several companies at once instead of forcing an older home into one carrier's narrow guidelines. You can see how statewide coverage options work on the Ohio homeowners insurance page.
Managing Risks with Updated Wiring
Wiring is often the single biggest hurdle for older Youngstown homes. Knob-and-tube systems, common in houses built before the 1940s, lack a ground wire and were never designed for modern electrical loads like space heaters, window AC units, and home offices. Insulation blown into walls over the decades can also trap heat around those old conductors.
Carriers take this seriously. Major insurers typically deny new applications for homes with active knob-and-tube wiring or require full removal within 30 days of closing. Aluminum branch wiring, used in some homes from the 1960s and 1970s, draws similar attention because connections can loosen and overheat over time.
If you're buying or already own an older home, here's a practical sequence:
- Get a licensed electrician's inspection that states in writing what wiring is present and whether any is still active.
- Replace or remediate knob-and-tube circuits entirely; for aluminum, ask about approved repair methods or full rewiring.
- Upgrade the panel if you still have fuses or a brand some insurers flag.
- Save the paperwork, including permits and the final inspection, to show the carrier.
The rewiring bill stings, but it opens up more carriers and lowers the odds of the claim nobody wants: an electrical fire inside the walls.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
The Impact of Vacant Neighbor Properties on Your Policy
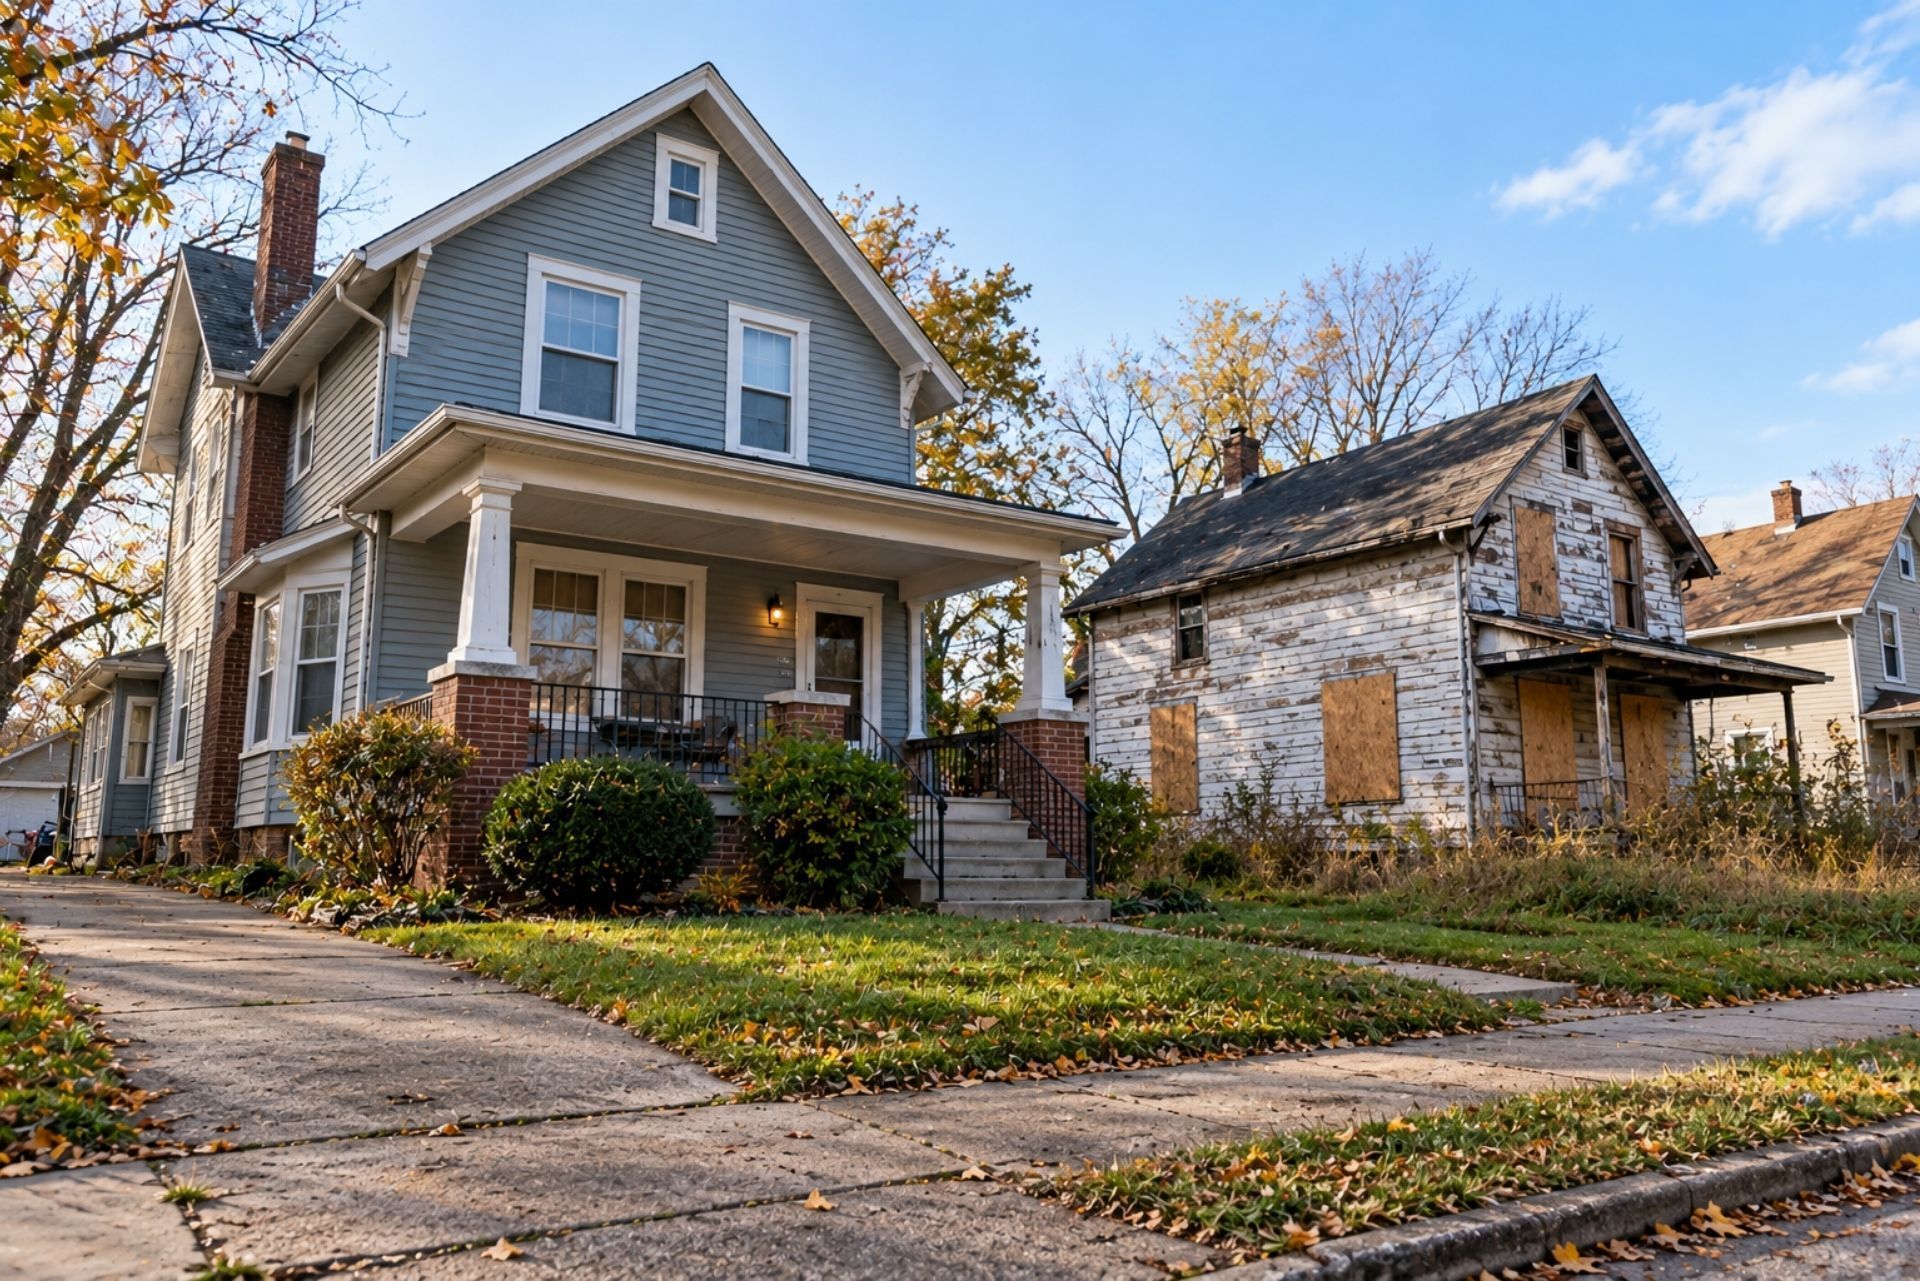
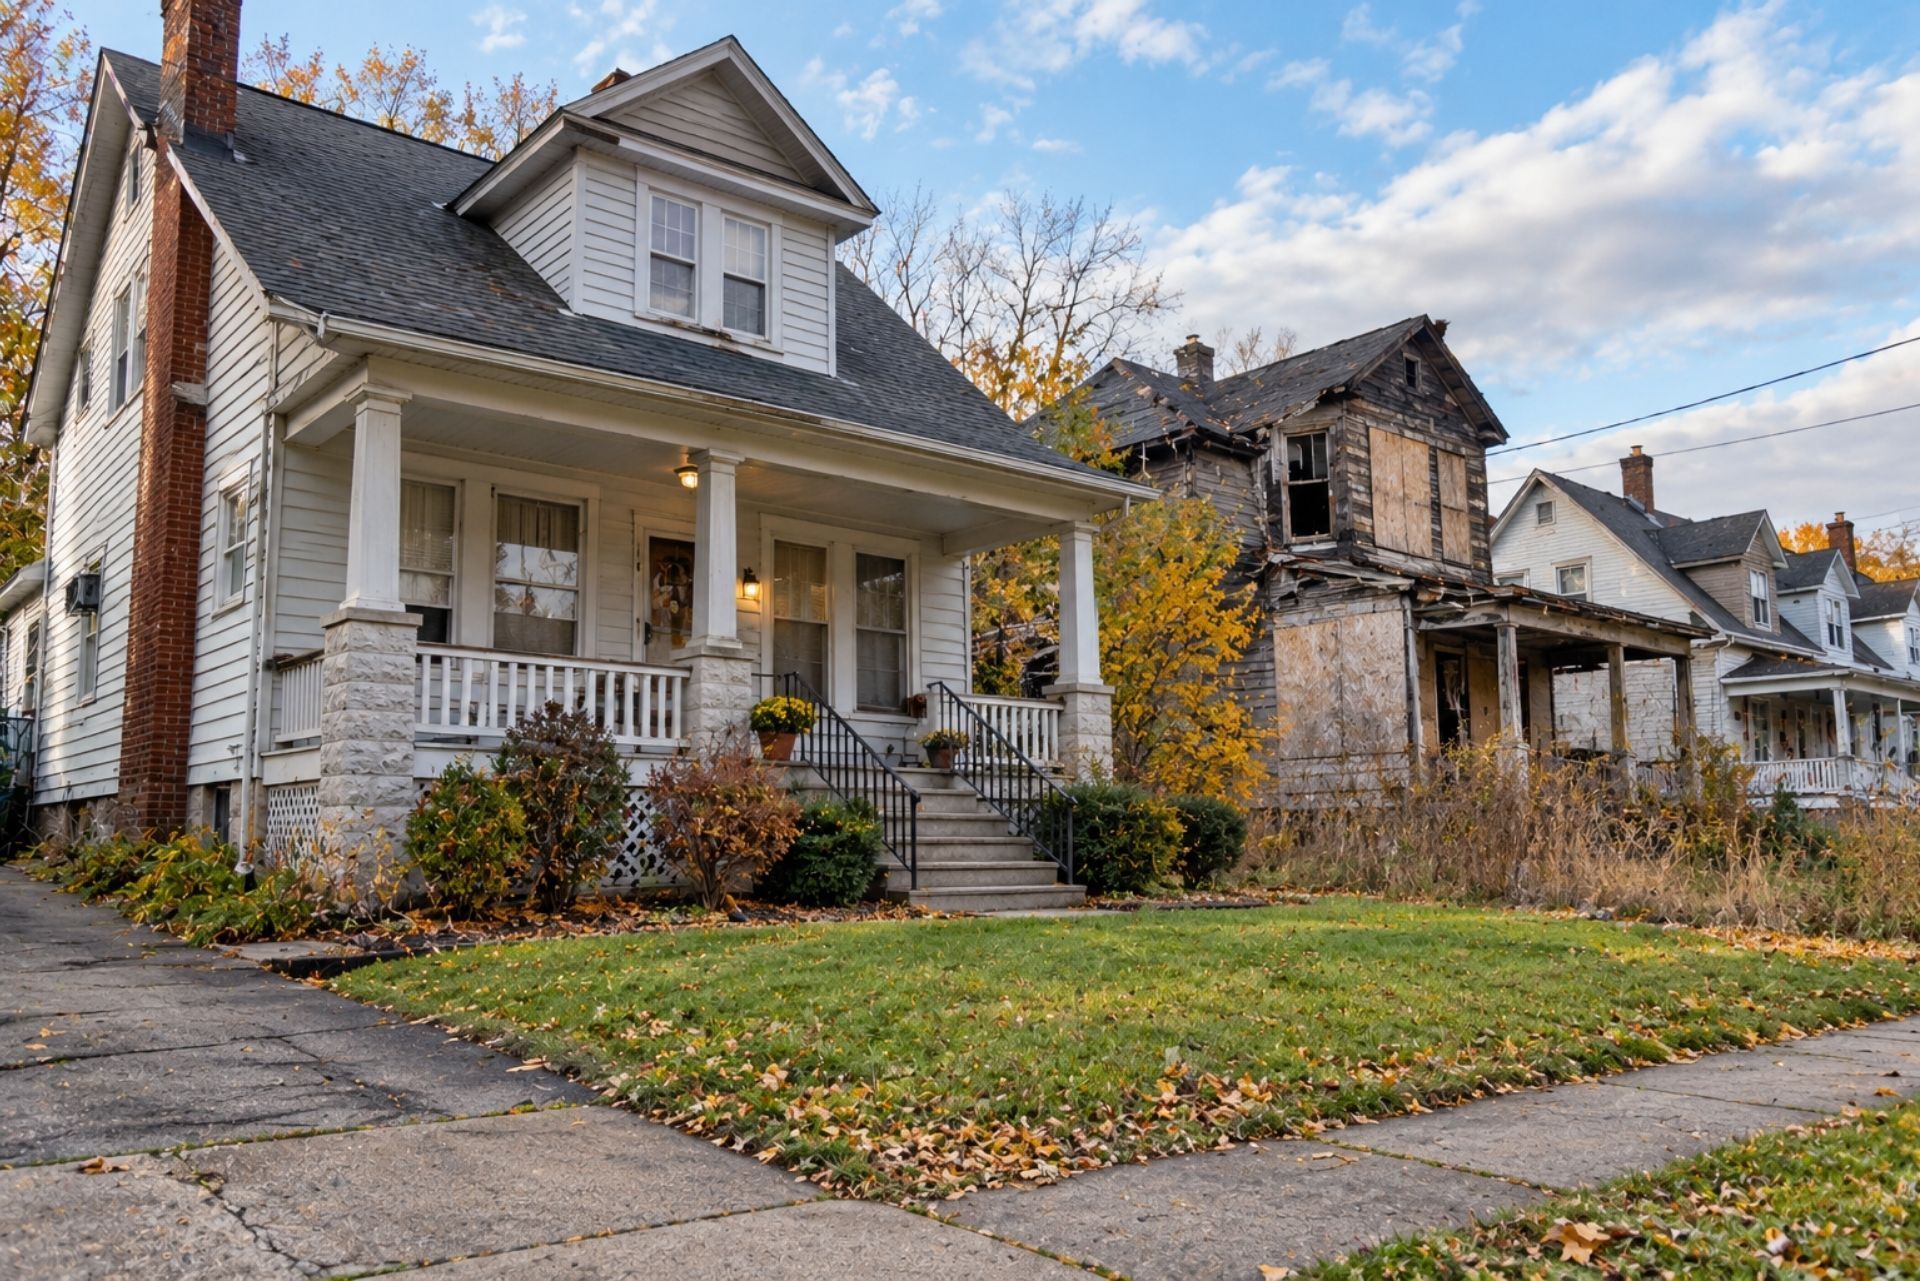
A vacant house next door can affect your coverage, mostly through added fire, vandalism, and liability exposure. Empty structures attract squatters, scrappers, and occasional arson, and fire spreads easily between closely spaced homes on narrow city lots. Underwriters know this, so some will look at the condition of the surrounding block when they evaluate a policy in urban Youngstown neighborhoods.
The picture has been improving. The Mahoning County Land Bank has impacted over 10,000 properties since its inception, working to clear blight and stabilize neighborhoods. Still, plenty of streets have at least one boarded-up house, and its presence can come up during an inspection or when a claims adjuster visits.
There are local rules aimed at the owners of those buildings. Owners of vacant or abandoned buildings are required by ordinance to carry property and liability insurance at least equal to fair market value (verify at publish). That helps if a neighboring vacant house catches fire and damages yours, since your insurer may pursue the owner's carrier, but you shouldn't count on recovery from an absentee owner.
Demolitions bring their own wrinkle. A September 2026 Ohio Court of Appeals decision clarified that policies generally exclude losses caused by government-ordered demolitions (verify at publish). That ruling concerns the demolished property itself, but it's a good reminder to photograph your own home's foundation, siding, and driveway before any nearby teardown, in case equipment or debris causes damage you need to claim against the contractor.
What you can do: report vacant structures to the city, keep your own exterior well lit, and make sure your liability limit is high enough. Many homeowners stay at the default $100,000 when $300,000 or $500,000 costs relatively little more.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Protecting Against Basement Flooding and Water Backup
If your basement floods because the sewer or a floor drain backs up, a standard policy almost certainly won't pay. Standard Ohio homeowners policies exclude water and sewer backups, and coverage has to be added as a separate endorsement. This is the gap that surprises Youngstown homeowners more than any other.
Older city infrastructure is part of the problem. Many neighborhoods rely on aging combined sewer lines, and a heavy summer storm can push water back up through basement drains within an hour. Add old clay lateral lines prone to root intrusion and sump pumps that fail during power outages, and the risk becomes very real.
The costs aren't small. The average sewer backup claim in 2026 runs roughly $20,000, and restoring a finished basement can exceed $62,000. That includes pumping, drywall removal, mold prevention, flooring, and replacing whatever was stored down there: furnaces, water heaters, washers, holiday decorations, and kids' old furniture.
A few points to check when you add the endorsement:
- The limit. Many endorsements start at $5,000 or $10,000. If your basement is finished, that won't come close.
- What triggers coverage. Some versions cover sump pump failure; others only cover backup from sewers or drains.
- Flood is separate. Backup endorsements don't cover surface water or rising rivers. That requires a flood policy.
On the prevention side, a backwater valve, a battery backup sump pump, and periodic camera inspection of your sewer lateral can each cut the odds of a claim. Some carriers also ask about these items during quoting.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Coverage for Theft and Vandalism Claims
Theft and vandalism are covered under standard homeowners policies, but the limits and sublimits matter more than most people realize. Denser neighborhoods can see more property crime, and in older urban areas, garages, porches, and detached sheds are frequent targets. Copper piping and air conditioner condensers draw scrappers, especially near vacant houses.
Personal property coverage usually sits at 50% to 70% of the dwelling limit. That sounds generous until you look at the sublimits for specific categories. Jewelry, firearms, cash, and collectibles often carry caps of a few thousand dollars unless you schedule them separately.
Here's a scenario that comes up often. A homeowner's detached garage is broken into, and the thief takes power tools, a snowblower, two bikes, and a toolbox. The total runs close to $7,000. If the policy pays actual cash value for contents, depreciation can shrink that payout dramatically, so a five-year-old snowblower might be valued at a fraction of what a new one costs. Replacement cost on contents fixes that.
Vandalism has its own catch: if a home sits vacant for more than a set number of days (often 30 or 60), many policies stop covering vandalism entirely. That matters if you're between tenants, handling an estate, or spending a winter away. Talk to your agent before the house sits empty, not after.
Practical steps:
- Take a video walk-through of every room and the garage once a year.
- Schedule high-value items like rings, guns, and instruments.
- Ask for replacement cost on personal property.
- Consider exterior cameras and motion lighting, which can help with both deterrence and proof.
A good agent reviews these limits with you so your belongings are protected inside the house and out in the yard.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Home
A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.
Understanding Replacement Cost vs Market Value
Insure your Youngstown home for what it would cost to rebuild, not what it would sell for. In this market, the two numbers can be far apart. Analysts describe a significant valuation gap in markets like Youngstown, where reconstruction costs often far exceed what the house would fetch on the open market.
The reason is straightforward. Market value reflects demand, location, and the condition of the neighborhood. Replacement cost reflects lumber, roofing, electrical, plumbing, permits, debris removal, and labor. As one local explanation puts it, "Lumber, copper, and skilled labor don't cost less in Youngstown just because home prices do."
The gap can be dramatic. One example shows a home with a market value of $63,300 that could cost more than $250,000 to rebuild with modern materials. Homeowners who insure based on market value can face a shortfall of $100,000 or more after a total loss. That's the difference between rebuilding and walking away with a check that won't cover a foundation and framing.
Older homes add one more layer. Plaster walls, hardwood trim, and slate roofs cost more to replicate. And building codes have changed since 1940, so a rebuild must meet current electrical and structural standards. Ordinance or law coverage pays for those code upgrades, and many base policies include only a small amount. Ask about raising it.
Youngstown Property Valuation Comparison
| Measure | What It Reflects | Typical Use | Risk If Used for Insurance |
|---|---|---|---|
| Market value | Sale price, location, demand | Buying, selling, taxes | Underinsured after a total loss |
| Replacement cost | Labor and materials to rebuild | Dwelling coverage limit | Higher premium, full rebuild |
| Actual cash value | Replacement cost minus depreciation | Some contents or roofs | Payout shrinks with age |
| Extended replacement | Replacement cost plus 20%-50% buffer | Protection from cost spikes | Small added premium |
If your dwelling limit is close to your purchase price on an older home, that's a red flag worth checking now.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Local Insurance Support in New Springfield and Zelienople
Local, independent help makes the difference with older homes, because the right carrier for a 1928 colonial isn't always the right one for a 1995 ranch. MVP Insurance was founded in 2008 by Josh Medure and David Varrati, and the agency works for clients rather than any single insurance company. That independence means MVP can shop several carriers at once and compare how each treats wiring updates, backup endorsements, and replacement cost.
The Ohio office sits at 13823 Grant St, New Springfield, OH 44443, a short drive from Youngstown. You can reach the team there at (330) 707-9055. The Pennsylvania office is at 108 E Grandview Ave, Zelienople, PA 16063, and can be reached at (724) 453-1122, which helps families and businesses with property in both states.
Clients also get 24/7 claims support, so a basement backup at 2 a.m. doesn't mean waiting until Monday to start the process. The agency uses modern tools and apps to keep policy documents and ID cards easy to reach, which saves time when you need proof of coverage for a lender or contractor.
Many Youngstown households bundle home and auto for a lower combined premium. If you're reviewing both, the
Youngstown car insurance pagecovers local auto considerations. When you're ready to compare options for your house,
start your quoteand MVP will do the legwork of comparing carriers for you. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Youngstown Home Insurance Frequently Asked Questions
Can I get home insurance in Youngstown if my house has knob-and-tube wiring? It's harder. Many major insurers decline homes with active knob-and-tube or require removal shortly after closing, so getting an electrician's inspection and replacing it opens up far more options.
Does homeowners insurance cover a flooded basement in Ohio? Not if the water came from a sewer or drain backup, unless you added a water backup endorsement. Surface flooding needs a separate flood policy.
Should I insure my house for what I paid for it? Usually no. In Youngstown, rebuilding often costs much more than the sale price, so your dwelling limit should match replacement cost.
Will a vacant house next door raise my insurance rates? It can affect underwriting in some cases, since vacant structures raise fire and vandalism risk. Comparing several carriers helps, because each weighs neighborhood conditions differently.
Is theft from my detached garage covered? Generally yes, under personal property coverage, but sublimits and depreciation can reduce the payout. Ask for replacement cost on contents.
What happens to my coverage if my house sits empty? Many policies limit vandalism and other coverage after 30 to 60 days of vacancy. Tell your agent before the home goes unoccupied so you can arrange the right policy.
Older Youngstown homes are worth protecting properly, and the fixes are rarely complicated: update the wiring, add backup coverage, check your contents limits, and insure for the true cost to rebuild. A short review today can keep one bad night from turning into a financial setback that lasts for years.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.