

Owner, MVP Insurance
Pittsburgh drivers need a policy that meets Pennsylvania's legal minimums, but the minimums alone rarely cover what this city throws at a car. Tunnel backups, steep icy grades, tight street parking, and a meaningful share of uninsured motorists all call for stronger liability limits, uninsured motorist protection, and a careful tort choice.
The rest of this guide covers why. If you've ever merged out of the Fort Pitt Tunnel with three seconds to pick a lane, or come back to your car on a South Side side street to find a mirror hanging by its wires, you already understand that driving here is its own skill. Insurance for Pittsburgh drivers should reflect that, and it often doesn't. Plenty of people buy a policy online, accept the default limits, check "limited tort" because it's a little less expensive, and never think about it again until a claim exposes the gaps. What follows walks through the local risks one by one: the tunnels and bridges, the hills and landslides, winter crashes, rowhouse parking, uninsured drivers, and the tort decision that confuses almost everyone. The goal is simple: help you build a policy that actually fits the way you drive in Allegheny County.
Navigating Pittsburgh PA Car Insurance Requirements
Every Pittsburgh driver must carry at least Pennsylvania's minimum auto coverage: bodily injury liability, property damage liability, and first-party medical benefits. That's the legal floor. The smarter move is treating those minimums as a starting point and adding coverage for the hazards that make city driving here different, like tunnel traffic, hill crashes, and winter ice.
The state minimums were written decades ago, and they haven't kept pace with what a hospital stay or a late-model SUV repair costs today. That matters more than ever, because auto injury claim payments are rising sharplyas of mid-2026, outpacing medical inflation thanks to higher medical bills and more attorney involvement. If you cause a multi-car pileup at the Liberty Tunnel portal with bare-minimum limits, anything above those limits can come after your savings and wages.
Pricing has been bumpy. The state reported in April 2026 that the market is stabilizing, with recent filings averaging a 0.5% rate decrease. Even so, Pennsylvania drivers now pay an average of $1,930 per year for full coverage, up 2.3% since January. Regulators have pushed back hard, too, blocking $85.3 million in proposed personal auto increasesin the first half of 2025 alone.
MVP Insurance was founded in 2008 by Josh Medure and David Varrati as an independent agency, which means we compare policies from multiple carriers instead of selling one company's product. For a broader look at statewide rules, see our page on Pennsylvania car insurance.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
The Risks of Tunnels, Bridges and Hill Driving
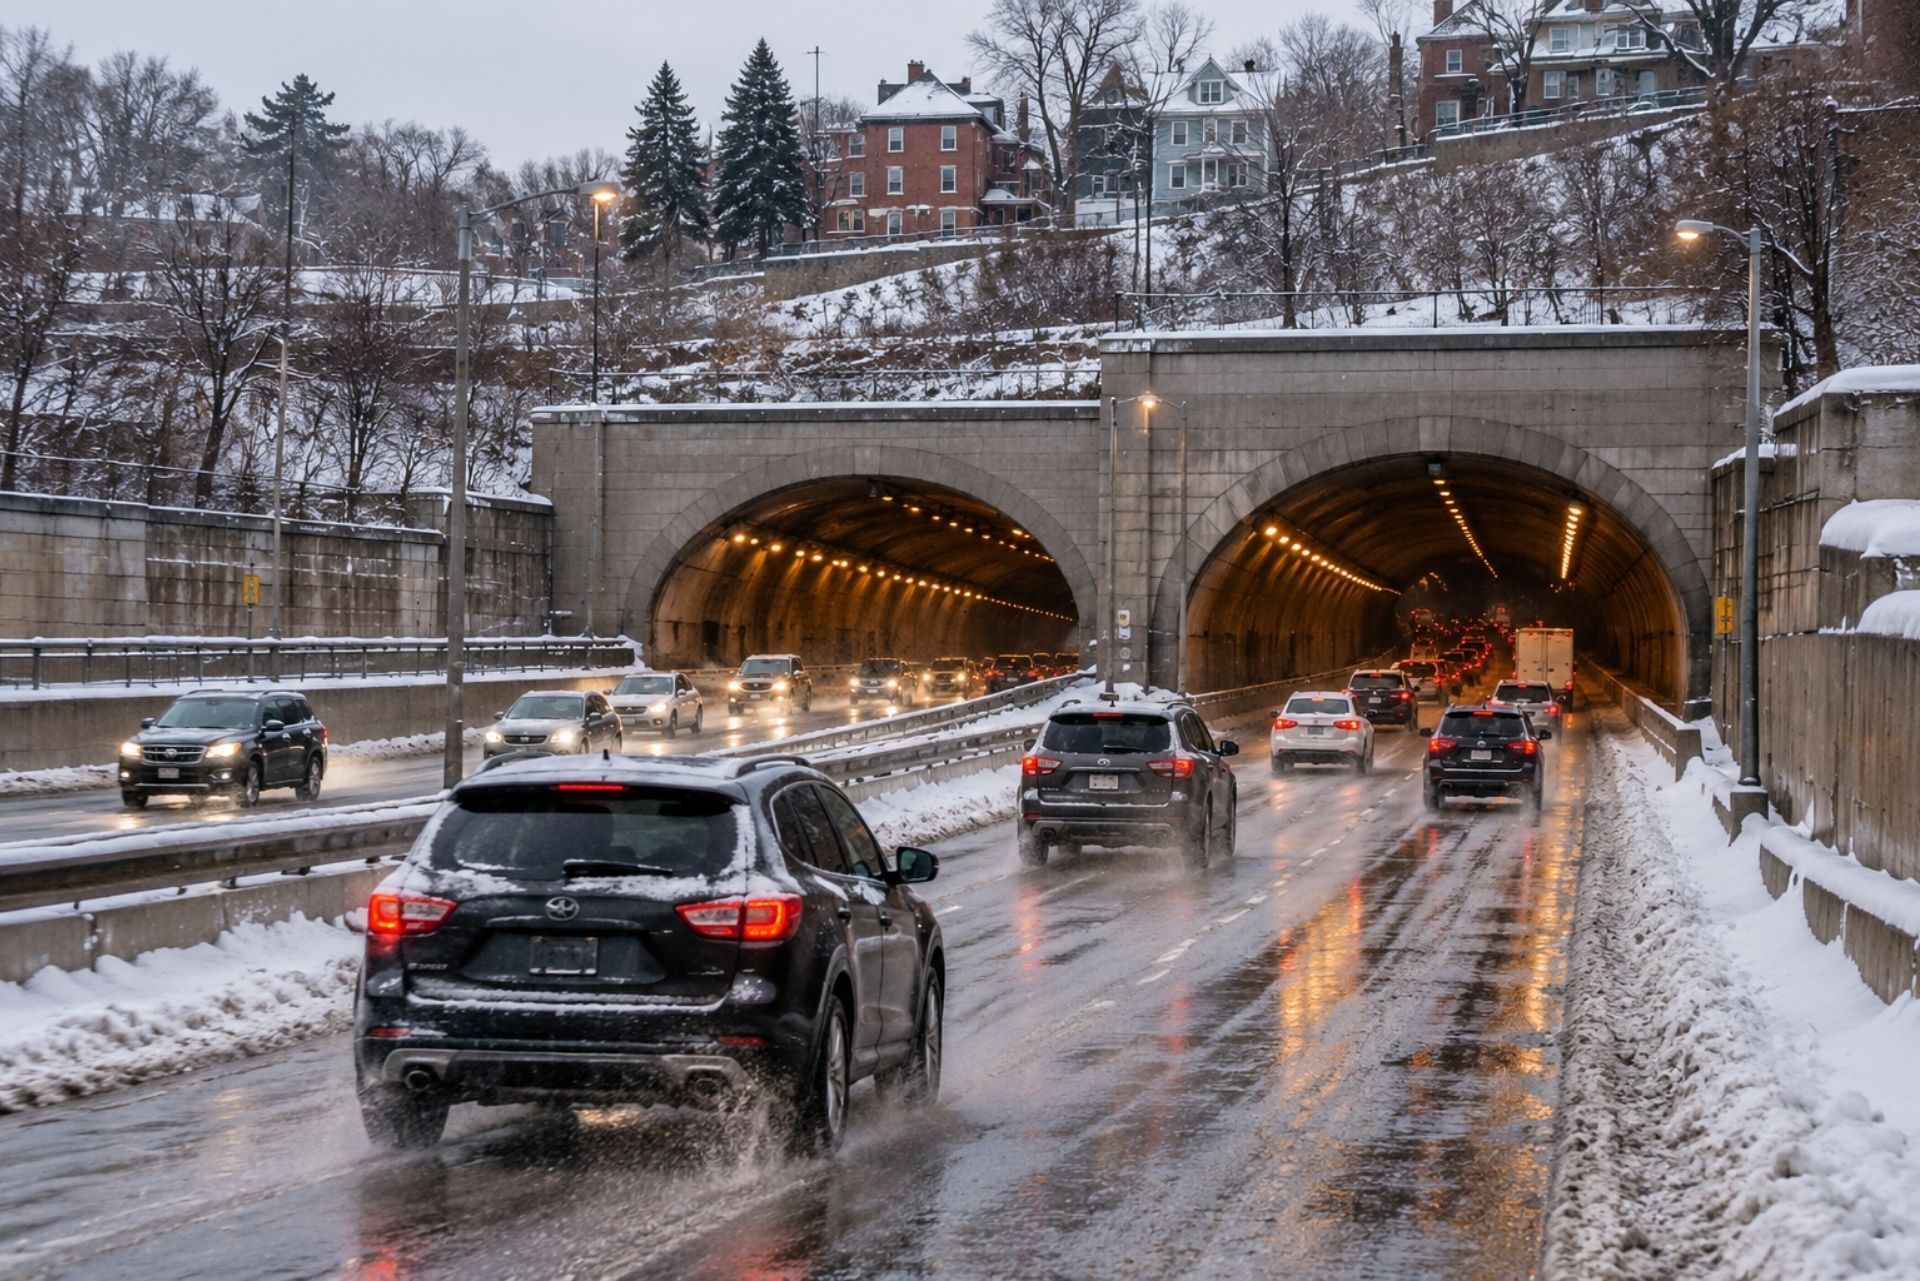
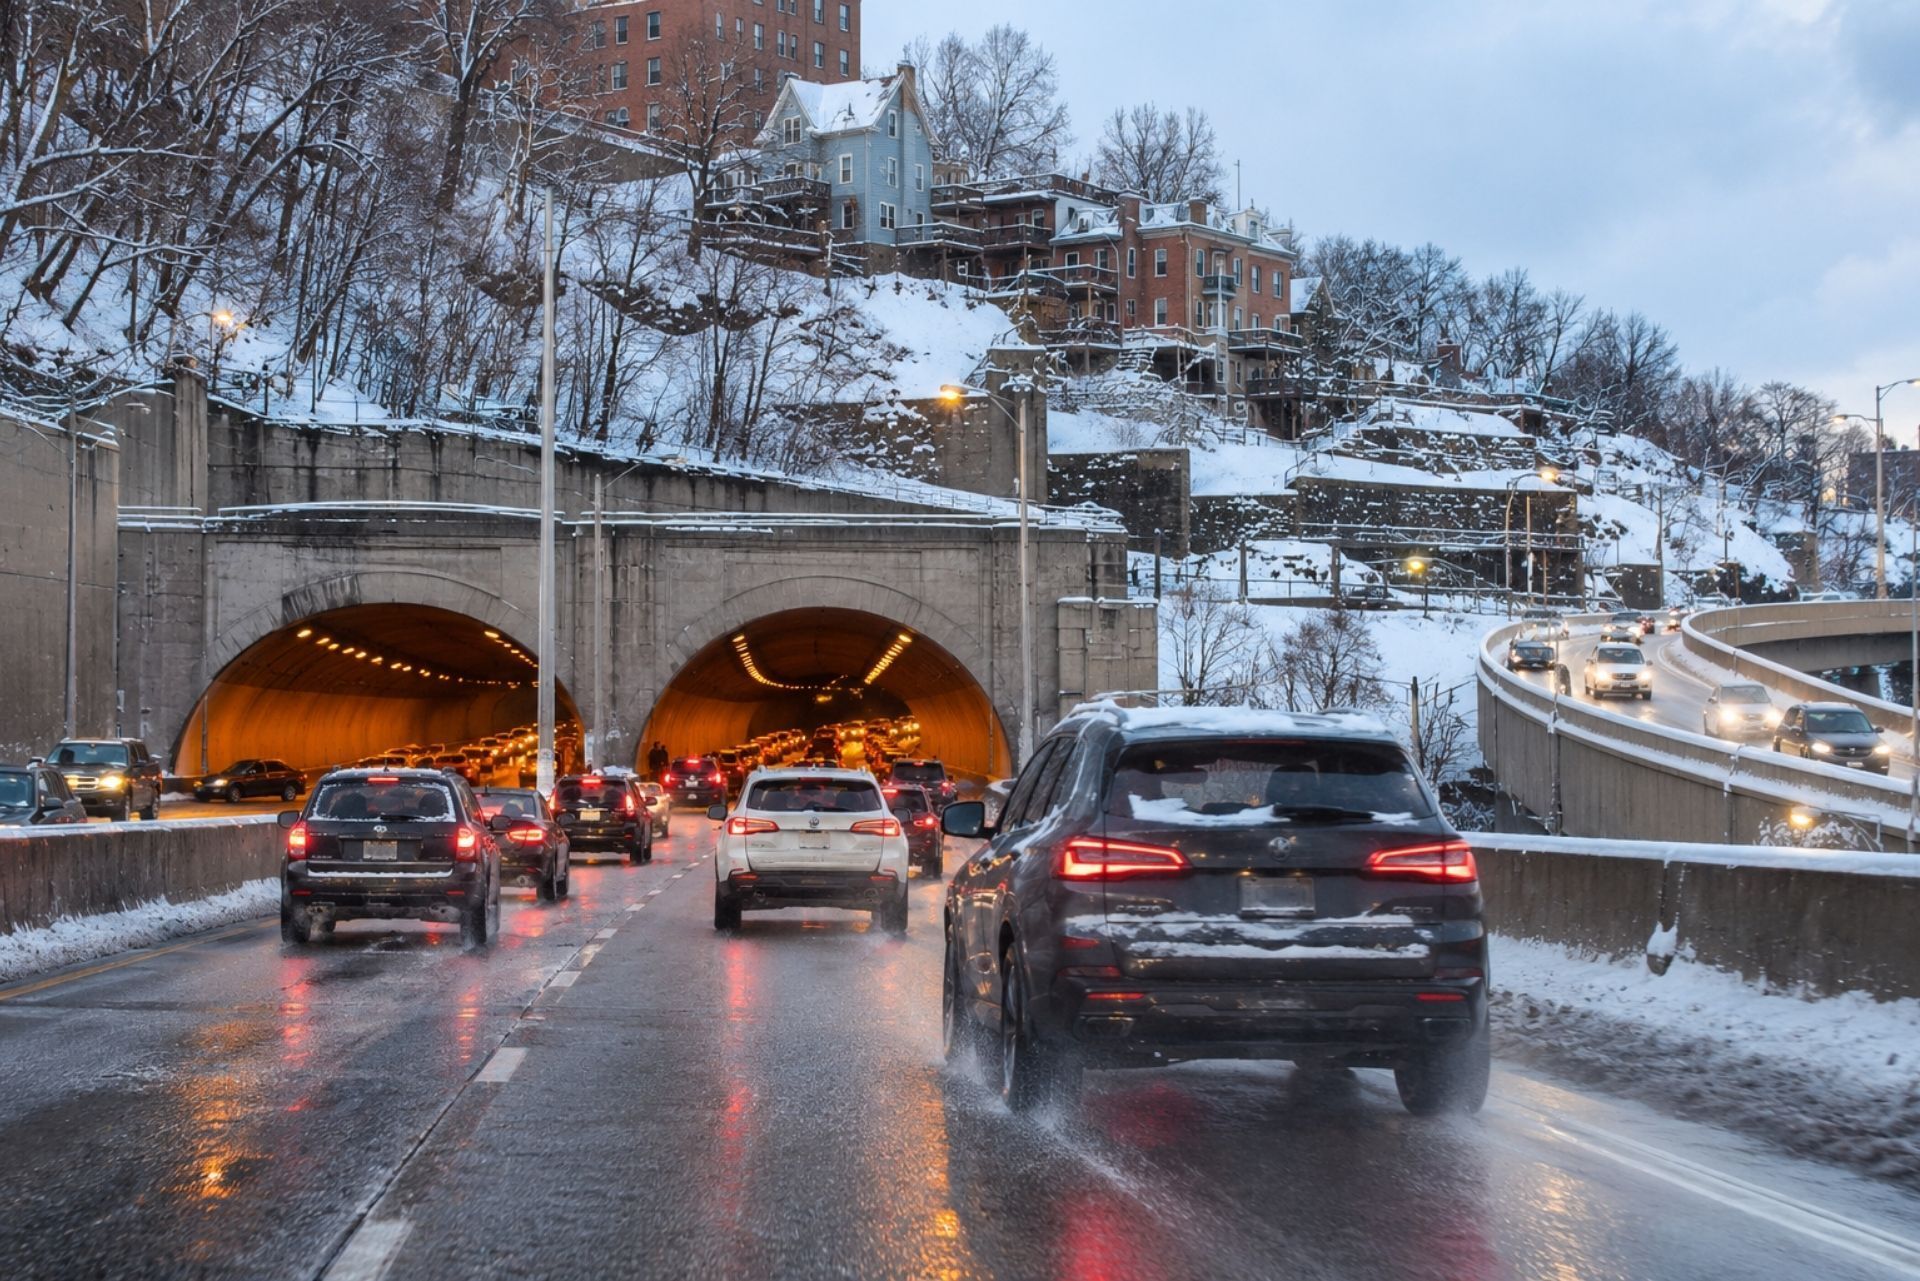
Pittsburgh's tunnels and bridges create a specific crash pattern: sudden braking, last-second lane changes, and rear-end or sideswipe collisions in tight spaces. Collision coverage and solid liability limits handle most of these claims, and they come up far more often here than in flatter cities.
The Fort Pitt Tunnel is the classic example. Inbound drivers emerge onto the Fort Pitt Bridge with a famous view and almost no time to cross several lanes toward their exit. Visitors hesitate, locals dart, and the result is a steady stream of low-speed sideswipes and fender benders. The Liberty Tunnel has its own issues, including heavy commuter volume from the South Hills and the merge chaos at either end where traffic funnels in from multiple directions.
Bridges add another layer. Many of the city's spans dump drivers onto ramps, one-way streets, or immediate turns, so you get frequent lane changes stacked close together. Here's what that tends to mean for claims:
- Rear-end collisions at tunnel entrances when traffic stops abruptly
- Sideswipes during forced merges on bridge approaches
- Disputed fault when two cars change lanes at the same moment
- Multi-vehicle claims in tunnel backups, which can exhaust low property damage limits fast
Location matters for severe crashes too. Allegheny County recorded 74 traffic fatalities in 2024, and state routes accounted for nearly half of non-interstate deaths while making up only 12% of the city network.
Landslides and Terrain Hazards in Allegheny County
Landslides are a known coverage gap for Allegheny County residents, and most people don't realize it until a hillside lets go. The hills that give the city its character also shed soil and rock onto roads, driveways, and parked cars, especially after heavy rain or freeze-thaw cycles.
On the auto side, damage from falling rocks or debris landing on your car is generally handled under comprehensive coverage, so a policy with liability only leaves you paying out of pocket. Driving into a slide that's already on the road may be treated as a collision claim instead, which changes your deductible. On the home side, earth movement is commonly excluded from standard homeowners policies, which is where the real gap shows up. Coverage terms vary by carrier and change over time, so verify the specific landslide and earth movement language in your own policies at the time you buy or renew rather than assuming either way.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Winter Accidents and Seasonal Road Safety
Winter is when Pittsburgh's geography turns against drivers. Steep grades plus ice equals more crashes in Western PA from roughly December through March, and most of them are the kind collision coverage exists to pay for: sliding into a parked car, a guardrail, or the vehicle stopped at the bottom of the hill.
Think about Canton Avenue in Beechview, or any of the dozens of residential streets in Mt. Washington, Polish Hill, or Greenfield that tilt steeply enough to make a summer walk tiring. Add a thin glaze of ice and a car that started rolling at three miles per hour can't stop. We see a familiar mix of winter claims: a driver slides through a stop sign at the bottom of a grade, a parked car gets hit by someone who lost traction above it, or a car fishtails on a bridge deck that froze before the surrounding road did.
A few practical points matter here. Your own car's damage in a single-car slide is a collision claim, so if you dropped collision on an older vehicle to save money, that slide into a utility pole is yours to pay. If someone slides into your legally parked car, their liability coverage should pay, but only if they have it, which ties directly into uninsured motorist protection. Deductibles also deserve a hard look: a $1,000 deductible feels fine in July and painful in February when you're facing your second winter fender bender.
The good news is that some city streets are getting safer. Pittsburgh reported a 17% drop in total crashes on city-owned streets in 2024 after Vision Zero improvements. Ice, though, doesn't read traffic studies.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Limits and minimums can change, so confirm current figures before you buy. Our honest view: the premium difference is often modest compared with what you give up. A soft-tissue injury from a Route 8 rear-end crash can mean months of pain that limited tort won't compensate.
The Role of Umbrella and Life Insurance in a Comprehensive Plan

Parking on City Streets and Rowhouse Neighborhoods
If you live in a dense rowhouse neighborhood, street parking is a daily risk to your car's sides and mirrors. Lawrenceville, Bloomfield, the South Side Flats, and Polish Hill all have narrow streets lined bumper to bumper on both sides, and there's often no driveway or garage option at all.
The typical damage is minor but frequent: a delivery truck clips a side mirror, someone scrapes your door while squeezing past, or a driver parallel parking taps your bumper and leaves. Hit-and-runs on parked cars are common, and that's where coverage choices start to matter. Without a note on the windshield or a camera, there's no other driver's insurance to bill.
Here's how those claims usually play out:
- Someone hits your parked car and leaves a note: Their property damage liability pays your repair.
- Hit-and-run with no identified driver: Your own collision coverage typically applies, minus your deductible.
- Vandalism, a keyed door, or a smashed window: Comprehensive coverage generally handles this.
- Mirror damage under your deductible: You pay it yourself, which is why deductible choice matters for street parkers.
One common mistake: people with older cars drop collision and comprehensive to cut costs, then park on a tight Bloomfield street every night. For a car worth a few thousand dollars, that can be a reasonable trade. For a newer vehicle with a loan, it's usually not allowed by the lender anyway. Run the numbers on your car's actual value versus what the coverage costs before deciding.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Protecting Against Uninsured Driver Exposure
Uninsured and Underinsured Motorist coverage is one of the most important protections a Pittsburgh driver can carry. It pays for your injuries when the driver who hit you has no insurance or not enough of it, and in a city with heavy traffic and plenty of minimum-limit policies, that scenario is common.
The numbers make the case. Roughly 11.0% of Pennsylvania motorists are uninsured, placing the state 36th nationally for uninsurance rates as of 2025. That's about one in nine drivers. Then layer in the underinsured problem: a driver carrying only the state minimum might technically be insured, but their liability limit could be used up by a single ER visit and a few weeks of physical therapy.
Pennsylvania lets drivers reject this coverage in writing, and many do it to shave a bit off the premium. That's a mistake we see repeatedly. Picture getting rear-ended on the Parkway East by someone with no policy: your health insurance may cover some medical bills, but lost wages, ongoing pain, and long-term treatment can go uncompensated without UM coverage.
A couple of nuances are worth asking about:
- Stacking: Pennsylvania allows you to stack UM/UIM limits across multiple vehicles on your policy, multiplying your protection. Rejecting stacking lowers your premium but also your coverage.
- Matching limits: A good rule is setting UM/UIM limits equal to your liability limits, so you protect yourself as well as you protect others.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Choosing Between Limited or Full Tort Coverage
The tort choice decides whether you can sue for pain and suffering after a crash. Full Tort keeps that right in every case. Limited Tort lowers your premium but restricts you to suing for pain and suffering only when your injury meets the state's "serious injury" threshold, with some exceptions.
Both options let you recover out-of-pocket losses like medical bills and lost wages. The difference is non-economic damages: the pain, the months of limping, the missed softball season, the anxiety every time you drive through a tunnel again. Under Limited Tort, most soft-tissue injuries such as whiplash or back strain won't clear the serious injury bar, so that compensation simply isn't available to you.
Limited Tort typically saves policyholders between 12% and 15% on premiums, which averages out to about $120 to $180 per year. That's real money for a household budget. But consider what you'd be giving up: a single moderate injury claim from a winter rear-end collision could be worth far more than a decade of those savings.
Our honest take: Full Tort is the stronger choice for most Pittsburgh families, especially those with kids who drive, long daily commutes, or frequent trips through the tunnels. Limited Tort can make sense if your budget is truly tight and you're comfortable accepting that risk. Just make the choice deliberately, not because it was the default box on a form.
Coverage Limits Comparison Table
| Coverage | State Minimum Approach | Stronger Pittsburgh Setup | Why It Matters Here |
|---|---|---|---|
| Bodily Injury Liability | Minimum required | Higher limits | Multi-car tunnel crashes |
| Property Damage Liability | Minimum required | Higher limits | Newer cars cost more to fix |
| Medical Benefits | Minimum required | Higher limit | Rising injury claim costs |
| Uninsured/Underinsured | Can reject in writing | Match liability, stacked | About 1 in 9 drivers uninsured |
| Collision | Not required | Included | Ice slides, hit-and-runs |
| Comprehensive | Not required | Included | Falling rock, vandalism |
| Tort Option | Limited saves money | Full keeps right to sue | Soft-tissue injuries |
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Bundling with Pittsburgh Homeowners Insurance
Bundling auto and home coverage with the same carrier usually lowers your combined premium and simplifies claims, since one company handles both policies. For Pittsburgh homeowners, it's also a chance to review gaps on both sides at once, and the house side here has some local quirks.
The biggest one is water. Pittsburgh's older neighborhoods run on combined sewer systems, which carry stormwater and sewage in the same pipes. During heavy rains, combined sewer overflows can push water back up through basement floor drains, and that basement backup is a specific, recurring concern for homeowners across the city. Standard homeowners policies often exclude sewer and drain backup unless you add an endorsement, so a finished basement in Brookline or Morningside can turn into a five-figure loss with no coverage.
Landslides connect the two policies as well. A hillside slip that damages your car may fall under comprehensive auto coverage, while the same slide cracking your foundation is often excluded from homeowners coverage. Looking at both together helps you see where earth movement protection exists and where it doesn't.
Practical bundling benefits include:
- One renewal dateto track instead of two
- Potential multi-policy savingsdepending on the carrier
- A single agentwho knows your full exposure
Our page on Pittsburgh homeowners insurance covers water backup, landslides, and older-home issues in more detail.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Frequently Asked Questions About Pittsburgh Auto Policies
How much is car insurance in Pittsburgh? It depends on your car, driving record, ZIP code, and coverage choices. Statewide, full coverage now averages about $1,930 a year, and city drivers can land above or below that based on their situation.
Is full tort worth it in Pennsylvania? For most drivers, yes. It costs roughly $120 to $180 more per year on average, and it keeps your right to sue for pain and suffering after almost any injury.
Does car insurance cover a rock falling on my car? Usually yes, if you carry comprehensive coverage. Liability-only policies won't pay for damage to your own car from falling rocks or debris.
Do I need uninsured motorist coverage in PA? It isn't mandatory since you can reject it in writing, but it's strongly recommended. About 11% of Pennsylvania drivers have no insurance at all.
Who pays if someone hits my parked car and drives off? Your own collision coverage typically pays, minus your deductible. Without collision, you'd likely pay for the repair yourself.
Does homeowners insurance cover basement sewer backup?
Often not by default. You usually need a separate water backup endorsement, which matters a lot in Pittsburgh neighborhoods with combined sewers.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Contact MVP Insurance in Zelienople or New Springfield
Pittsburgh driving asks more of a car insurance policy than the state minimum delivers. The tunnels and bridges create crowded, fault-disputed crashes. The hills turn icy every winter, and the hillsides themselves sometimes come down. Rowhouse parking means scraped doors and missing mirrors, roughly one in nine drivers carries no insurance, and the tort box you check today decides what you can recover after an injury tomorrow. None of these are reasons to panic. They're reasons to set limits on purpose.
As an independent agency, MVP Insurance shops multiple carriers for you, so you can compare Full and Limited Tort pricing, UM stacking, and deductible options side by side instead of guessing. If you're ready to see how your current policy stacks up, start your quote and we'll handle the comparison legwork. Claims support is available 24/7 when you need it.
MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293. You can reach us at either office:
- Zelienople, PA: 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122
- New Springfield, OH: 13823 Grant St, New Springfield, OH 44443, (330) 707-9055
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.