


Pittsburgh PA Homeowners Insurance

Owner, MVP Insurance

A standard Pittsburgh homeowners policy leaves several local risks uncovered. Landslides, sinking ground over old mines, and basement sewer backups are typically excluded unless you add specific endorsements or separate coverage. Older rowhouses also need limits based on true rebuild cost, not what the house would sell for. Each gap has a fix, but none of them come automatically.


That surprises a lot of people. They buy a policy, pay the bill every year, and assume "homeowners insurance" means the house is protected. Then a hillside slips in Mount Washington, or a summer storm pushes sewage through a floor drain in Bloomfield. They learn the policy language was written for a flatter, newer, drier place than Western Pennsylvania.


Premiums aren't helping the mood either. Pennsylvania homeowners saw an inflation-adjusted 28.9% premium increase between 2021 and 2025, the highest in the Federal Reserve's Third District. When you're paying more, you want the coverage to fit how Pittsburgh actually breaks.

Understanding Pittsburgh PA Homeowners Insurance for Unique Risks

Pittsburgh PA homeowners insurance works best when you build it around the city's geography, not a national template. That usually means adding endorsements for sewer backup, buying separate mine subsidence coverage, and setting dwelling limits that reflect real reconstruction costs. Earth movement remains the hardest gap to close.


The core problem is the standard HO-3 form. It covers sudden, accidental damage like fire, wind, and burst pipes. It excludes the slow-moving or ground-based threats that hit this region most often. Rivers, steep slopes, a century of coal mining, and an aging combined sewer system all create losses that sit outside the basic contract.


The most common mistake we see is buying on price alone. Two quotes can look nearly identical on the declarations page and still differ completely on water backup limits or replacement cost terms. Before you compare premiums, compare the endorsements. Our Pennsylvania homeowners insurance pagewalks through the base coverages if you want a refresher on how the pieces fit together.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Landslide and Earth Movement Gaps on Hillside Lots

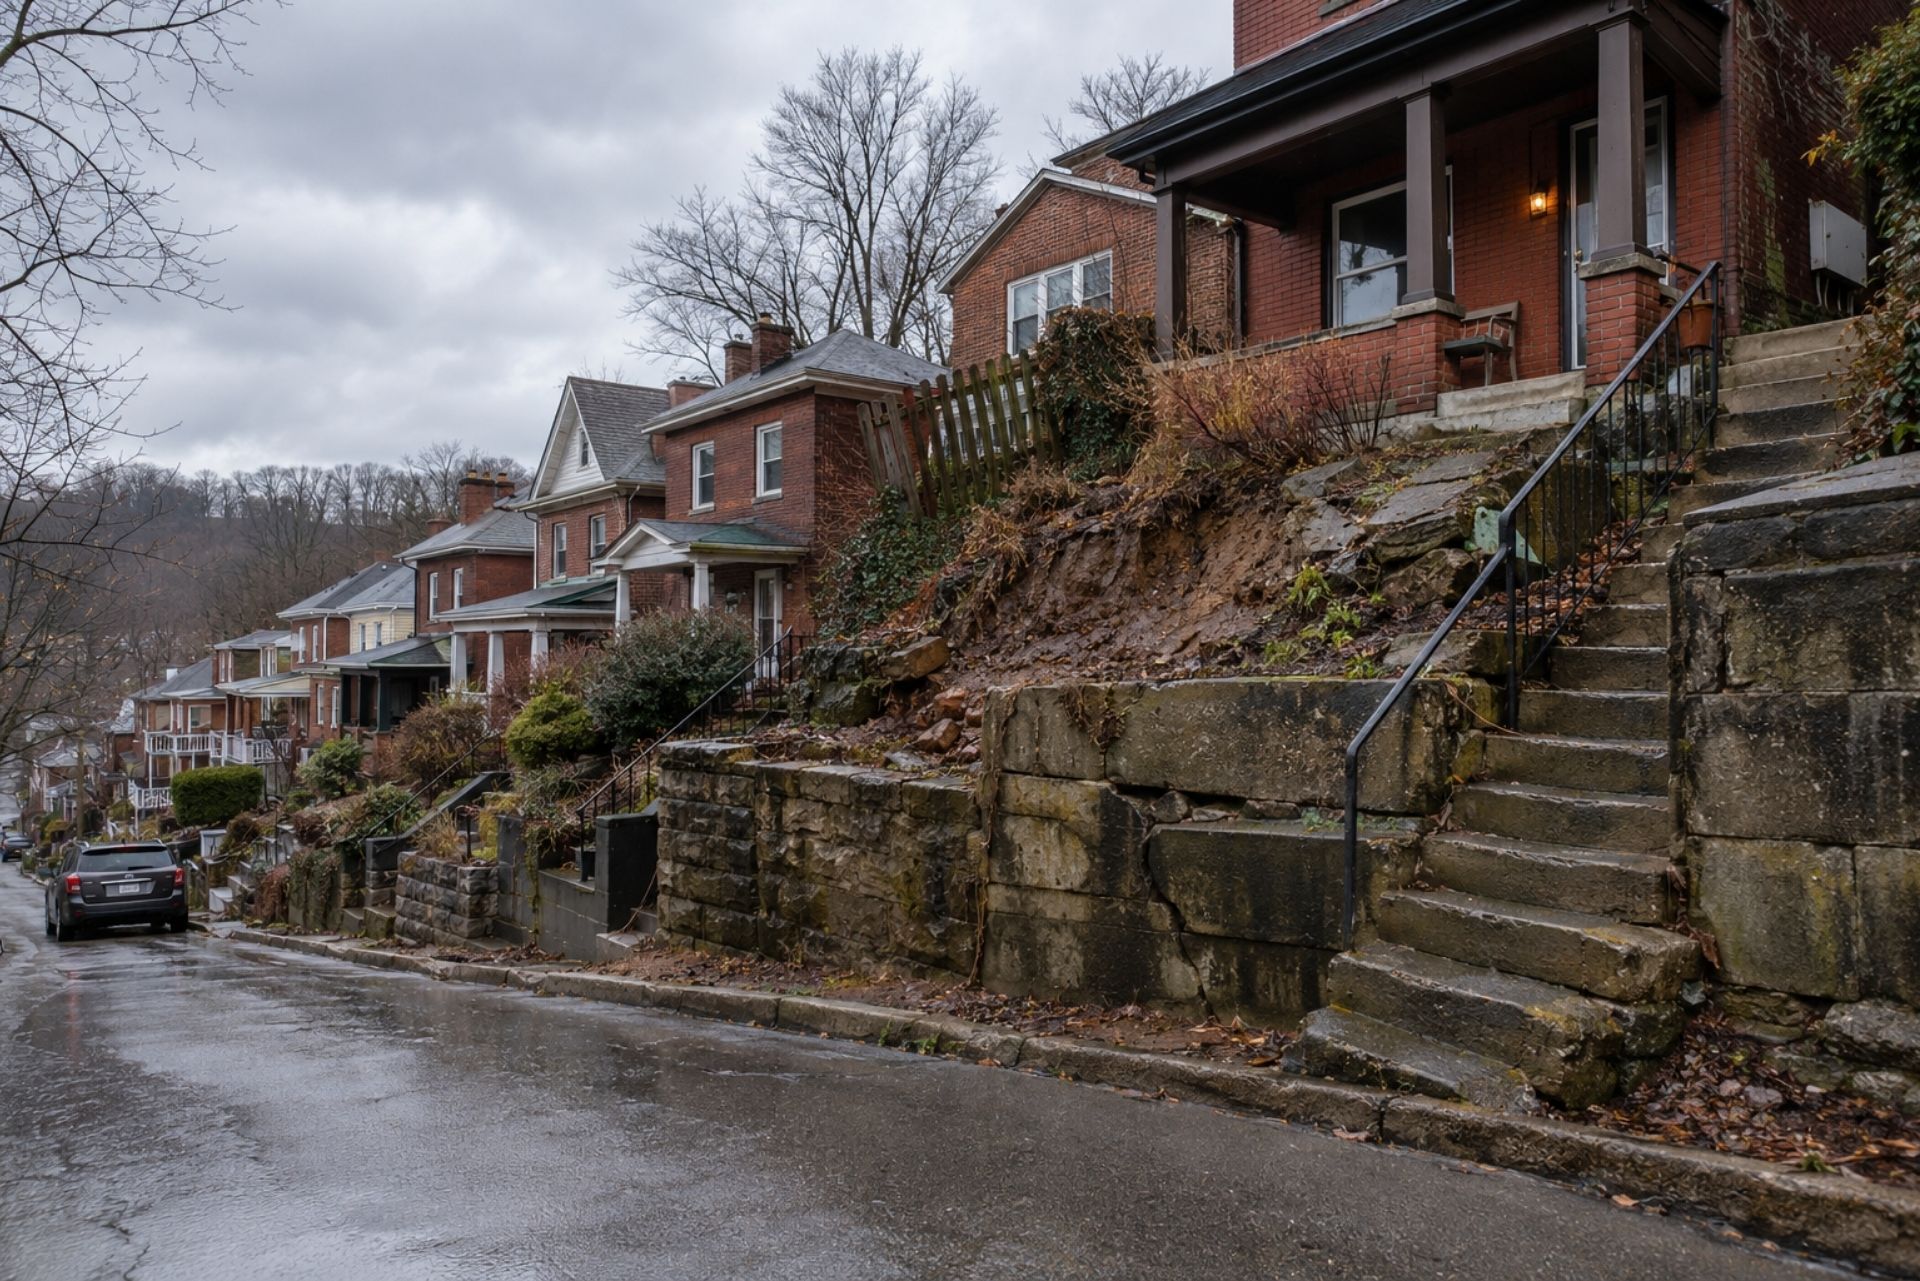
your house sits on a slope, assume your policy will not pay for a landslide. Standard HO-3 policies strictly exclude "earth movement", and in Allegheny County that exclusion lines up almost perfectly with one of the region's most frequent property disasters.


Think about homes on the steep terrain near the Fort Pitt and Liberty tunnels, or the hillsides above Route 51. Saturated soil, freeze-thaw cycles, and old fill dirt all contribute to slides. The private market has largely stepped back here: commercial insurers are "not stepping up" to cover landslide costs in Western Pennsylvania, leaving a multi-million dollar annual gap.


Retaining walls are their own trap. Most policies treat a leaning or failing wall as a maintenance problem under "earth movement" and "gradual deterioration" clauses, not a sudden loss. So inspect walls yearly, document drainage repairs, and fix bulges early.


For coverage, your options are limited:


  • Difference in Conditions (DIC) policies: specialty contracts that can pick up some excluded perils, when available
  • Earth movement endorsements: offered by some carriers, often with tight limits
  • Pending state program: the proposed Protecting Pennsylvanians from Landslides Act (H.B. 589) would create a state-run program offering up to $150,000 for natural landslides. Check its current status before relying on it.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Century-Old Rowhouses and Modern Rebuild Costs

Insure a rowhouse for what it costs to rebuild, not what it would sell for. In neighborhoods like Lawrenceville, the South Side, and Polish Hill, market value and replacement cost can be wildly different numbers, and the policy pays based on the dwelling limit you choose.


Rebuilding a 1910 brick rowhouse is a complicated job. Crews have to work around shared party walls, protect the neighbors' structures, and haul materials down narrow streets with no driveway access. Then the building inspector requires modern electrical, plumbing, egress, and fire separation that the original house never had. Construction pricing keeps climbing too: Pittsburgh's building cost index rose 7.9% year over year as of September 2026.


Standard Pittsburgh construction runs $200 to $250 per square foot in 2026, while complex hillside sites can reach $450. A 1,600-square-foot rowhouse on a tough lot could cost far more to replace than its last sale price suggests.


Ask about extended or guaranteed replacement cost, and add ordinance or law coverage. That endorsement pays for code upgrades the base policy won't touch, which is exactly where older homes get squeezed after a fire.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Sewer Backup During Heavy Rain and Combined Overflows

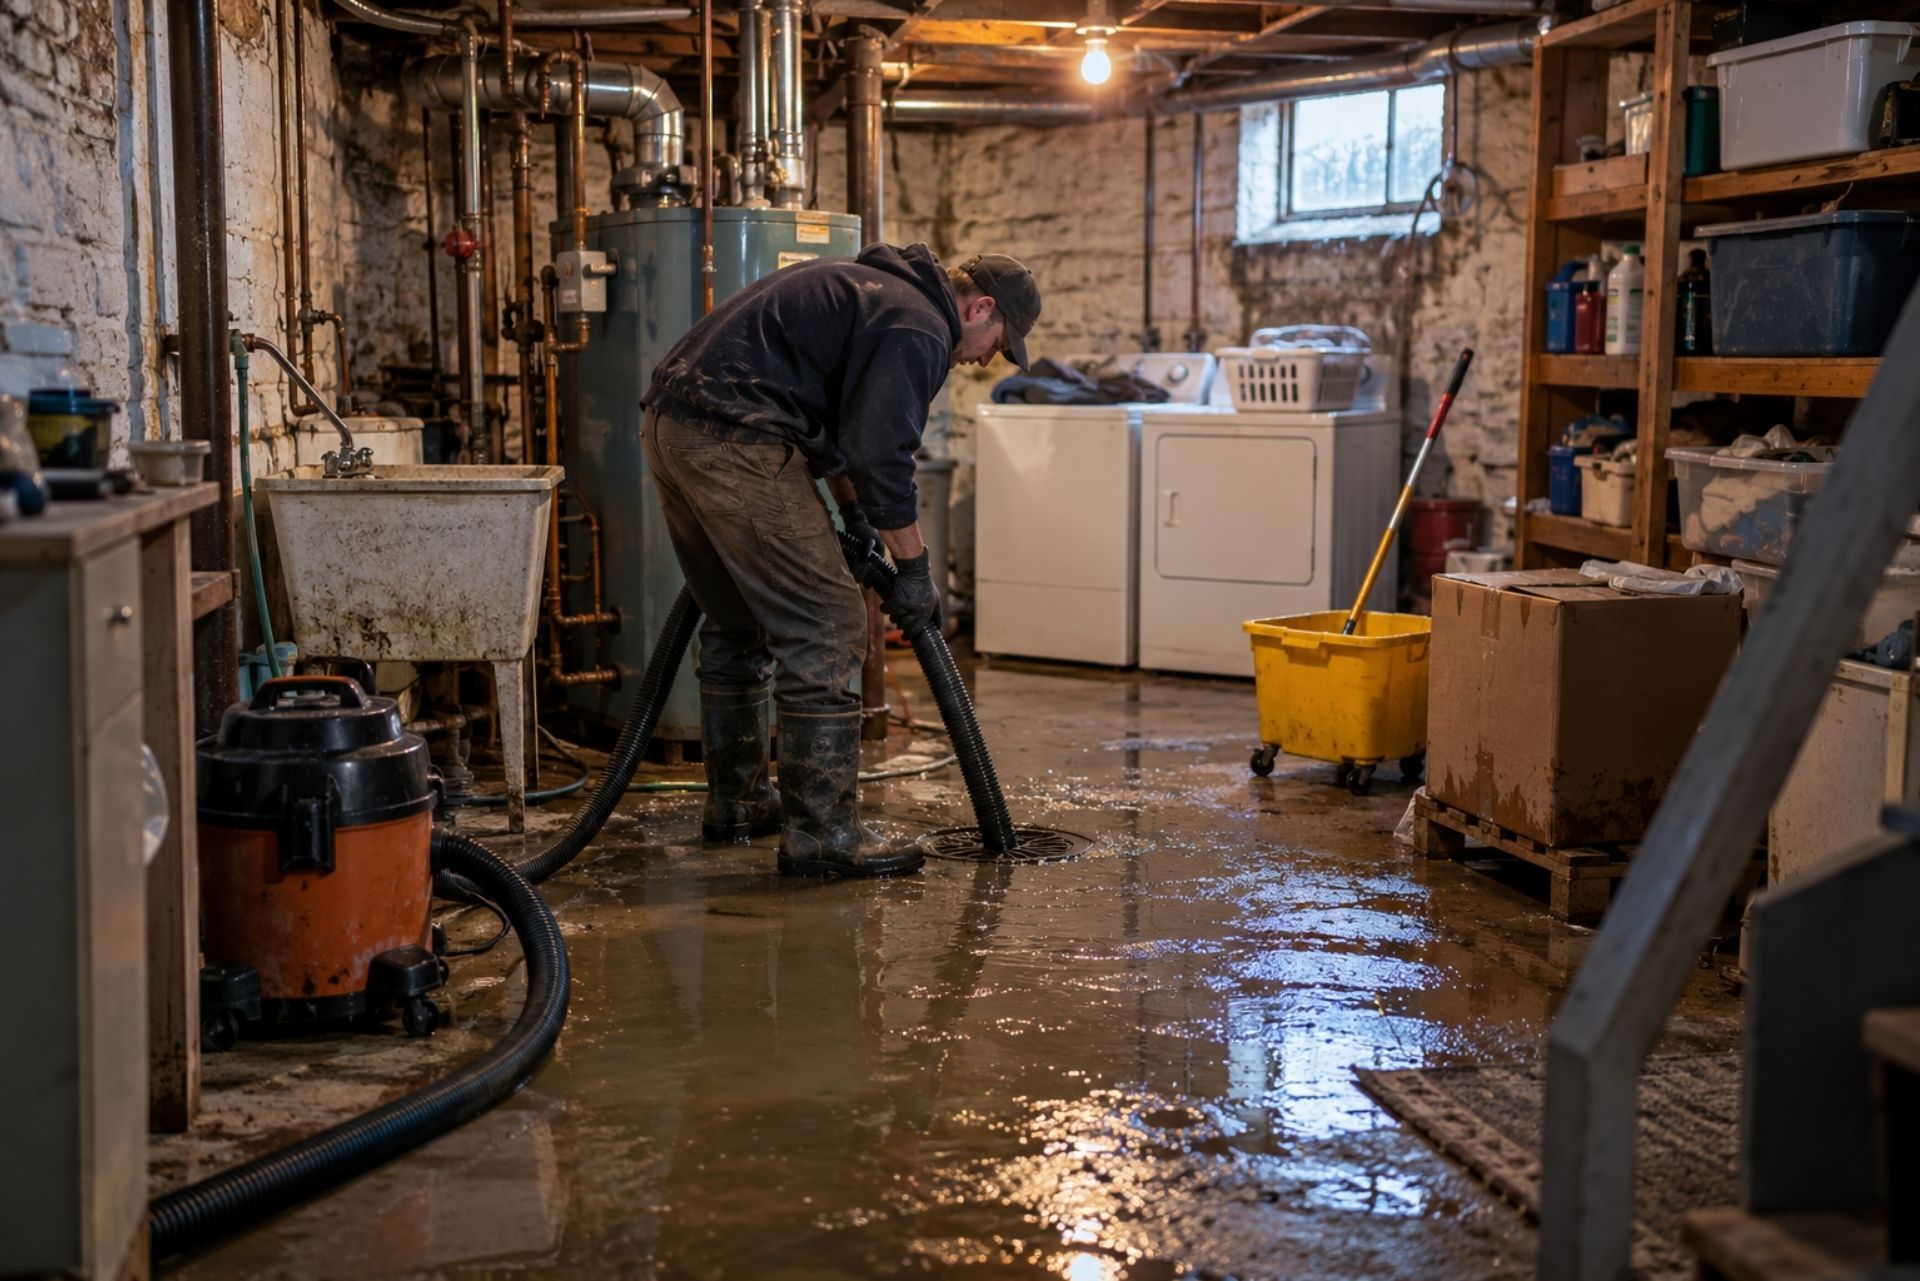
Sewer backup is not covered by a standard homeowners policy, and it is not covered by flood insurance either. You need a separate water backup rider, often called "Water Backup and Sump Discharge," to protect your basement when the system overflows.


Much of Pittsburgh runs on combined sewers, where stormwater and household waste share the same pipes. During a heavy downpour, those pipes fill, and the overflow has to go somewhere. Too often that means up through floor drains and basement toilets in older homes. Standard policies typically exclude these backups from the combined sewer-stormwater system, so finished basements, furnaces, and water heaters end up as out-of-pocket losses.


The regional fix is slow and expensive. ALCOSAN rates have climbed about 7% a year since 2019 to fund a $4.5 billion Clean Water Plan aimed at reducing overflows. Until that work catches up, your basement is still exposed.


The endorsement itself is usually affordable, typically $50 to $250 per year in the Pittsburgh market in 2026. Pick a limit that matches what's actually downstairs. A $5,000 limit disappears fast when you've got finished drywall, flooring, and a new HVAC unit down there. A backflow valve on your main line is worth pricing out too.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Home

A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.

Mine Subsidence Insurance in Western Pennsylvania

Yes, most Allegheny County homeowners should seriously consider mine subsidence coverage. Damage from ground collapsing into old coal mines is excluded from standard home insurance, and Pennsylvania offers a state-run Mine Subsidence Insurance Fund to fill that gap (verify current program details at publish).


More than 1 million Pennsylvania structures sit atop abandoned mines, and subsidence damage often tops $100,000 per incident. Cracked foundations, doors that suddenly stick, and sloping floors can all point to shifting ground below. Many homeowners don't know a mine exists under their street because the maps are old and the workings are deep.


The coverage is reasonably priced. As of October 2026, $150,000 in mine subsidence coverage costs roughly $128.50 per year for standard residential policies, though you should confirm current rates since they can change. Compared to a six-figure foundation repair, that math is easy. Contact MVP Insurance and we can talk through whether your address warrants it and how it pairs with your main policy.

Comparison of Pittsburgh Property Coverage Add-Ons

Coverage Type Standard Policy Inclusion Typical Endorsement Needed
Landslide Excluded (earth movement) DIC policy or limited earth movement endorsement; proposed state program pending
Sewer Backup Excluded Water Backup and Sump Discharge rider
Mine Subsidence Excluded State Mine Subsidence Insurance Fund policy (verify at publish)
Ordinance/Law Usually minimal or none Ordinance or law endorsement for code upgrades

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Frequently Asked Questions About Pittsburgh Home Insurance

Does my homeowners policy cover landslides? Almost certainly not. Standard policies exclude earth movement, so you'd need a specialty policy or endorsement, and those can be hard to find in Western Pennsylvania.


Why does my sewer back up when it rains hard? Pittsburgh's combined sewers carry both stormwater and wastewater, and heavy rain overwhelms them. The overflow can push back into basements through low drains.


Do I need mine subsidence insurance in Pittsburgh? If you live in Allegheny County, it's worth a serious look. Much of the area sits over abandoned coal mines, and the coverage costs far less than a typical subsidence repair.


How do I insure an old rowhouse properly? Set your dwelling limit based on full replacement cost, including shared-wall work and code upgrades. Add ordinance or law coverage so modern building requirements don't come out of your pocket.


Is flood insurance the same as water backup coverage? No. Flood insurance covers rising surface water, while water backup covers sewage or drain overflow coming into your home. Most Pittsburgh basements need the backup rider even if flood coverage isn't required.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Coverage What It Protects Common Gap to Watch
Homeowners Dwelling, belongings, liability High wind/hail deductibles
Renters Belongings, liability, living costs Low liability limits
Auto Vehicle damage, injury liability State minimum limits only
Motorcycle Bike, gear, liability Custom parts excluded
Boat Hull, motor, liability on water Trailer or navigation limits
Umbrella Excess liability above other policies Underlying limits too low
Life Income replacement for family Only employer coverage

Consult with MVP Insurance for Comprehensive Local Coverage

Pittsburgh homes need more than a generic policy: they need sewer backup protection, a mine subsidence check, honest rebuild limits for older rowhouses, and a clear-eyed conversation about landslide exposure. Getting those pieces right before a storm or a slope failure is the whole point.


Josh Medure and David Varrati have run MVP Insurance as an independent agency since 2008, which means we shop multiple carriers on your behalf instead of pushing one company's product. Stop by our Zelienople office at 108 E Grandview Ave, call (724) 453-1122, or reach our New Springfield, Ohio office at (330) 707-9055. If you're also reviewing your auto coverage, our Pittsburgh car insurance pagemakes bundling easy to compare. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


Ready to see what a policy built for these hills looks like? Start your quoteand we'll flag the gaps in your current coverage before they turn into a claim denial.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








