


Owner, MVP Insurance
Pennsylvania high value home insurance is specialized coverage for custom, historic and luxury homes whose rebuild costs, finishes and contents outgrow a standard homeowners policy. It typically adds guaranteed replacement cost, cash settlement on total losses, broader water damage protection and higher liability limits for estates in Sewickley, Fox Chapel and the North Hills.
The Importance of Pennsylvania High Value Home Insurance
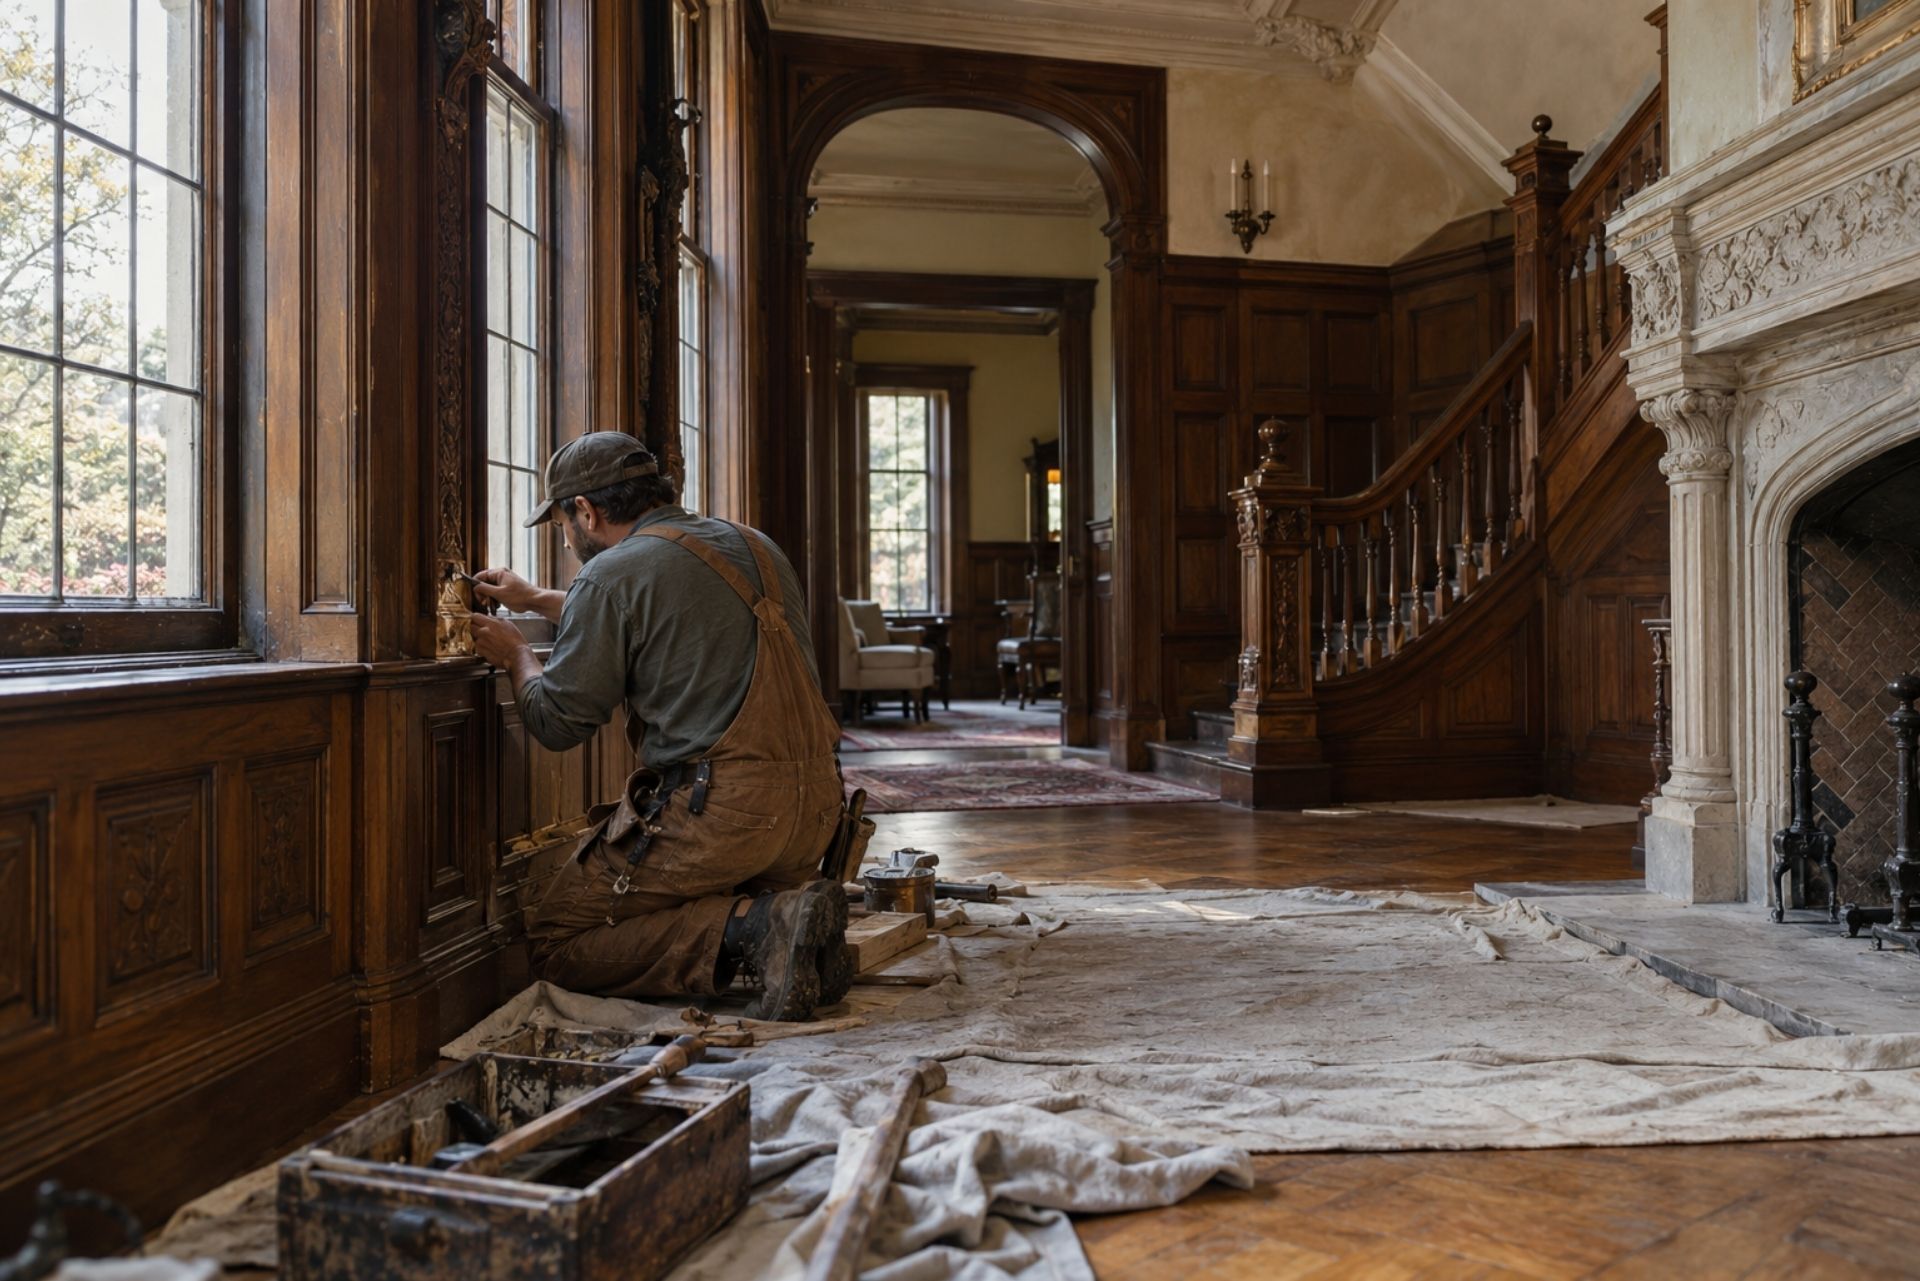
High value home insurance exists because standard policies were built for standard houses. Picture a 1920s stone Tudor on a Sewickley Heights hillside with hand-carved walnut paneling, slate roofing and leaded glass. A typical homeowners form caps the dwelling limit, settles certain materials at "like kind and quality," and may limit coverage for jewelry, art and wine to a few thousand dollars. On a home like that, those limits leave a gap that can run into seven figures.
Private client coverage closes that gap. It carries higher limits, broader definitions of covered loss and claims handling designed for properties where a single kitchen can cost more than an average house. It also tends to include services that standard carriers skip, such as appraisals by people who understand period craftsmanship.
Cost pressure makes this review more urgent. Pennsylvania homeowners saw premiums climb roughly 44% between 2021 and 2024, one of the steepest increases in the country. When rates rise that fast, many estate owners discover their policies were never written with their home's true replacement cost in mind. You can see how MVP approaches these accounts on our private client insurancepage.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Guaranteed Replacement Cost for Custom and Historic Homes
Guaranteed replacement cost pays to rebuild your home to its original quality even if the bill exceeds your dwelling limit. That single feature is often the reason to move into a high value policy.
Here's why it matters in western Pennsylvania. Our region is full of homes built by craftsmen who no longer exist: Fox Chapel colonials with plaster crown molding, Sewickley Victorians with heart pine floors, North Hills mid-century moderns with custom millwork. After a fire, rebuilding them requires specialty masons, plasterers and salvage-sourced materials. Those trades are scarce, and their prices jump sharply after a large regional storm or when lumber markets spike.
A standard policy with "extended replacement cost" might add 20% or 25% above your limit. That sounds generous until a contractor tells you your hand-split slate roof alone costs triple what the appraiser estimated. Guaranteed replacement cost generally has no cap, so the insurer absorbs that difference.
There are usually conditions. Most carriers require you to insure the home at 100% of its estimated replacement value and allow a periodic professional appraisal. Skip the appraisal or lowball the limit, and the guarantee may not apply. That's one of the most common mistakes we see.

Written By
David Varrati
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Cash Settlement Options for Total Losses
A cash settlement option lets you take a payout for a total loss instead of rebuilding the same house on the same lot. Many high value policies generally pay the full replacement cost figure even if you walk away from the site.
Standard policies often pay only actual cash value (replacement cost minus depreciation) unless you rebuild, and rebuild there. That can be a painful choice after a total loss. Maybe your kids have moved out and you never wanted 7,000 square feet again. Maybe you'd rather buy a finished home in Wexford than spend three years managing a custom rebuild in Fox Chapel.
With cash settlement, the decision stays yours. Clients typically use it in a few ways:
- Downsizing: Buying a smaller home and keeping the difference.
- Relocating: Moving closer to family or a second residence without a rebuild penalty.
- Selling the lot: Taking the payout and selling the land separately.
Read the details closely. Some forms base the payout on the dwelling limit, others on the estimated replacement cost at the time of loss. That difference can be substantial, so it's worth knowing which version you have before you ever need it.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan

Smart Home Protection and Water Leak Detection Credits
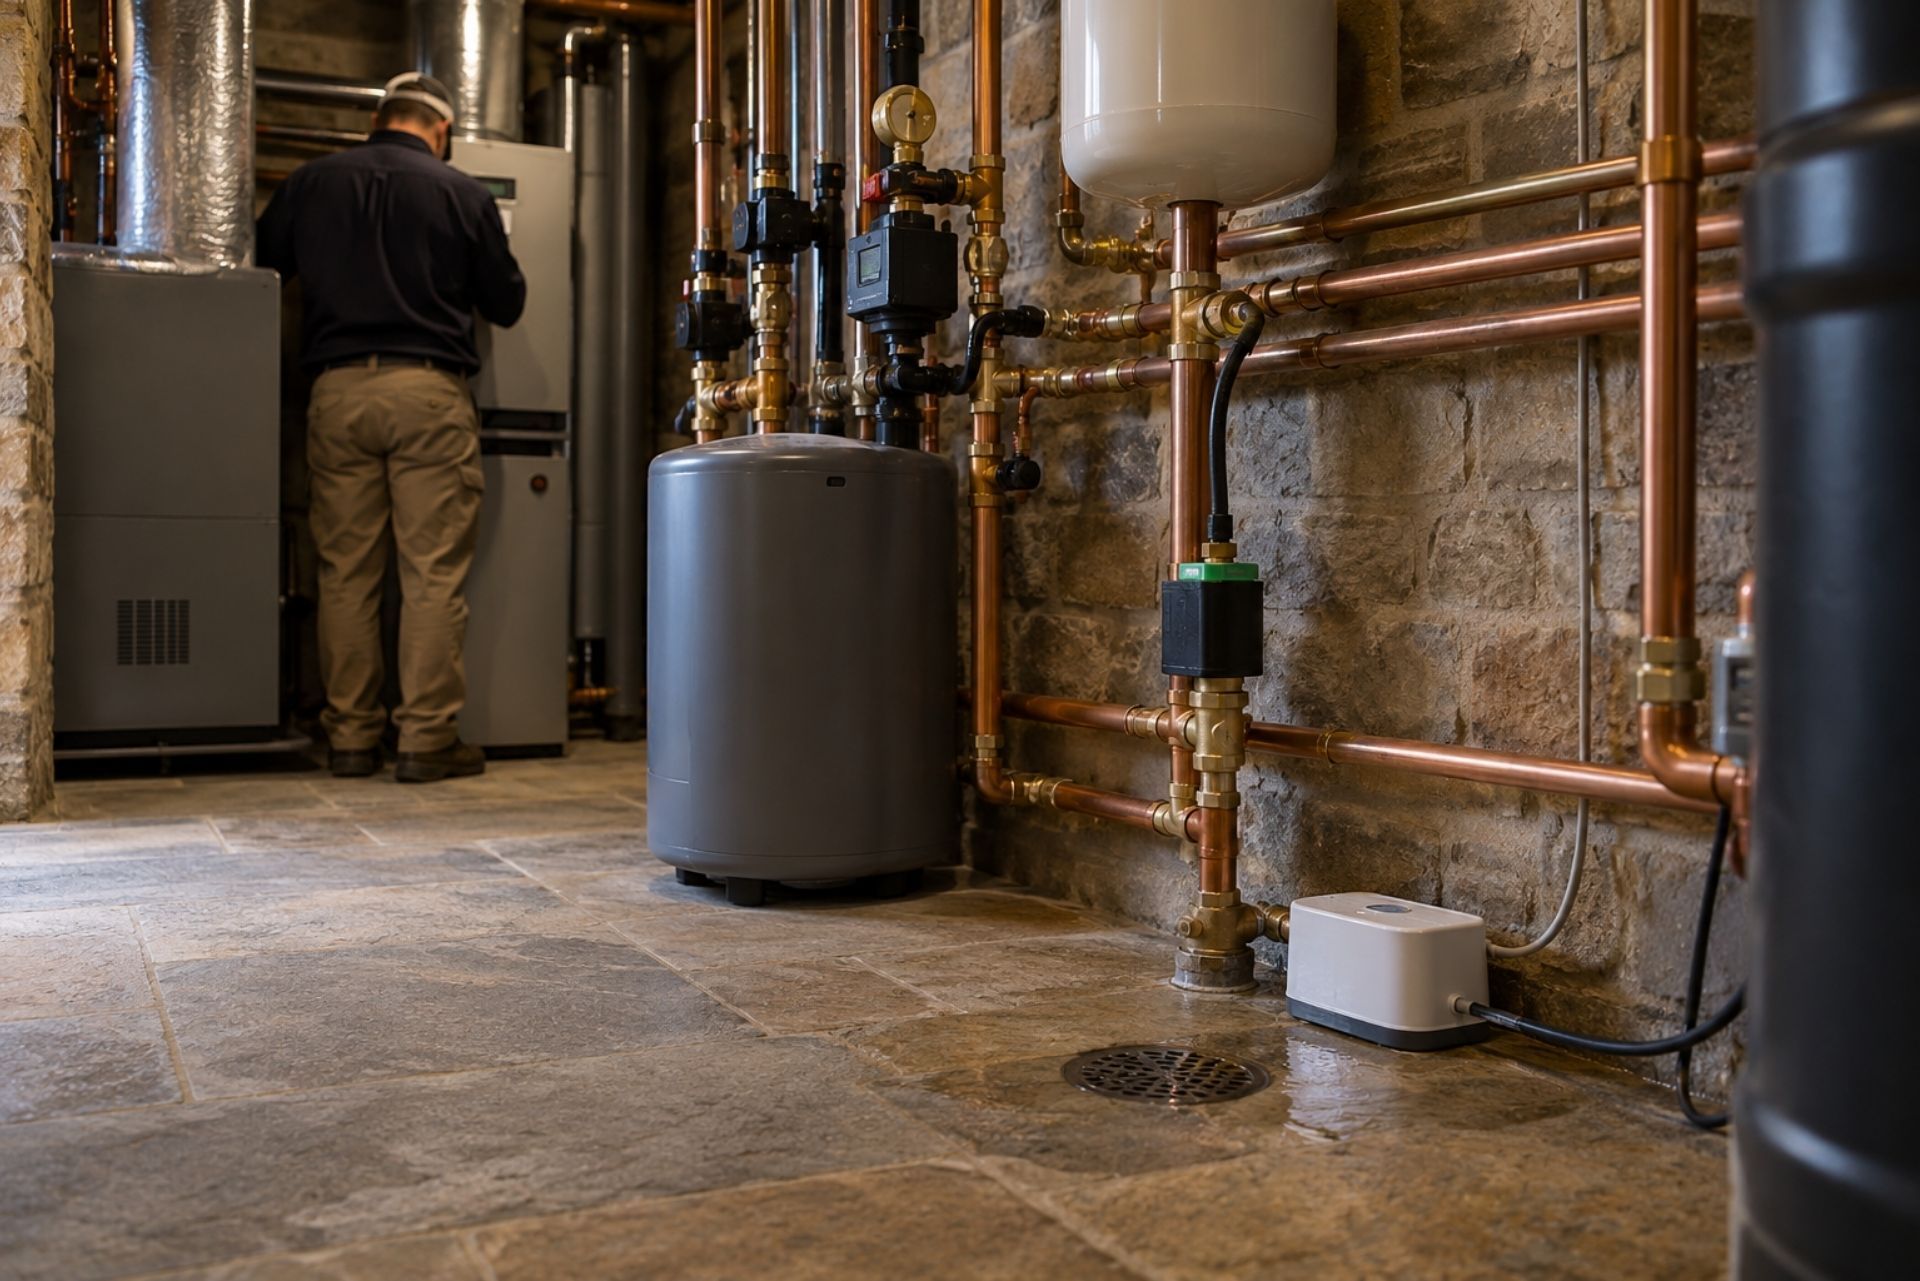
Installing an automatic water shut-off valve or a monitored leak detection system typically earns a meaningful premium credit on a high value policy. More importantly, it stops the claim that private client underwriters fear most.
Water damage, not fire, is the frequent and expensive loss on large homes. A supply line bursts behind a third-floor bathroom while you're away for a week in February. By the time a neighbor notices, water has soaked through plaster ceilings, hardwood floors and a finished basement. On a home with custom cabinetry and imported stone, a claim like that can rival a fire loss and displace the family for months.
An automatic shut-off valve senses abnormal flow and closes the main line within minutes. Leak sensors near water heaters, washers and dishwashers send alerts to your phone. Many carriers offer credits for these systems, and some require them on homes above a certain value or with frequent vacancy.
Some high value policies also include infrared home scans. A technician uses thermal imaging to find moisture and electrical hot spots behind walls before they turn into damage. If your policy offers that service, schedule it. It costs you an afternoon and can catch a slow leak years early.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Insuring Estates in Sewickley and Fox Chapel
Estates in Sewickley, Fox Chapel and the North Hills need coverage matched to older construction, larger lots and wealth spread across several properties and asset types. MVP Insurance serves these communities from our Zelienople office, close enough to know the difference between a Sewickley Heights carriage house and a newer build off Route 19 in Wexford.
Each area has its own quirks. Sewickley has many historic homes where code upgrade coverage (ordinance or law) becomes critical, since rebuilding often means bringing old wiring, plumbing and egress up to current standards. Fox Chapel properties often sit on wooded, sloped lots, so tree removal, retaining walls and landslide exclusions deserve a hard look. North Hills homes tend to be newer but larger, with pools, outbuildings and home offices that raise liability exposure.
Regulation matters here too. Pennsylvania updated filing requirements in Notice 2026-07, effective April 12, 2026, loosening rules for some property and casualty lines while keeping strict oversight on homeowners policy forms. Policy language still varies widely between carriers, which is why side-by-side comparison matters.
As an independent agency, MVP shops multiple carriers for each client. That matters for complex portfolios with a primary estate, a lake house, collector vehicles and an umbrella that all need to fit together without gaps.
Comparing Standard vs. Private Client Coverage
| Feature | Standard Homeowners | Private Client Policy |
|---|---|---|
| Dwelling settlement | Limit or capped extension | Guaranteed replacement cost (typically no cap) |
| Total loss options | Rebuild on site for full value | Cash settlement often available |
| Jewelry and art | Low sublimits | Scheduled, often no deductible |
| Water damage | Basic, with exclusions | Broader, with prevention credits |
| Code upgrades | Small percentage | Higher or full limits |
| Claims handling | General adjusters | Adjusters trained on luxury homes |
| Extra services | Rare | Appraisals, home scans |
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Valuable Items and Secondary Residence Considerations
Scheduling valuable items and reviewing every secondary residence belong in the same conversation as the main house. Gaps usually hide in these two places.
Start with valuables. A standard policy might cover stolen jewelry up to a small sublimit, with your deductible applied first. Scheduling each piece (an engagement ring, a watch collection, a painting inherited from a grandparent) gives it a stated value and broader protection, including mysterious disappearance. That's the classic case of a ring slipping off at a restaurant. Appraisals should be refreshed every few years, since gold, gemstones and art markets move. Our valuable items insurance in Pennsylvaniapage covers scheduling in more depth.
Secondary homes bring different risks. A ski place, a Lake Arthur cottage or a condo near family often sits empty for weeks, which raises the odds of an undetected freeze or burglary. Many policies limit coverage after extended vacancy. During a private client review, we typically look for:
- Vacancy and unoccupancy clauses
- Whether each property is on the same carrier for coordinated limits
- Rental use, even occasional short-term stays
- Liability coverage that extends to every location through your umbrella
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Common Questions About High Value Property Coverage
What qualifies as a high value home? Most carriers start private client coverage when a home's replacement cost reaches roughly $750,000 to $1 million, though thresholds vary. Custom construction or historic features can qualify a home sooner.
Does standard insurance cover historic craftsmanship? Usually not fully. Standard policies may pay for modern equivalents instead of matching original plaster, millwork or slate, while high value policies generally pay to restore original quality.
Is high value home insurance more expensive? Not always. Because these homes are underwritten carefully and often include prevention credits, a private client policy can price competitively against a standard policy with added endorsements.
Do I need an appraisal to get guaranteed replacement cost? Typically yes. Carriers usually want a professional replacement cost estimate so the dwelling is insured at its full value.
Will a water shut-off valve really lower my premium? Many carriers offer credits for automatic shut-off systems and monitored leak detection. The bigger benefit is avoiding a months-long water claim.
Can I insure my main home and lake house together? Often you can, and coordinating them under one carrier usually simplifies liability limits and claims.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Request a Private Client Review with MVP Insurance
A home in Sewickley, Fox Chapel or the North Hills deserves coverage built around what it would truly cost to replace. Guaranteed replacement cost protects original craftsmanship. Cash settlement keeps your options open after a total loss. Leak detection prevents the claim that hits large homes hardest, and scheduling valuables and second homes closes the gaps most owners never see until it's too late.
MVP Insurance is an independent agency founded in 2008 by Josh Medure and David Varrati. We compare multiple carriers and offer 24/7 claims support. Stop by our Zelienople office at 108 E Grandview Ave, Zelienople, PA 16063, call (724) 453-1122, or reach our New Springfield office at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. MVP is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
The final step to securing your estate is a clear look at what you have today.
Request a Private Client Reviewand we'll show you where your coverage stands.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.












