

Owner, MVP Insurance
Coverage
Buying a condo or townhome around Pittsburgh means sharing more than a parking lot. You share a roof, a set of walls, and often a plumbing stack with neighbors you may never meet. That shared structure is exactly why condo coverage confuses so many owners, and why the gaps tend to show up only after a pipe bursts or the association sends a bill you weren't expecting.
The good news is that the confusion follows a pattern. Most problems trace back to three things: not knowing what the association's policy actually covers, carrying too little loss assessment protection, and assuming a neighbor's leak is automatically the neighbor's problem. Sort those out and your coverage starts making sense.
Understanding Pennsylvania Condo Insurance and HO-6 Policies
Pennsylvania condo insurance, written as an HO-6 policy, protects your personal belongings, your personal liability, and the parts of your unit's interior that the association's master policy doesn't cover. The Pennsylvania Uniform Condominium Act generally governs what the association must insure, so your HO-6 fills whatever space the HOA leaves open.
Under that law, condo associations are generally required to insure common elements and units at a minimum of 80% of actual cash value,as of this writing. That sounds generous until you realize "units" can be defined narrowly in the declaration. Townhome communities are a different animal. Most Pittsburgh-area townhomes fall under the Uniform Planned Community Act,which typically requires the association to insure only common facilities, not the structure you live in. If you own a townhome, you may need something closer to a full homeowners policy rather than an HO-6, and our guide to homeowners insurance in Pennsylvaniacovers that side.
One more Pennsylvania-specific point: buyers generally get a five-day statutory right to cancel a purchase agreement after receiving the resale certificate and insurance summary. Use those five days to read the insurance section closely.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Reading the HOA Master Policy: Bare Walls vs All-In Coverage
A master policy is either bare walls or all-in, and the difference decides how much building you personally need to insure. Bare walls coverage stops at the studs: the association insures the framing, roof, and common areas, while you cover drywall, flooring, cabinets, fixtures, and everything inside. All-in coverage (sometimes called single entity) usually includes the original fixtures and finishes installed by the builder, though not your later upgrades.
The trouble is that declarations rarely use those exact labels. You'll find language like "improvements and betterments" or "fixtures installed as part of original construction" buried in a document that runs 60 pages. Ask the property manager for the certificate of insurance and the relevant declaration section, then match the wording to the table below.
| Master Policy Type | HOA Typically Covers | Your HO-6 Should Cover |
|---|---|---|
| Bare walls | Framing, roof, exterior, common areas | Drywall, flooring, cabinets, fixtures, upgrades, belongings |
| Single entity / original spec | Structure plus original builder finishes | Owner upgrades, belongings, liability |
| All-in | Structure, original finishes, sometimes owner improvements | Belongings, liability, loss assessment |
| Planned community (most townhomes) | Common facilities only | Often the entire dwelling plus contents |
The Importance of HO-6 Walls-In Coverage for Interior Build-Outs
Walls-in coverage (listed as Coverage A, or "dwelling," on an HO-6) pays to rebuild everything from the drywall inward. That includes flooring, cabinetry, countertops, built-in appliances, interior doors, light fixtures, and any upgrades you or a prior owner installed.
The most common mistake we see is an owner who renovated, say, $40,000 in quartz counters and new hardwood, but kept the $10,000 walls-in limit their lender suggested at closing. After a kitchen fire, the master policy restores the builder-grade cabinets at most, and the owner absorbs the rest. Even on an all-in master policy, your improvements usually aren't covered by the association.
A practical way to set the limit:
- Estimate replacement cost, not what you paid. Labor in Allegheny and Butler counties has climbed, and tear-out costs add up.
- Add every upgrade, including ones made before you bought.
- Ask for replacement cost on contents too, so a ten-year-old sofa isn't paid at garage-sale value.
Recent rule changes matter here. If your master policy carries a per-unit deductible, your HO-6 is now required to cover the perils that deductible applies to for mortgaged owners.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
Managing Loss Assessment Limits and HOA Deductibles
Loss assessment coverage pays your share when the association passes costs down to owners, usually because of a large master policy deductible or damage that exceeds the master policy's limits. It's an HO-6 endorsement, and many policies include only a small default amount unless you raise it.
Here's how it plays out. A windstorm damages the roof on a 20-unit building, and the master policy carries a $25,000 deductible. The board divides that deductible among owners, or bills it all to the units affected. Without enough loss assessment coverage, that check comes from your savings.
Your limit should be at least as high as the association's per-unit or building deductible. Under Fannie Mae and Freddie Mac Bulletin 2026-C, effective July 1, 2026, there's now a $50,000 ceiling on per-unit deductibles for condo master policies. That gives you a useful upper benchmark. As one analysis put it, "The association's choice reaches into hundreds of separate insurance contracts it is not a party to."
Watch for one detail: some HO-6 policies limit how much of an assessment tied to a deductible they'll pay. Ask how your carrier handles that specifically. With Pennsylvania homeowners premiums rising 28.9% in real terms between 2021 and 2025, many boards are choosing higher deductibles to hold down master policy costs.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Deductibles are where you can trim premium without gutting protection. Industry voices suggest raising deductibles to $1,000 to offset higher urban base rates. Just make sure you can actually pay that amount after a February break-in.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Protecting Older Housing Stock and Garaged Vehicles
Cleveland's older housing stock creates an auto insurance angle people don't expect. Many homes in Ohio City, Tremont, Slavic Village, and the inner-ring suburbs have detached garages built decades ago, often narrow, aging, or unusable for modern vehicles. That pushes cars onto driveways and streets, which raises theft and weather exposure.
If your garage does house your car, its condition matters. A collapsed roof from heavy snow damages the vehicle (a comprehensive auto claim) and the structure (a homeowners claim). Coordinating both policies avoids finger-pointing between coverages, and Cleveland residents can save up to 20% by bundling auto with homeowners or renters policies.
Review your homeowners insurance options in Cleveland alongside your Ohio car insurance coverage so the gaps between them close.
Handling Water Damage Between Units in Pittsburgh Area Condos
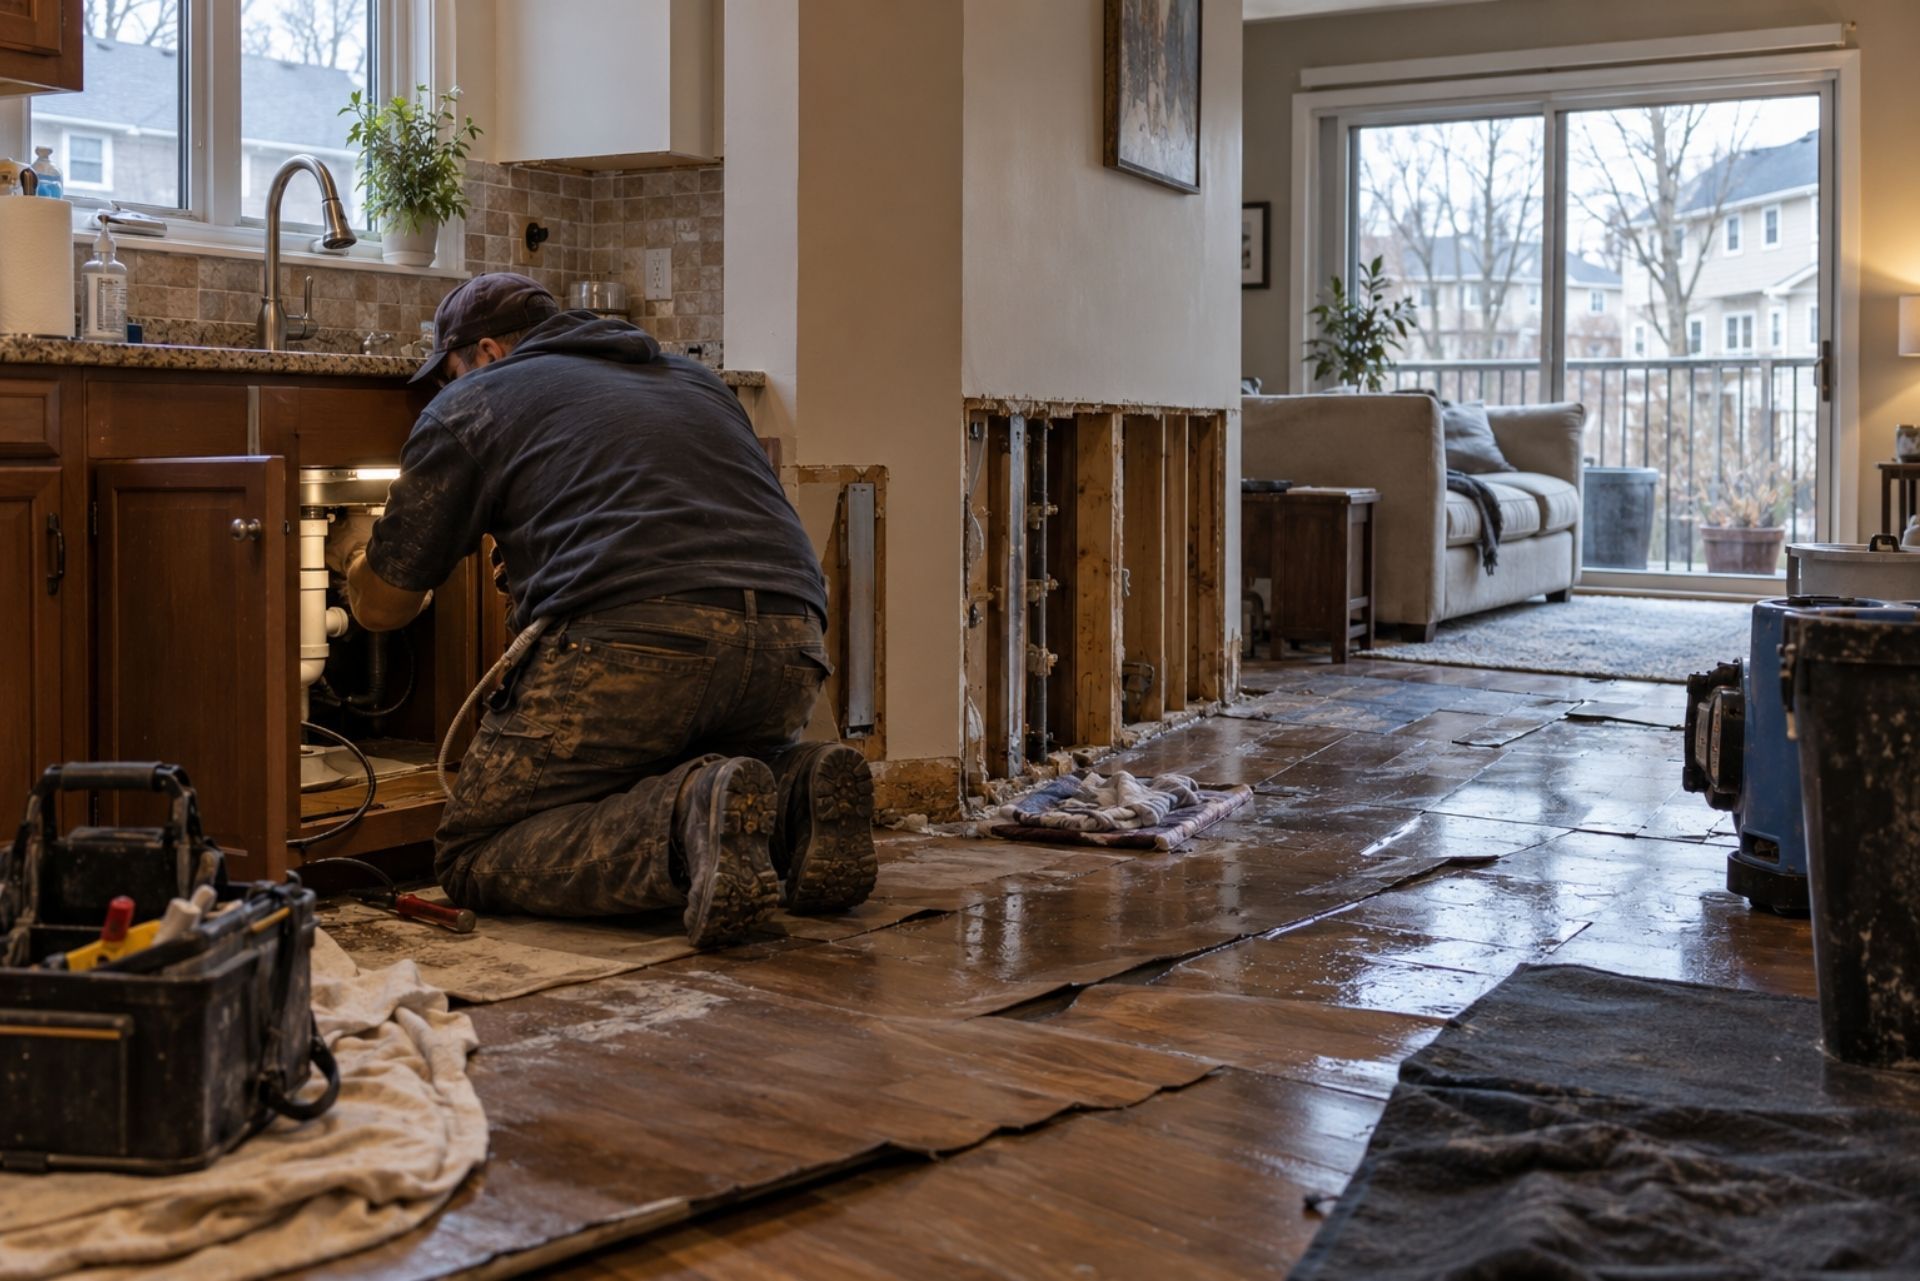
When water travels from one unit to another, your own HO-6 usually pays for the damage to your unit first, and fault gets sorted out afterward. Owners often expect the upstairs neighbor's policy to pay automatically, but that only happens if the neighbor was negligent.
Liability coverage responds to negligence, not to accidents. If your neighbor's supply line to a washer fails without warning, that's generally a sudden accident, and their liability coverage may not owe you anything. Your walls-in and contents coverage repair your ceiling and replace your rug, minus your deductible. If the neighbor ignored a known leak for weeks, your carrier may pursue their insurer to recover what it paid, called subrogation.
The building matters too. Condos in older neighborhoods like Mt. Lebanon and Dormont often have aging internal plumbing, cast iron drains, and shared stacks that fail inside walls. When the leak starts in a common element, the master policy may respond, subject to its deductible, which loops back to loss assessment.
A few steps that protect you:
- Shut off water and photograph everything before cleanup.
- Notify the property manager and your agent the same day.
- Ask whether your policy includes water backup coverage, since sewer and drain backups are usually excluded otherwise.
- Keep receipts for drying and emergency repairs.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
These suggestions are a starting point, not a universal rule. Your agent can tailor them to your assets, vehicles, and budget.
Comparing Top Pennsylvania Condo Insurance Carriers
No single carrier fits every condo owner, so comparing several quotes side by side usually produces the right mix of price and coverage. Underwriting appetite shifts year to year, and in April 2026 the Pennsylvania Insurance Department issued Notice 2026-07 updating property and casualty filing requirements, which may change how carriers adjust rates going forward.
As an independent agency, MVP Insurance works with these carriers rather than representing just one:
| Carrier | What Owners Often Notice |
|---|---|
| Erie | Strong regional presence in Western PA, agent-focused service |
| Westfield | Sold through independent agents, solid endorsement options |
| Progressive | National reach, convenient digital tools, often bundled with auto |
| Frederick Mutual | Regional mutual, can be competitive for HO-6 and older buildings |
Pricing and endorsement availability typically vary by building age, claims history, and ZIP code, so a carrier that suits a newer Cranberry townhome may not suit a 1960s Squirrel Hill co-op-style building. MVP Insurance has offices in Zelienople and New Springfield, and the team shops these options for you, then explains how walls-in limits and loss assessment compare across quotes. You can also review our broader Pennsylvania personal insurance optionsif you're bundling auto or umbrella coverage.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
How Stacking Protects Multi-Vehicle Households
Say your household insures three cars, each with $50,000 in underinsured motorist coverage. Stacked, an injured family member could typically access up to $150,000. Unstacked, they get $50,000.
Here's where stacking usually makes the most sense:
- Households with two or more vehicles, since each added car increases the available limit
- Families without strong disability coverage who would struggle if a breadwinner couldn't work
- Drivers who chose limited tort, because uninsured motorist claims can help offset restricted lawsuit rights
- Commuters on busy corridors where uninsured drivers are more common
Single-car owners get less benefit from stacking, so unstacked may be reasonable there.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Frequently Asked Questions About Pennsylvania Condo Insurance
Do I need condo insurance if my HOA has a master policy?Yes. The master policy protects the building and common areas, not your belongings, liability, or usually your interior finishes.
How much walls-in coverage should I carry?Enough to replace everything from the drywall inward at today's construction costs, including upgrades. On a bare walls building, that's often far more than the minimum your lender asks for.
How do I find out if my master policy is bare walls or all-in? Request the certificate of insurance and declaration from your property manager. Look for language about original fixtures or improvements and betterments.
What loss assessment limit makes sense? At least the amount of your association's deductible. Since per-unit master deductibles are now capped at $50,000 for loans backed by Fannie Mae and Freddie Mac, that figure is a reasonable ceiling to consider.
Is a townhome insured the same way as a condo?Often not. Most Pittsburgh-area townhomes fall under planned community rules, so the association may insure only common areas and you may need a full homeowners policy.
Who pays when my upstairs neighbor's pipe leaks into my unit? Your HO-6 typically pays first, minus your deductible. Your carrier may then seek repayment if the neighbor was negligent.
Getting condo coverage right comes down to reading the master policy honestly, matching your walls-in and loss assessment limits to what the association leaves you, and planning for water before it shows up in your ceiling. Those three steps prevent most of the ugly surprises Pittsburgh-area owners run into.
If you'd like a second set of eyes on your declaration and current policy, start your quotewith MVP Insurance. We'll compare carriers and walk you through the gaps in plain language. Visit or call us at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122, or 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.