

Owner, MVP Insurance
Boardman OH car insurance needs to account for three local realities: heavy stop-and-go traffic on the US-224 retail corridor, a high share of rear-end crashes near Southern Park Mall, and a meaningful number of uninsured drivers in Ohio. For most households, that means strong liability limits, collision coverage, and uninsured motorist protection that hasn't been waived.
If you live in Boardman Township, you probably already know which stretches of Route 224 test your patience on a Saturday afternoon. What fewer drivers think about is how that daily traffic pattern should shape the policy sitting in their glove box. A policy that looks fine on paper can leave real gaps once a distracted driver taps your bumper outside a shopping plaza or your 16-year-old gets a license.
This guide walks through the coverage decisions that matter most for local families: handling crash claims, deciding on uninsured motorist protection, adding a new teen driver without overpaying, and pairing your auto policy with your homeowners coverage. Use it as a checklist before your next renewal.
Boardman OH Car Insurance and Local Road Risks
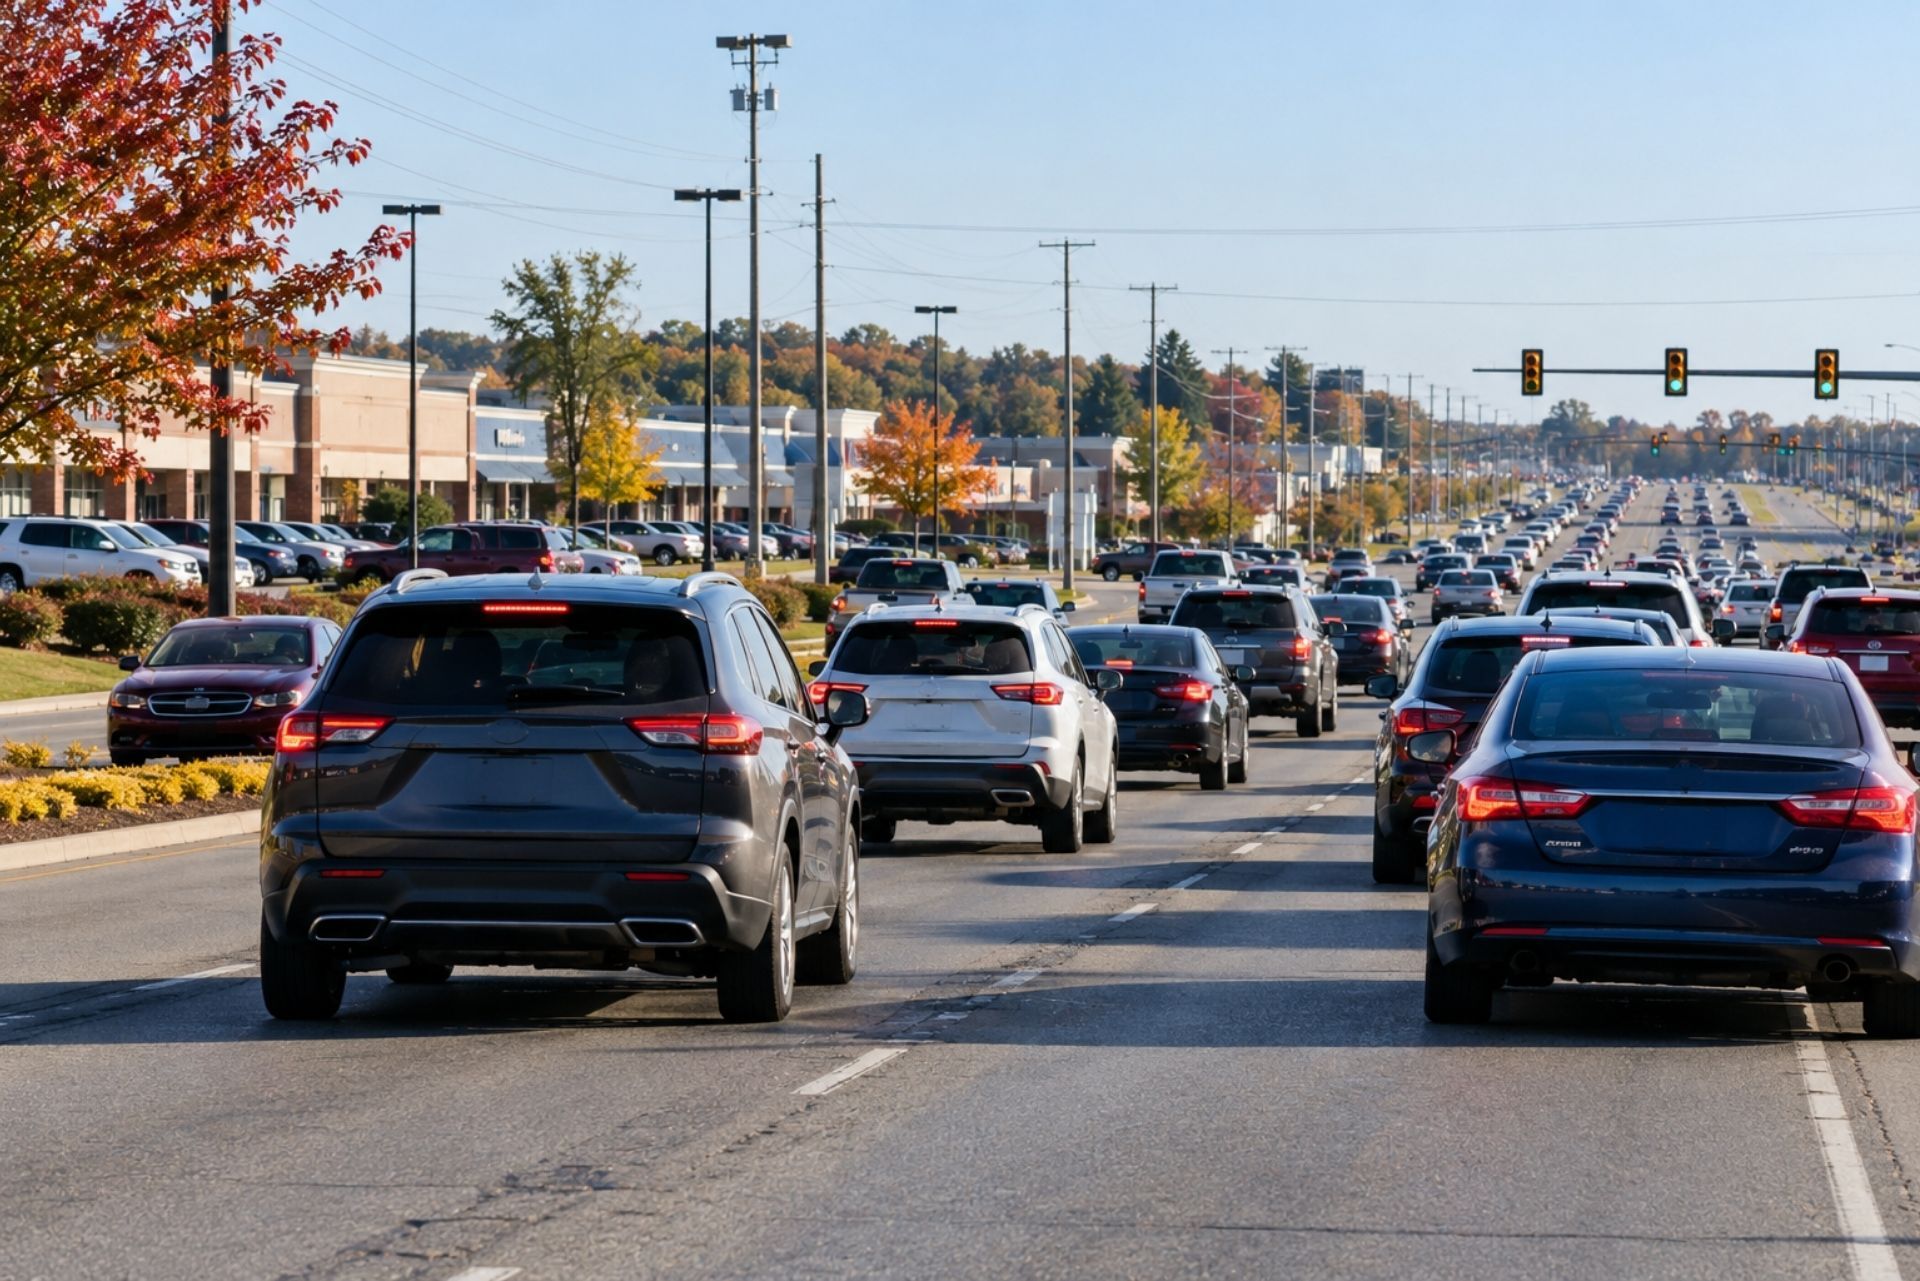
Boardman car insurance protects drivers throughout Boardman Township, and the biggest daily exposure for most residents is the busy US-224 commercial corridor around Southern Park Mall. The right policy reflects how and where you actually drive, not just what Ohio requires you to carry.
Boardman has a mix of quiet residential streets and one of the most concentrated shopping districts in the Mahoning Valley. That combination matters to insurers. You might spend most of your week on calm side streets, then spend an hour on a corridor packed with turning vehicles, parking lot exits, and drivers who are reading store signs instead of watching brake lights. Underwriters price for where losses happen, and dense commercial traffic produces a steady stream of fender benders and injury claims.
MVP Insurance serves Boardman drivers from its New Springfield office at 13823 Grant St, about 15 minutes away. As an independent agency founded in 2008 by Josh Medure and David Varrati, MVP works for the customer rather than for a single insurance company. That means the agency shops several carriers and compares coverage side by side, so you aren't stuck accepting whatever one company quotes.
That independence is useful in a township like Boardman, where two neighbors on the same street can get very different rates based on their driving history, credit, vehicles, and the coverage choices they've made. A local agent who knows the area can explain why one quote is lower and whether that lower number hides a smaller limit or a waived coverage. For a broader look at statewide options, MVP's guide to car insurance in Ohiocovers the basics that apply everywhere from Boardman to Columbus.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Managing US-224 Retail Corridor Traffic and Southern Park Mall Risks
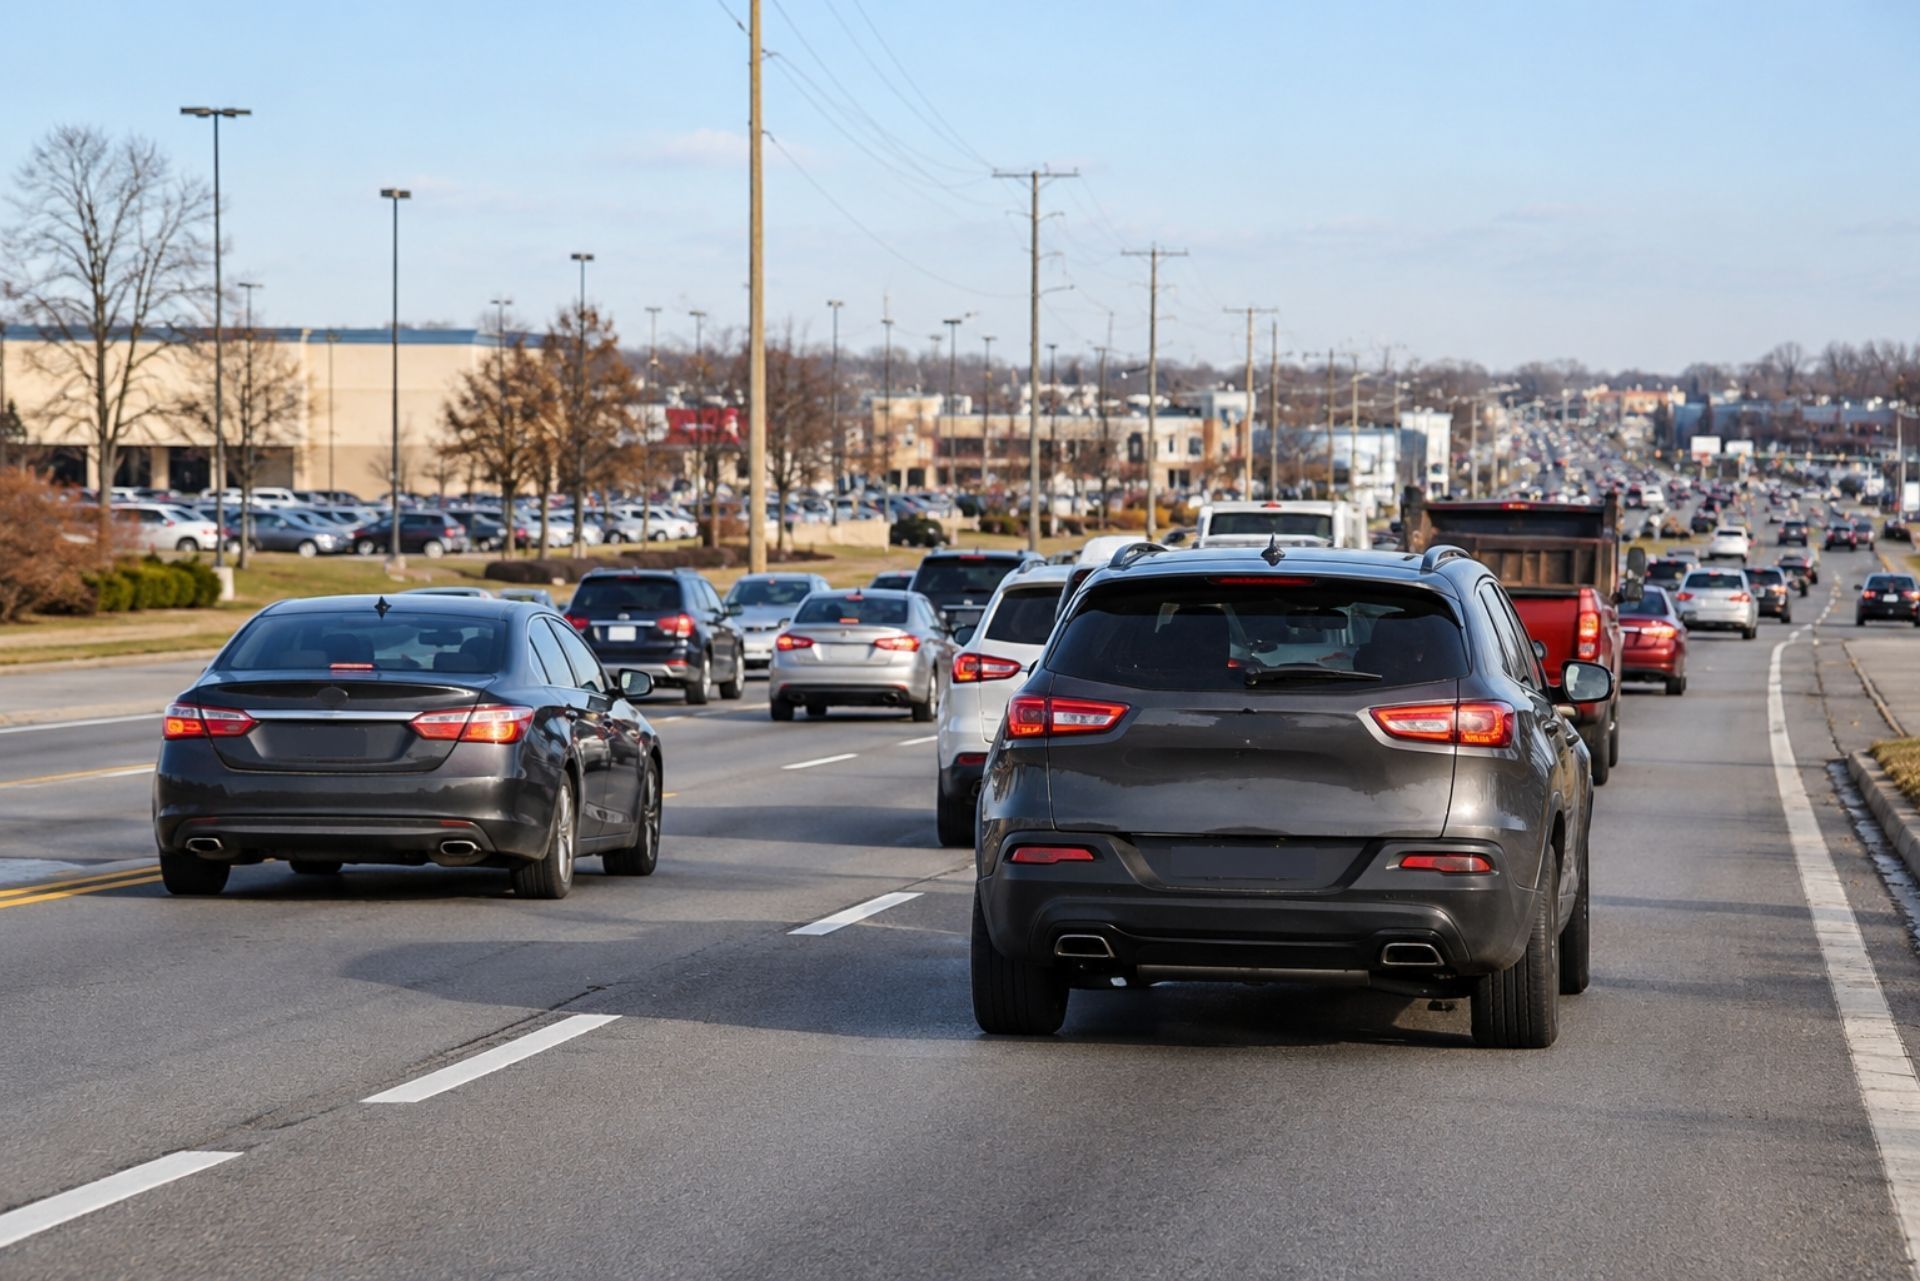
The short answer: heavy shopper traffic around Southern Park Mall and along the US-224 corridor raises your odds of a minor crash, a parking lot scrape, or a damaged vehicle, which makes collision and comprehensive coverage worth keeping for most local residents.
Route 224 through Boardman is lined with big-box stores, restaurants, banks, and plaza entrances, and many drivers are turning left across traffic at the same time. Local reporting on ODOT's corridor study found that rear-end collisions account for 60% of crashes on the US-224 retail corridor, mostly because of congestion and frequent left turns. ODOT has also proposed changes, including added through lanes, dedicated turn lanes, and removing signals at two intersections to cut down on stop-and-go hazards.
Until any of those improvements are built, the risk is what it is. Here's how the main physical damage coverages apply to corridor driving:
- Collision: Pays to repair your car after you hit another vehicle or object, or when you're found at fault in a rear-end crash. Without it, a minor at-fault bump in a plaza lot comes entirely out of your pocket.
- Comprehensive: Covers non-crash damage such as theft, vandalism, falling objects, hail, and deer strikes. Cars parked for hours in busy lots during the holidays are a common target for break-ins.
- Rental reimbursement: Pays for a rental while your car is in the shop. Body shops in the area can back up after winter storms, so a week without a car is a real possibility.
A common mistake we see is dropping collision on a car that still has decent value just to trim the premium. On a vehicle worth $12,000, the savings rarely justify absorbing a $4,000 repair after a low-speed crash. A better move is often raising your deductible from $500 to $1,000, which keeps the protection while lowering the cost.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Comparing Water Backup Coverage Limits
Endorsements come in tiers, and the default limit is often too low for a fully finished space. Match the limit to what's actually down there.
How to Handle Rear-End Collision Claims in Boardman
If you're rear-ended on Route 224, the other driver is usually presumed at fault, but you still need to document everything and report the claim quickly. Working through an independent agent helps you decide whether to file with your own carrier or the other driver's, and keeps the process moving.
Rear-end crashes tend to look simple, but they cause a surprising number of claim disputes. The other driver may say you stopped suddenly or cut in front of them while changing lanes. Neck and back injuries often don't show up until a day or two later, and a quick roadside agreement to "just exchange numbers" can fall apart once repair estimates come in.
Follow these steps after a crash:
- Move to a safe spot if the cars are drivable, turn on your hazards, and call Boardman police so there's an official report.
- Photograph both vehicles, license plates, the intersection or lot entrance, traffic signals, and any skid marks.
- Get the other driver's name, phone number, insurance company, and policy number. Snap a photo of their insurance card.
- Collect contact information from witnesses. Shoppers and workers at nearby businesses often see what happened.
- Get checked by a doctor if you feel any soreness, even if it seems minor.
- Call your agent before giving a recorded statement to the other driver's insurer.
You generally have two paths. Filing with the at-fault driver's carrier avoids your deductible, but you're dealing with a company that has no obligation to you. Filing with your own collision coverage is often faster; your insurer then pursues the other company and can recover your deductible later. MVP Insurance offers 24/7 claims service, so you can get guidance the same evening rather than waiting until Monday.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella Coverage
An umbrella policy typically kicks in once your underlying auto or home liability is exhausted. Picture a multi-car accident where injuries run well past your auto limit, or a guest seriously hurt on your deck. Umbrellas often cover claims your base policies don't, like certain libel or slander suits. The catch: carriers usually require minimum underlying limits, so your auto and home policies must be set correctly first.
The Role of Umbrella and Life Insurance in a Comprehensive Plan
The Importance of Uninsured Motorist Coverage
Uninsured motorist coverage pays for your injuries, and in some cases your vehicle damage, when a driver without insurance causes a crash. In Ohio it's optional, but turning it down is one of the riskiest money-saving moves a driver can make.
Under Ohio Revised Code Section 3937.18, insurers must offer uninsured and underinsured motorist (UM/UIM) coverage, but you can reject it in writing. Many people sign that rejection form at the bottom of an application without realizing what it means. If you're not sure whether you did, ask your agent to check your declarations page today.
The exposure is real. Estimates cited in proposed legislation put roughly 18.5% of Ohio drivers, nearly 1 in 5, on the road without insurance. On a corridor as crowded as US-224, you're sharing the road with plenty of them. Underinsured coverage matters just as much: a driver carrying only Ohio's minimum limits may have far too little to pay for a serious injury.
There are also limits on what UM covers for vehicles. For property damage caused by an identified uninsured driver, Ohio law caps recovery at the lesser of your policy limit or $7,500, with a deductible of no more than $250. That's why collision coverage still matters even when you carry UM; for a newer car, $7,500 won't go far.
Lawmakers are paying attention too. House Bill 596, introduced in the 136th General Assembly, would make UM coverage mandatory on all policies rather than optional. It's a proposal at this point, not law, so for now the decision is still yours.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Bundling makes sense for Ohio families who commute into Pennsylvania. You get one renewal conversation, liability limits that match across policies, and often a multi-policy credit. It also makes room for an umbrella policy, which usually requires matching underlying limits on your home and auto policies.
Start with the details of homeowners coverage in Ohio, then line them up with car insurance for New Springfield drivers. If you drive daily on Route 224 or into Pennsylvania, make sure your vehicle's garaging address and mileage are accurate. A mismatch can complicate a claim.
Adding Teen Drivers to Your Policy
Adding a teen driver raises your liability exposure and your premium, but keeping your new driver on your existing policy is usually far more affordable than buying them a separate one. The key is to raise your liability limits, not lower them, while looking for legitimate ways to offset the cost.
Market data puts the average increase at about 102% when a 16-year-old joins a parent's Ohio auto policy. That sounds steep, but a standalone full-coverage policy for a 16-year-old in Ohio averages more than $2,900 per year, so staying on the family policy is typically the smarter route. For context, full coverage in Ohio averages around $137 per month as of August 2026, and minimum-only liability averages about $39 per month.
The bigger issue is liability. A teen driver brings a higher chance of an at-fault crash, and if your teen injures someone, your household assets and future wages are on the line. This is the worst time to cut limits to save money. Here are practical ways to manage the transition:
- Ask about good student credits, which many carriers offer for strong grades.
- Look into telematics or driving-app programs that reward safe habits.
- Assign the teen to the oldest, safest vehicle in the household when the carrier allows it.
- Consider an umbrella policy if your home equity or savings exceed your auto limits.
- Report the new license right away. Waiting creates a claim problem, not a savings.
Because MVP Insurance compares multiple carriers, the household that was well priced with one company before the teen arrived may find a better fit elsewhere afterward. Teen pricing varies widely between carriers, so this is a good moment for a fresh comparison.
Ohio Minimum Requirements vs Recommended Limits
Ohio's current minimum liability limits are 25/50/25: $25,000 per person for injuries, $50,000 per accident, and $25,000 for property damage. HB 596 has proposed raising the minimum to 50/100/25, though that change has not been enacted. Neither number reflects what a serious crash actually costs.
| Coverage | Ohio Minimum | Suggested for Families with Teens |
|---|---|---|
| Bodily injury per person | $25,000 | $100,000 to $250,000 |
| Bodily injury per accident | $50,000 | $300,000 to $500,000 |
| Property damage | $25,000 | $100,000 |
| Uninsured/underinsured motorist | Optional (can reject in writing) | Match your liability limits |
| Collision and comprehensive | Not required | Keep on vehicles with real value |
A single trip to the hospital plus a damaged late-model SUV can blow past $25,000 quickly. Your agent can help you find the right level based on your home, savings, and income.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Bundling Boardman Home and Auto Insurance
Bundling your home and auto policies with one carrier often lowers your combined premium and simplifies renewals, billing, and claims. It also helps make sure your liability limits line up across both policies, which matters if you plan to add an umbrella.
Most Boardman homeowners already have two of their biggest financial exposures sitting in the same driveway. When those policies are with separate carriers, it's easy to end up with mismatched renewal dates, different liability limits, and two deductibles if a single storm damages both the house and the car. A bundled setup reduces those headaches and usually earns a multi-policy credit.
Bundling isn't automatically the right call, though. Sometimes one carrier offers strong homeowners pricing but weak auto rates, and splitting the policies comes out ahead. An independent agent can price both options and show you the real difference instead of assuming the bundle wins. MVP Insurance does that comparison for you, so you don't have to request quotes from five companies on your own.
If you own a home in the township, MVP's page on
Boardman homeowners insurancecovers local considerations like older housing stock, roof age, and water backup coverage. MVP helps clients protect both assets through its offices in New Springfield, OH and Zelienople, PA, with modern tools that let you view documents and ID cards without digging through paperwork.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Frequently Asked Questions About Boardman Car Insurance
What car insurance is required in Boardman, Ohio? Ohio requires liability coverage of at least 25/50/25. Your insurer must offer uninsured motorist coverage, but you can turn it down in writing.
Is uninsured motorist coverage worth it in Ohio? For most drivers, yes. With nearly 1 in 5 Ohio drivers estimated to be uninsured, it protects you when the at-fault driver can't pay.
Who pays if I get rear-ended on Route 224? The driver who hit you is usually responsible, and their insurance should pay. You can also use your own collision coverage to get repairs moving faster and let your insurer recover the cost.
How much does adding a teen driver cost in Ohio? On average, adding a 16-year-old roughly doubles a parent's premium. Keeping the teen on the family policy is still usually less expensive than a separate policy.
Where is MVP Insurance's office near Boardman? The New Springfield office is at 13823 Grant St, New Springfield, OH 44443, about 15 minutes from Boardman. You can reach it at (330) 707-9055.
Can I keep my current carrier if I work with an independent agent? Often, yes. An independent agent compares your current policy against other options and only recommends a change if it actually helps you.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Contact MVP Insurance for Personal Assistance
Driving in Boardman means accepting some built-in risk: crowded plaza entrances on Route 224, a heavy share of rear-end crashes, and a meaningful number of uninsured drivers on Ohio roads. The fix isn't complicated. Carry liability limits well above the state minimum, keep uninsured motorist coverage instead of waiving it, hold onto collision while your car still has value, and raise your protection, not lower it, when a teen gets behind the wheel.
If you'd like someone to look over your current policy, Josh Medure and David Varrati are glad to help. Call the New Springfield office at (330) 707-9055 or the Zelienople office at (724) 453-1122 for a policy review. MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
Want a side-by-side comparison of Boardman OH car insurance options without making a dozen phone calls?
Start your quoteand let MVP shop multiple carriers for you. A 15-minute conversation now can save you from finding a coverage gap after the crash, when it's too late to fix.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.