


Cleveland OH Homeowners Insurance

Owner, MVP Insurance

Cleveland homeowners insurance costs more and qualifies harder when the house is old. Carriers look closely at original wiring, roof condition, basement water history, and whether the home sits empty. If you know those four issues before you shop, you can fix problems first, avoid surprise declines, and buy coverage that actually pays for a century-old rebuild.


That matters in a city where many streets were built out before World War II. Slate roofs, plaster walls, clay sewer laterals, and oak trim are part of what makes neighborhoods like Tremont, Detroit-Shoreway, and Slavic Village appealing. They are also what makes underwriters ask more questions. A 1915 colonial and a 2005 ranch can sit in the same ZIP code and get very different answers from the same carrier.


Insurance mistakes on older homes rarely show up on day one. They show up after a frozen pipe, a sewer backup during a July storm, or a roof that sags under February snow. That is when the policy wording matters, and that is when many owners find out their coverage was built for a newer house.

Cleveland OH Homeowners Insurance for Century-Old Houses

Cleveland's older housing stock affects both whether you can get a policy and how much the policy will pay to rebuild. Carriers in Cuyahoga County often ask for the year of construction plus update dates for the roof, wiring, plumbing, and heating. Homes without documented updates may be steered toward limited policy forms or declined outright.


Replacement cost is the bigger trap. Rebuilding plaster walls, custom millwork, or a slate roof with like kind and quality materials costs far more than standard construction. Some carriers won't offer full replacement cost on older homes and instead offer functional replacement cost, which pays to rebuild with modern equivalents like drywall instead of plaster. That can be a sensible trade, but you should choose it on purpose. Our overview of homeowners insurance in Ohioexplains how these settlement options work across the state.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

How Does Knob-and-Tube Wiring Affect Your Insurance Eligibility?

Active knob-and-tube wiring can disqualify your home with many carriers. As of 2026, Allstate, Progressive, and Honeycomb have adopted "hard no" policies for homes with active knob-and-tube, generally requiring modern copper wiring before they will write coverage.


Not every door is closed. State Farm and USAA may offer conditional coverage when a licensed electrician certifies the system is safe, ungrounded, and not buried under insulation. That last point catches a lot of Cleveland owners, because blown-in attic insulation added during an energy upgrade often covers the old wiring.


A common mistake is assuming the wiring is gone because the panel was replaced. A new 200-amp panel can still feed knob-and-tube circuits upstairs. Before you shop, get an electrician to confirm what is actually in the walls and put it in writing. That letter does more for your application than any explanation you can give on the phone.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Comparing Water Backup Coverage Limits

Endorsements come in tiers, and the default limit is often too low for a fully finished space. Match the limit to what's actually down there.

Managing Lake Effect Snow Loads in the East Side Snow Belt

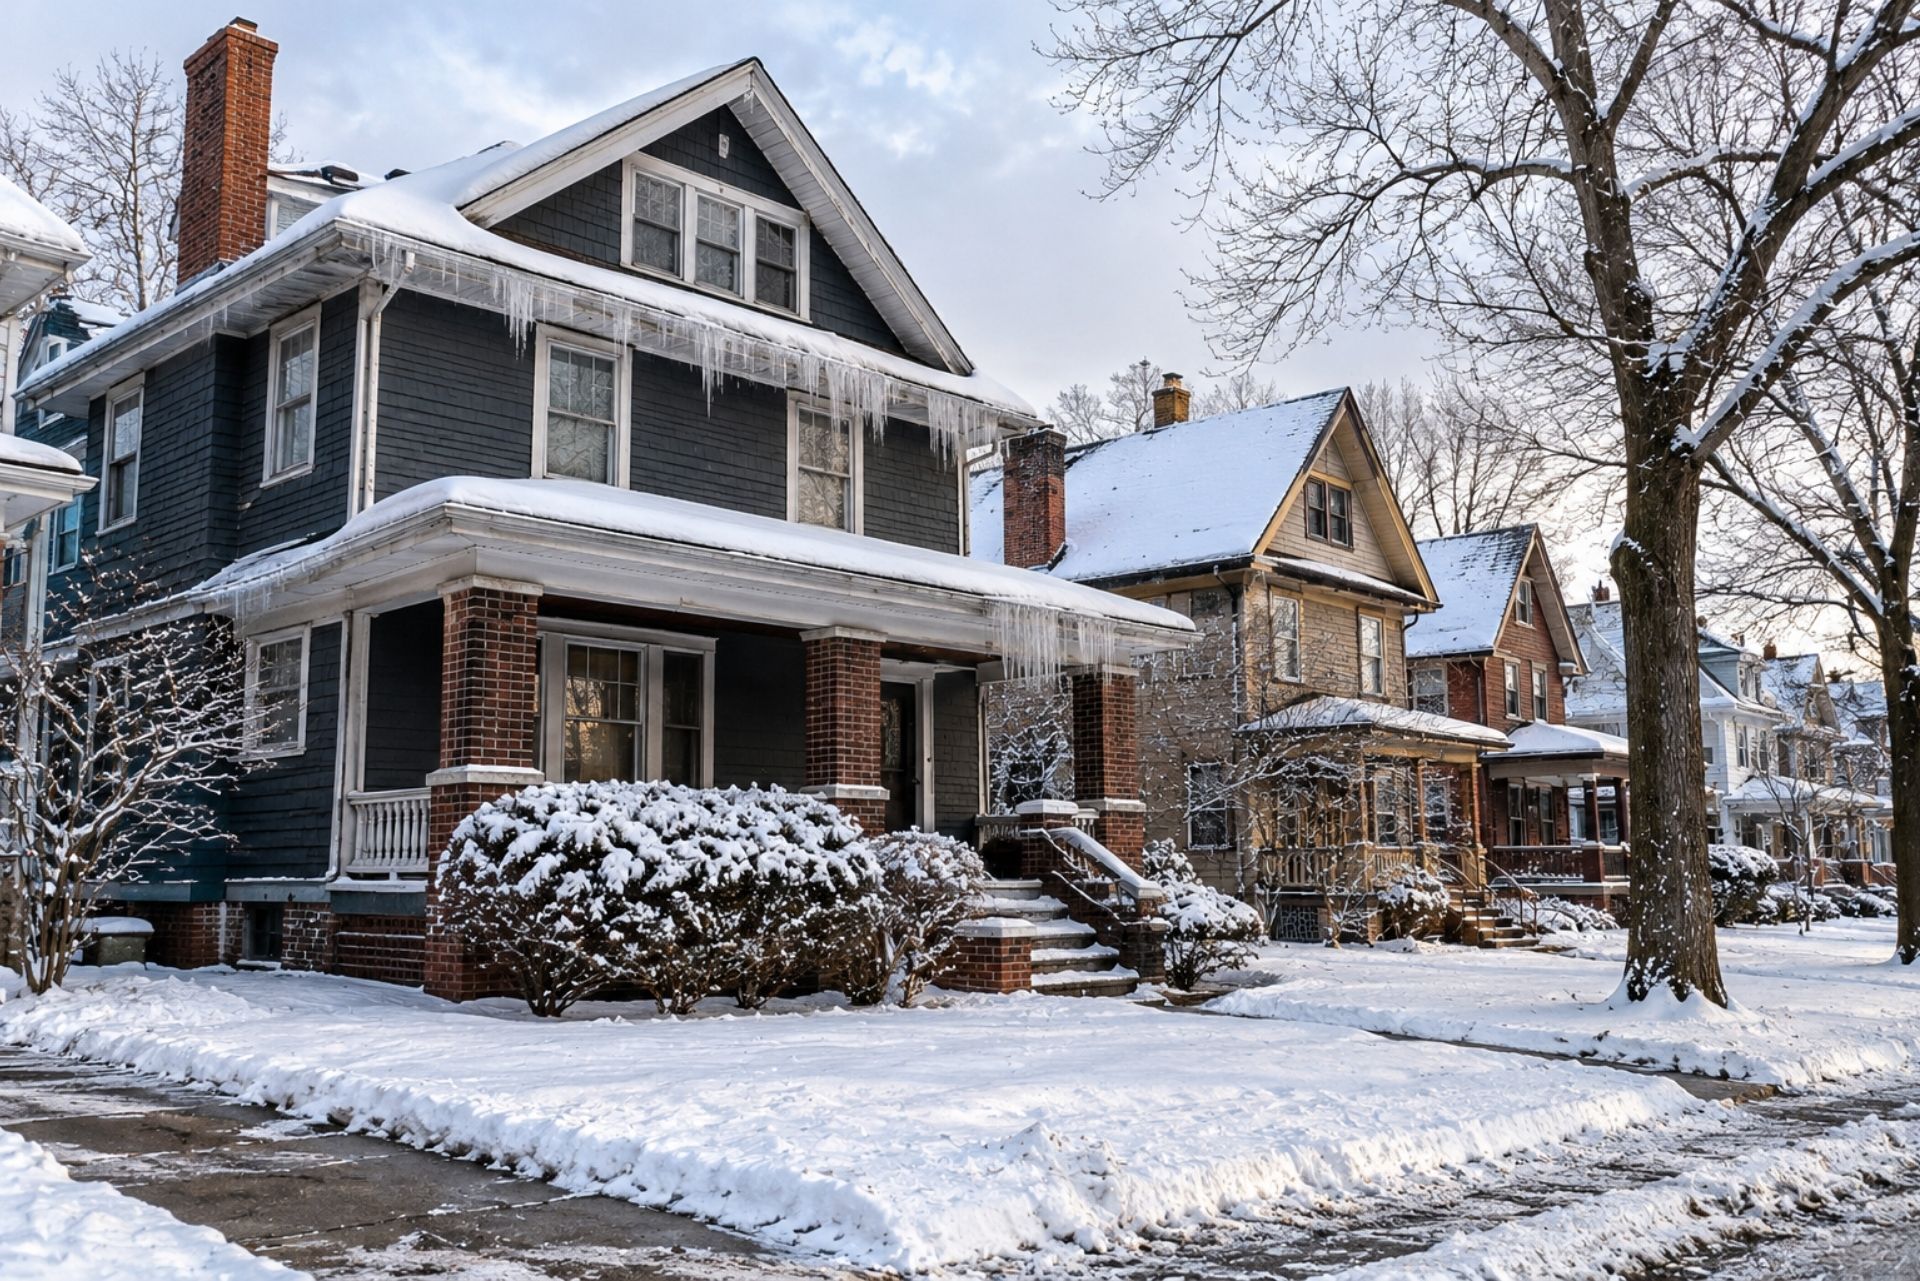
Homes east of Cleveland face heavier, more frequent snow because cold air picks up moisture over Lake Erie and dumps it on the higher ground of the snow belt. Communities toward Geauga and Lake counties can see repeat storms that stack snow and ice on roofs for weeks.


The City of Cleveland uses a ground snow load design criterion of 30 pounds per square foot for regional weather. A house built in 1920 was not designed to modern code, and decades of re-roofing layers can add weight before any snow falls. Undersized rafters, notched joists, and sagging ridgelines all reduce the margin.


Most broad and special form policies cover collapse from the weight of ice, snow, or sleet. The catch is wear and tear. If an adjuster finds rot or long-term deflection, the carrier may argue the roof failed from neglect rather than snow. Ice dams are similar: the resulting interior water damage is usually covered, but repeated leaks you ignored may not be. Keep roof inspection records and clear heavy drifts safely with a roof rake.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella Coverage

An umbrella policy typically kicks in once your underlying auto or home liability is exhausted. Picture a multi-car accident where injuries run well past your auto limit, or a guest seriously hurt on your deck. Umbrellas often cover claims your base policies don't, like certain libel or slander suits. The catch: carriers usually require minimum underlying limits, so your auto and home policies must be set correctly first.

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Preventing and Insuring Against Basement Flooding

Basement water is the most common surprise claim for older Cleveland homes, and a standard policy does not cover most of it. Old clay laterals crack, tree roots intrude, foundation walls seep, and combined sewers back up during heavy rain. The regional sewer district has put more than $150 million into local sewer repairs since 2016 to reduce basement flooding, which tells you how widespread the problem is.


Here is how coverage typically breaks down:


  • Sudden internal water damage (a burst supply line or failed water heater): usually covered under the standard policy.
  • Sewer or drain backup and sump pump failure: excluded unless you add a water backup endorsement.
  • Surface flooding or groundwater seepage: excluded; flood coverage requires a separate flood policy.
  • Long-term seepage through foundation cracks: generally treated as maintenance and not covered.


Water backup endorsements often come with low limits like $5,000 or $10,000. If your basement is finished, that may not cover drywall, carpet, and a furnace. Ask for a higher limit and install a backwater valve or battery backup sump pump.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Bundling makes sense for Ohio families who commute into Pennsylvania. You get one renewal conversation, liability limits that match across policies, and often a multi-policy credit. It also makes room for an umbrella policy, which usually requires matching underlying limits on your home and auto policies.


Start with the details of homeowners coverage in Ohio, then line them up with car insurance for New Springfield drivers. If you drive daily on Route 224 or into Pennsylvania, make sure your vehicle's garaging address and mileage are accurate. A mismatch can complicate a claim.

Addressing Vacant Property Concerns in Older Neighborhoods

Vacancy changes your coverage quickly. Many standard homeowners policies restrict or exclude certain losses, such as vandalism, theft, and glass breakage, once a home has been empty for 30 or 60 consecutive days, depending on the carrier and policy wording. Water damage claims can also be limited if no one was there to notice a leak.


Cleveland's vacancy risks are real. Empty houses attract copper theft, squatters, and arson, and a burst pipe can run for weeks. City officials studying the issue noted that new parcel data "will help us identify where we can apply City resources to ensure the worst ones are dealt with first."


Owners also carry legal duties. Under Ordinance 3106, vacant properties must be registered annually at $70 per unit for 1 to 3 family homes. Owners must complete at least one interior and exterior inspection each month and keep written reports. Effective February 6, 2026, Cleveland stopped requiring the exterior point-of-sale inspection for vacant 1 to 3 unit homes, though rules can change, so confirm before closing. If a house will sit empty during an estate settlement or renovation, ask about a vacancy endorsement or a dedicated vacant dwelling policy before the deadline hits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Comparing Coverage Options for Older Cleveland Homes

The policy form decides which causes of loss are covered, and older homes often get offered narrower forms. Here is how they compare:

Feature Basic Form Broad Form Special Form
Covered perils About 10 named perils (fire, wind, hail, etc.) Basic plus about 6 more All risks unless excluded
Weight of snow/ice Not included Included Included
Burst or frozen pipes Not included Included Included
Plaster and old trim Often actual cash value Varies by carrier Replacement cost possible
Typical for Vacant or high-risk homes Older homes with some updates Well-maintained, updated homes

Special form gives the widest protection, but carriers may limit it on homes with original systems. A broad form with proper endorsements can still serve a 1910s house well if you understand where the gaps are.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Bundling Car Insurance Ohio Cleveland for Maximum Value

Combining your home and auto policies with one carrier usually lowers the total premium and simplifies renewals and claims. For older homes, bundling can also help: a carrier that wants your auto business may be more flexible on a house with partial updates.


The value depends on shopping more than one company. A captive agent can only bundle within a single carrier, so if that carrier won't take your knob-and-tube house, the bundle falls apart. An independent agency compares multiple carriers and finds one that accepts both the home and your vehicles. It's also worth checking whether the bundle actually saves money, since sometimes two separate carriers cost less. You can compare options on our page for car insurance in Cleveland, Ohio.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Frequently Asked Questions About Cleveland Home Insurance

Can I get homeowners insurance with knob-and-tube wiring in Cleveland? Sometimes. Several major carriers now refuse it, while a few may accept it with a licensed electrician's safety certification.


Does homeowners insurance cover sewer backup in my basement? Not by default. You need a water backup endorsement, and you should pick a limit that matches your finished space.


What happens to my coverage if my house sits empty? Many policies limit coverage after 30 or 60 days of vacancy. Call your agent before that point to add vacancy coverage.


Is roof collapse from snow covered? Broad and special form policies usually cover it. Claims can be denied if the roof was already rotted or poorly maintained.


Why is insurance more expensive for an old house? Older systems create more claims, and rebuilding with historic materials costs more. Documented updates often bring the price down.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Contact MVP Insurance for a Comprehensive Policy Review

Older Cleveland homes reward owners who plan ahead. Know what wiring is in your walls, add backup coverage before the next storm, keep roof records for snow belt winters, and never let a vacant house slip past its coverage deadline. Those steps turn a hard-to-insure property into one that underwriters will accept.


MVP Insurance is an independent agency founded in 2008 by Josh Medure and David Varrati, with offices at 108 E Grandview Ave in Zelienople, PA ((724) 453-1122) and 13823 Grant St in New Springfield, OH ((330) 707-9055). We are licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. Because we work for you rather than one carrier, we compare policies across companies to find coverage that fits a century-old home.


If your house has history, let us do the comparison legwork. Start your quoteand we'll review your current policy for gaps before your next claim finds them for you.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








