


Pennsylvania Commercial Property Insurance

Owner, MVP Insurance

Pennsylvania commercial property insurance pays to repair or replace the things your business physically depends on: the building, the equipment inside it, and the inventory on your shelves. It can also replace lost income while you're closed for repairs. For Pennsylvania owners, the details that matter most are winter damage and the true cost of rebuilding an older storefront.


Those details are where claims get decided. A policy can look complete on paper and still leave a Main Street retailer short after a February roof collapse. It can also pay a fraction of what a 1920s brick building actually costs to rebuild. The sections below cover where coverage tends to break down and how to close those gaps before you need them.

Essential Pennsylvania Commercial Property Insurance for Buildings and Assets

At its core, commercial property coverage protects your physical assets (buildings, equipment and inventory) from risks like fire, theft, vandalism, wind and certain natural disasters. If you own your building, the policy covers the structure itself. If you lease, you still need coverage for your contents and any improvements you've paid for, such as new flooring, lighting or a built-out kitchen.


Many smaller operations bundle property and liability into a business owners policy in Pennsylvania,which often costs less than buying each piece separately. Larger or more specialized risks may need standalone property forms with higher limits. The broader picture of what a PA company typically carries is laid out on our Pennsylvania business insurancepage.


MVP Insurance works with business owners in Zelienople, New Springfield and the surrounding region to match coverage to how they actually operate. A machine shop in Butler County and a café in Lawrence County face very different exposures. As an independent agency, we compare multiple carriers instead of steering you toward one.

David Varrati

By: Joshua Medure

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page
Life

Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.

Protecting Your Equipment and Inventory from Loss

Equipment and inventory fall under "business personal property," and this is where many owners guess low. The usual mistake is setting a limit years ago and never revisiting it. That leaves out the new espresso machine, the second CNC unit or a seasonal inventory build that doubles stock every November.


Here's what to check on your current policy:


  • Limit accuracy: Walk through your space and total the replacement value of everything you'd need to reopen, including computers, furniture, tools and stock.
  • Peak season coverage: Ask about a seasonal increase endorsement if inventory swings during the holidays or a busy harvest season.
  • Equipment breakdown: Standard property forms usually exclude mechanical or electrical breakdown. A failed compressor in a walk-in cooler needs this separate coverage.
  • Off-premises property: Tools in a truck or goods at a trade show may need an inland marine policy.
  • Spoilage: Restaurants and grocers should confirm whether food spoilage from a power outage is covered.


Keep photos and receipts in cloud storage, not just in the building that might burn.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Business Income After a Shutdown

Business income coverage pays your lost profits and continuing fixed expenses while you're closed to repair damage from a covered loss. It covers rent, loan payments, payroll you choose to keep, and the net income you would have earned. If you came here from our old Commercial Interruption page, this is the same coverage under its current name.


Picture a fire in a neighboring unit that forces your bakery to close for four months. The property side of your policy fixes the ovens and walls. Business income keeps the lights on financially, so you don't lose your best employees to a competitor while contractors work.


One nuance trips people up. Commercial forms typically define the "period of restoration" as the time it should take to repair the property with "reasonable speed." That standard doesn't always match reality when supply chains slow down a specialty part or a contractor's schedule. Ask for an extended period of indemnity, which covers the slow ramp back up after reopening. Also choose a time limit that reflects realistic rebuild timelines, not best-case ones.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Winter Freeze and Roof Collapse Claims

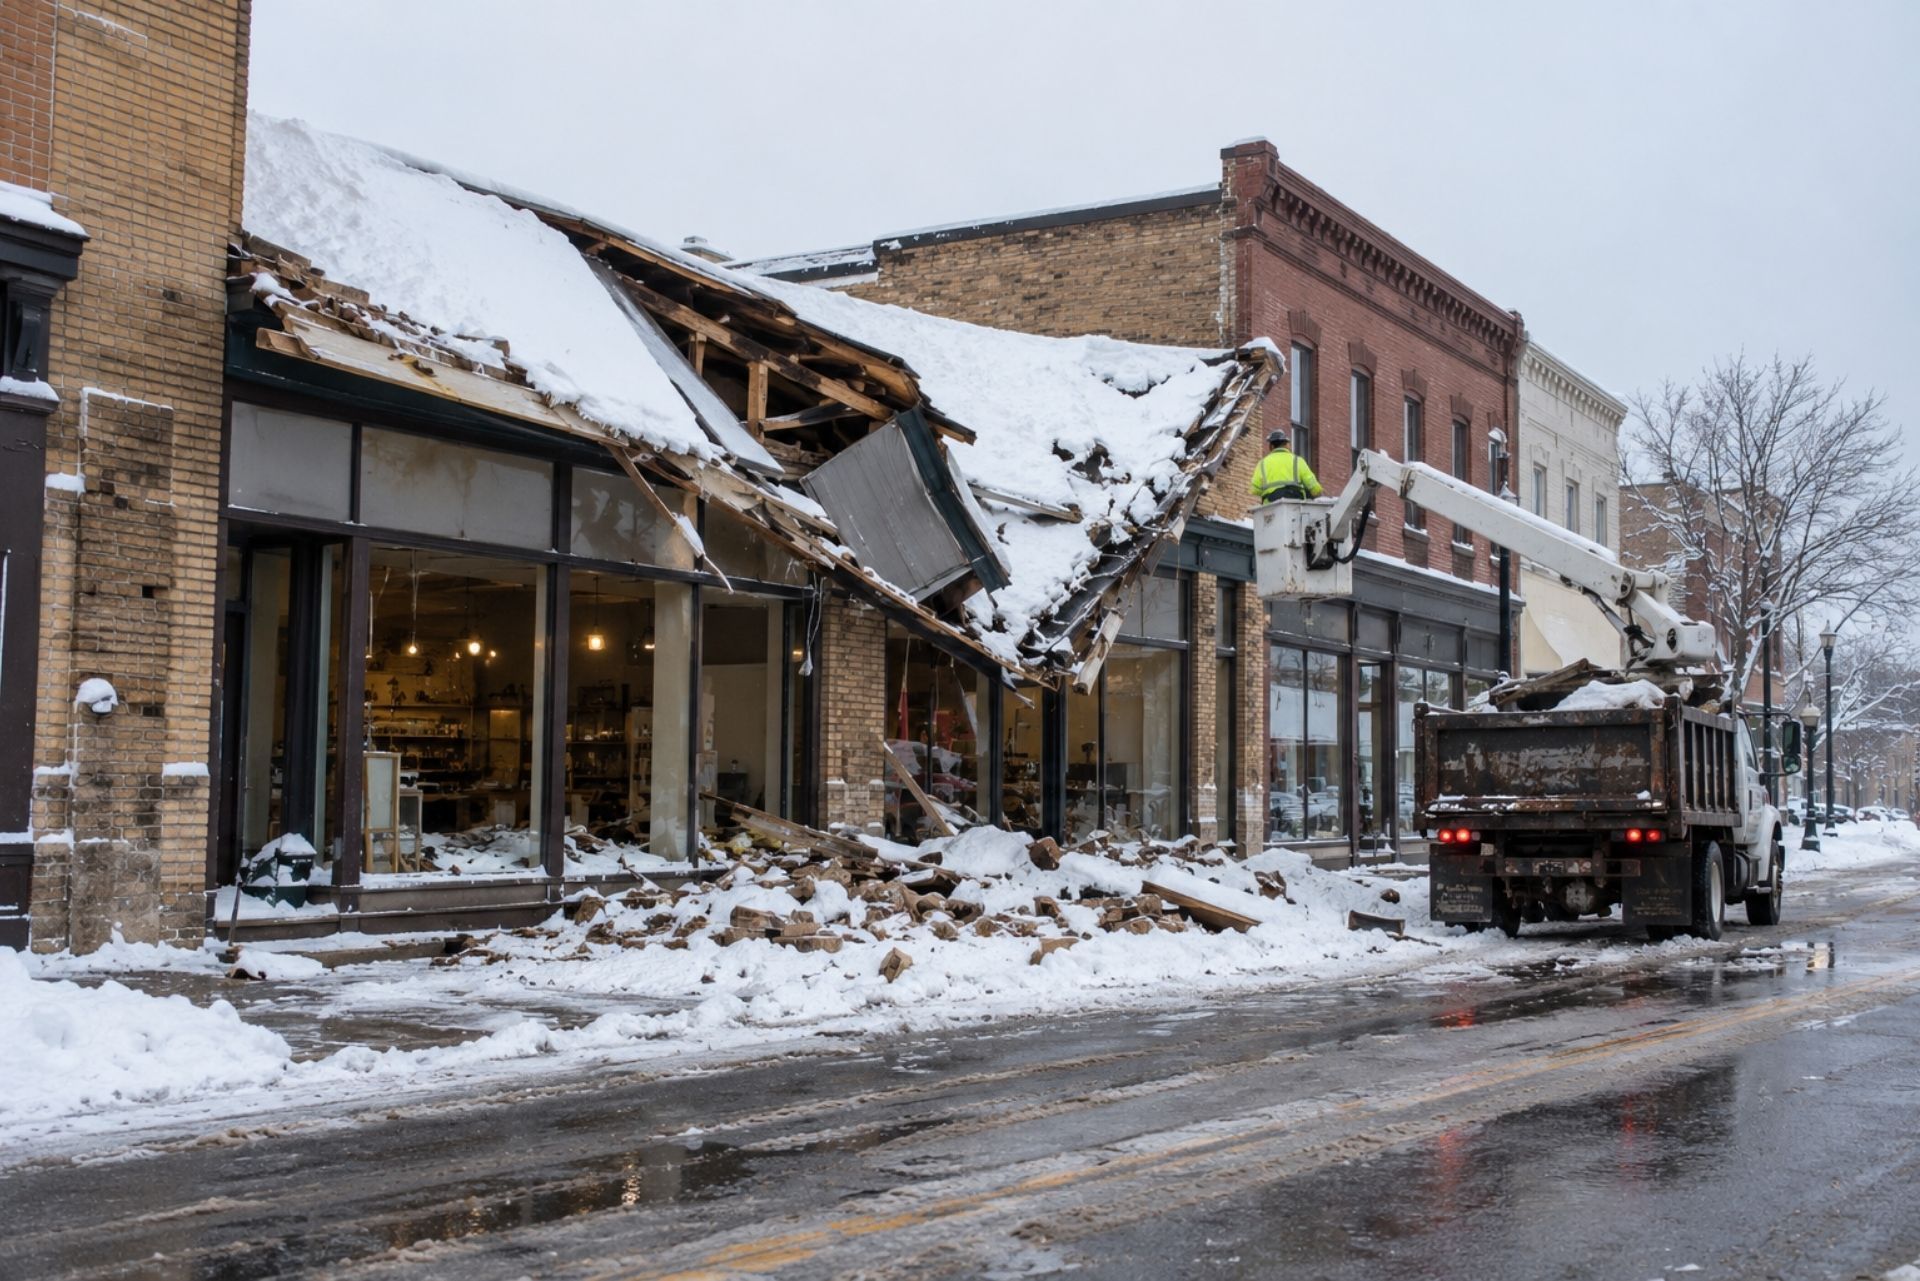
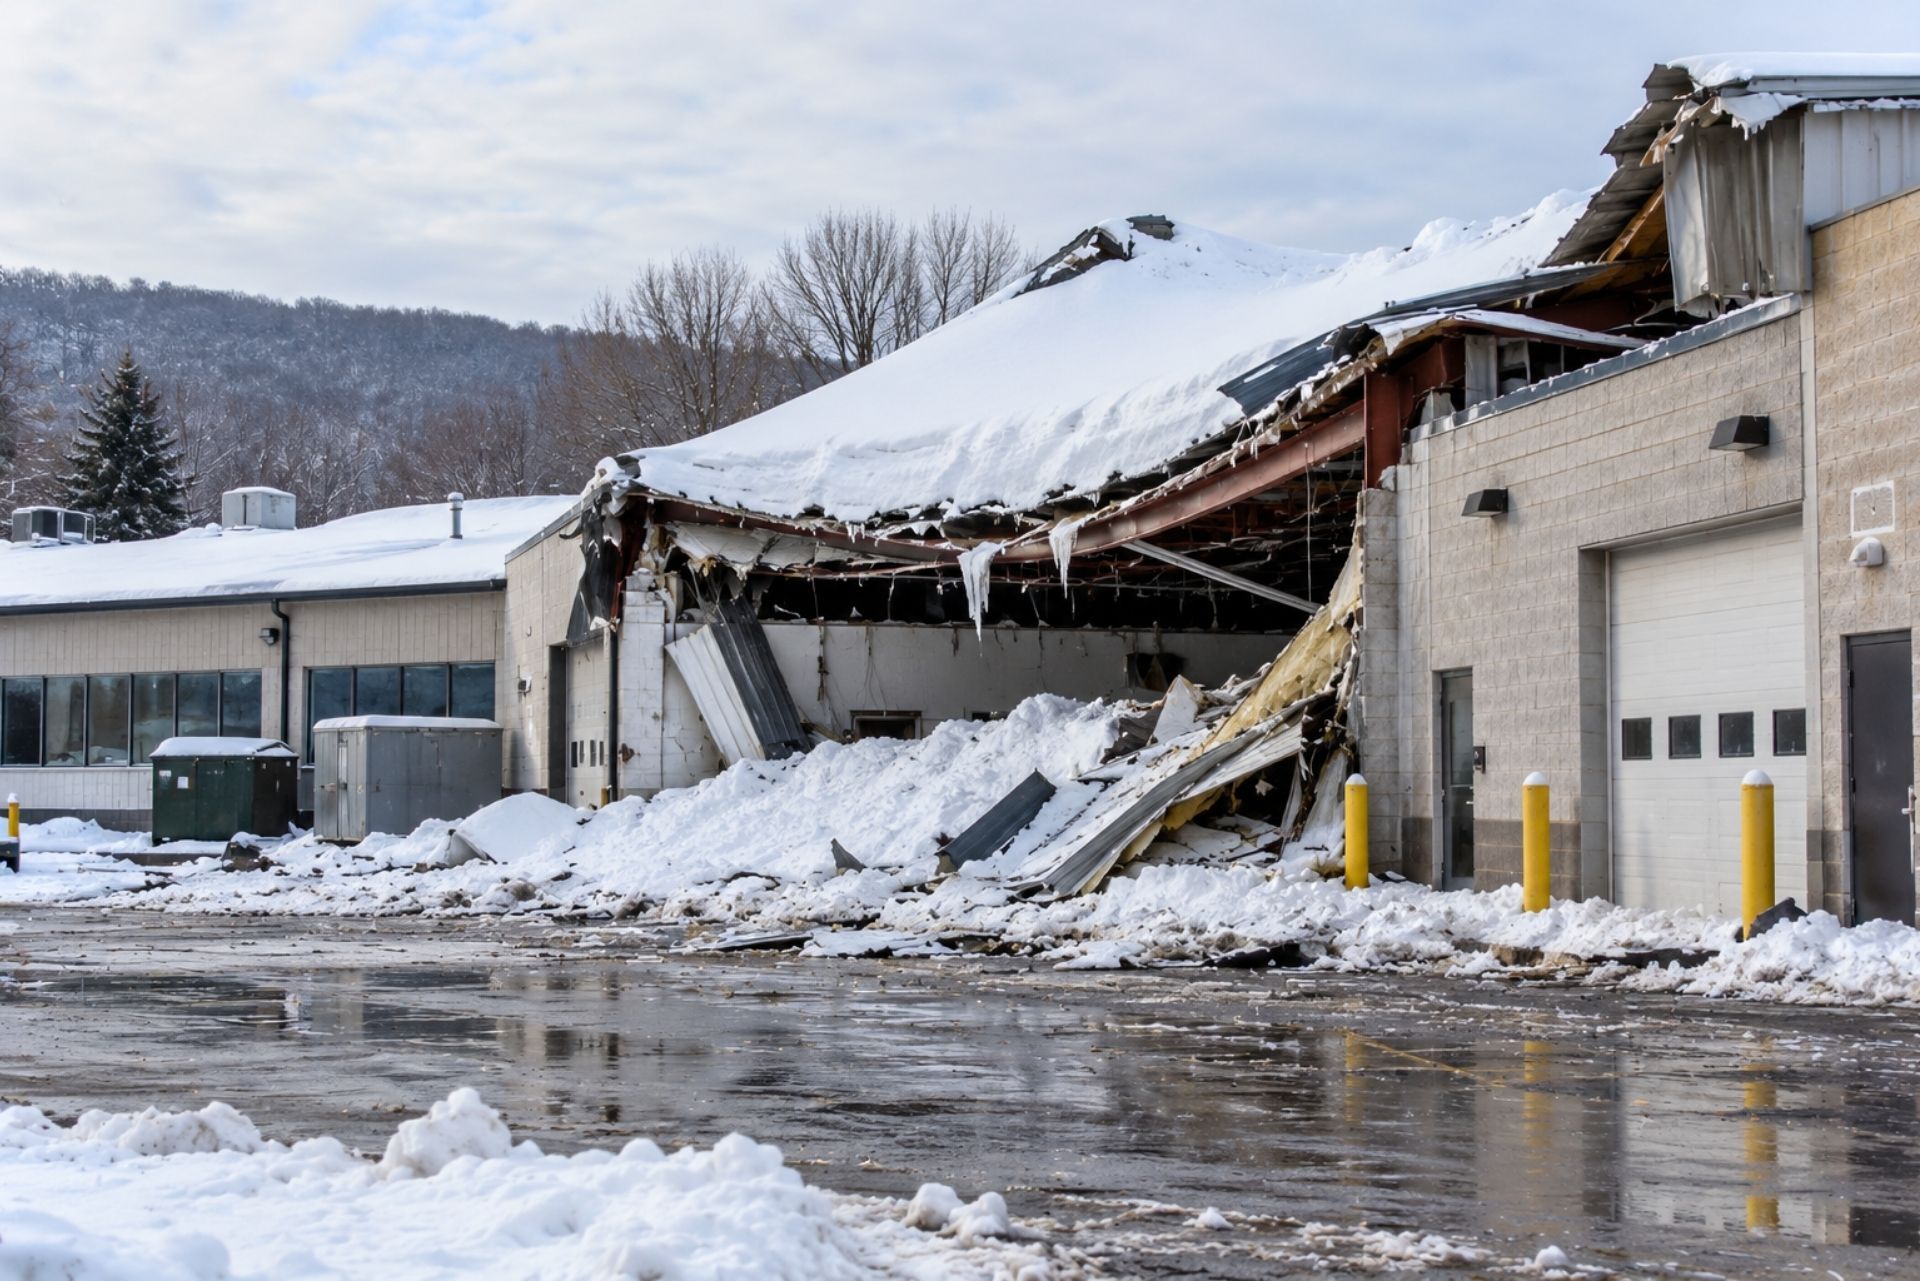
Pennsylvania winters create two of the most expensive claim types we see: roofs collapsing under snow load and frozen pipes bursting inside sprinkler systems. Both are generally covered perils on most commercial property forms. Exclusions and conditions vary by policy, though, so confirm the wording on yours.


Snow load collapses tend to hit flat or low-slope roofs on older commercial buildings, especially after heavy wet snow followed by rain. Roof claims have become far more costly. Average residential and small commercial roof replacement costs in the Northeast rose 33% in 2025 compared with the prior four-year average. Roof claim severity has hit record highs even in years with fewer storms. If your building limit hasn't moved in three years, it may be well behind current costs.


Frozen sprinkler pipes are the quieter disaster. A dry-pipe system with trapped water or a wet system in an unheated stairwell can split overnight and soak inventory across several floors. Many policies require you to maintain heat or drain the system, and failing to do so can jeopardize a freeze claim. Keep the thermostat on during holiday closures, and document your sprinkler inspections.


During the claim itself, Pennsylvania insurers can't automatically withhold contractor overhead and profit from advance payments just because repairs aren't finished yet. Know that before you accept a first check.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Replacement Cost on Older Storefronts

Replacement cost coverage pays to rebuild with materials of similar kind and quality, without subtracting depreciation. On older brick storefronts, that still isn't enough. Rebuilding a century-old building means meeting today's code, not the code from 1925.


Actual cash value policies subtract depreciation, which can leave owners of older buildings with a payout that covers a fraction of the work. Replacement cost is almost always the stronger choice for an owner-occupied storefront. Even replacement cost has a ceiling, however, and that ceiling is the building as it existed.

Ordinance or Law Coverage for Main Street Buildings

Standard policies typically pay to rebuild a building "as-is." That's why Pennsylvania's aging storefronts often need Ordinance or Law coverage: it fills the gap between the old structure and what current municipal codes demand. Think of a two-story brick building on a main street in Zelienople, Grove City or Beaver. After a fire, the borough may require sprinklers, ADA-compliant entrances, updated electrical and new egress stairs.


Ordinance or law coverage usually comes in three parts:


  • Coverage A: Loss to the undamaged portion of a building that code requires you to tear down.
  • Coverage B: Demolition and debris removal costs for that undamaged portion.
  • Coverage C: The increased cost to build to current code.


Owners often skip Coverage C or choose a low limit. On an older storefront, code upgrades alone can run into six figures, so set that limit with a contractor's input.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Claims and credit where allowed

Comparing Pennsylvania Property Coverage Options

The right mix depends on whether you own or lease, how old your building is, and how long you could survive closed. This table shows how the main pieces compare.

Coverage What It Pays For Who Needs It Most
Building (replacement cost) Rebuilding without depreciation Owners of their building
Building (actual cash value) Rebuilding minus depreciation Rarely ideal for occupied buildings
Business personal property Equipment, furniture, inventory Owners and tenants
Business income Lost profit and fixed costs during closure Anyone who can't operate remotely
Equipment breakdown Mechanical and electrical failure Restaurants, manufacturers, medical offices
Ordinance or law Code upgrades and demolition Older storefronts and historic buildings
Spoilage Perishable goods lost to outages Food service and grocers

Most clients don't need everything on this list. A dental office in a newer plaza might skip ordinance or law but need strong equipment breakdown limits. A family hardware store in a 1910 building needs nearly every row. A review of your policy against your actual building and operations is where the real gaps show up.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Frequently Asked Questions About PA Business Property Coverage

Does commercial property insurance cover a roof collapse from snow? In most cases, yes, collapse from the weight of snow or ice is a covered cause of loss. Check your policy for maintenance conditions and any exclusions on older roofs.


Are frozen sprinkler pipes covered by my business insurance? Usually, as long as you kept the building heated or properly drained the system. Neglecting heat can lead to a denied claim.


What's the difference between replacement cost and actual cash value? Replacement cost pays to rebuild with no deduction for age. Actual cash value subtracts depreciation, so you get less money for older property.


Do I need property insurance if I rent my storefront? Yes. Your landlord's policy covers the building, not your equipment, inventory or the improvements you paid for.


How long does business income insurance pay? It pays during the period of restoration, which is the time it should reasonably take to repair the damage. An extended period of indemnity can add coverage after you reopen.


Is ordinance or law coverage included automatically? Often only a small amount is included, if any. Older buildings usually need it added with higher limits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Claims and credit where allowed

Coverage What It Pays For Who Needs It Most
Building (replacement cost) Rebuilding without depreciation Owners of their building
Building (actual cash value) Rebuilding minus depreciation Rarely ideal for occupied buildings
Business personal property Equipment, furniture, inventory Owners and tenants
Business income Lost profit and fixed costs during closure Anyone who can't operate remotely
Equipment breakdown Mechanical and electrical failure Restaurants, manufacturers, medical offices
Ordinance or law Code upgrades and demolition Older storefronts and historic buildings
Spoilage Perishable goods lost to outages Food service and grocers

Contact MVP Insurance for a Commercial Property Review

The biggest surprises in commercial property claims are rarely about whether something is covered. They come from limits that fell behind rising roof costs, missing code upgrade coverage on an old brick building, or a business income period that ran out before the contractor finished. Each of those is fixable before a loss, and much harder to fix after one.


Josh Medure and David Varrati founded MVP Insurance in 2008 as an independent agency, so we work for you, not the carrier. Call our Zelienople office at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122. You can also reach our New Springfield office at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055, to schedule a policy review. We'll walk through your building, equipment, inventory and income exposure with you. Then we'll compare options from multiple carriers. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


If you'd rather start online, you can request your quote hereand we'll follow up with options built around your property. Before the next snowstorm rolls in, take thirty minutes to confirm your roof, your pipes and your limits are ready for it.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

Joshua Medure

Owner, MVP Insurance


I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania







