


Owner, MVP Insurance
Zelienople business owners usually need four core protections: property coverage that fits the building they occupy (including older or historic structures), general liability for customer injuries and property damage, workers compensation once they hire, and coverage designed for their trade. Retailers, restaurants and contractors each need a different mix, and the right blend depends on your building, staff and daily risks.
Downtown Zelie has changed a lot in a short time. Shops that once relied on regulars now see crowds during market weekends and summer festivals, and that growth brings new exposures. Here is how a sensible commercial insurance plan comes together for a Butler County business.
Zelienople PA Business Insurance for Main Street Retailers and Restaurants
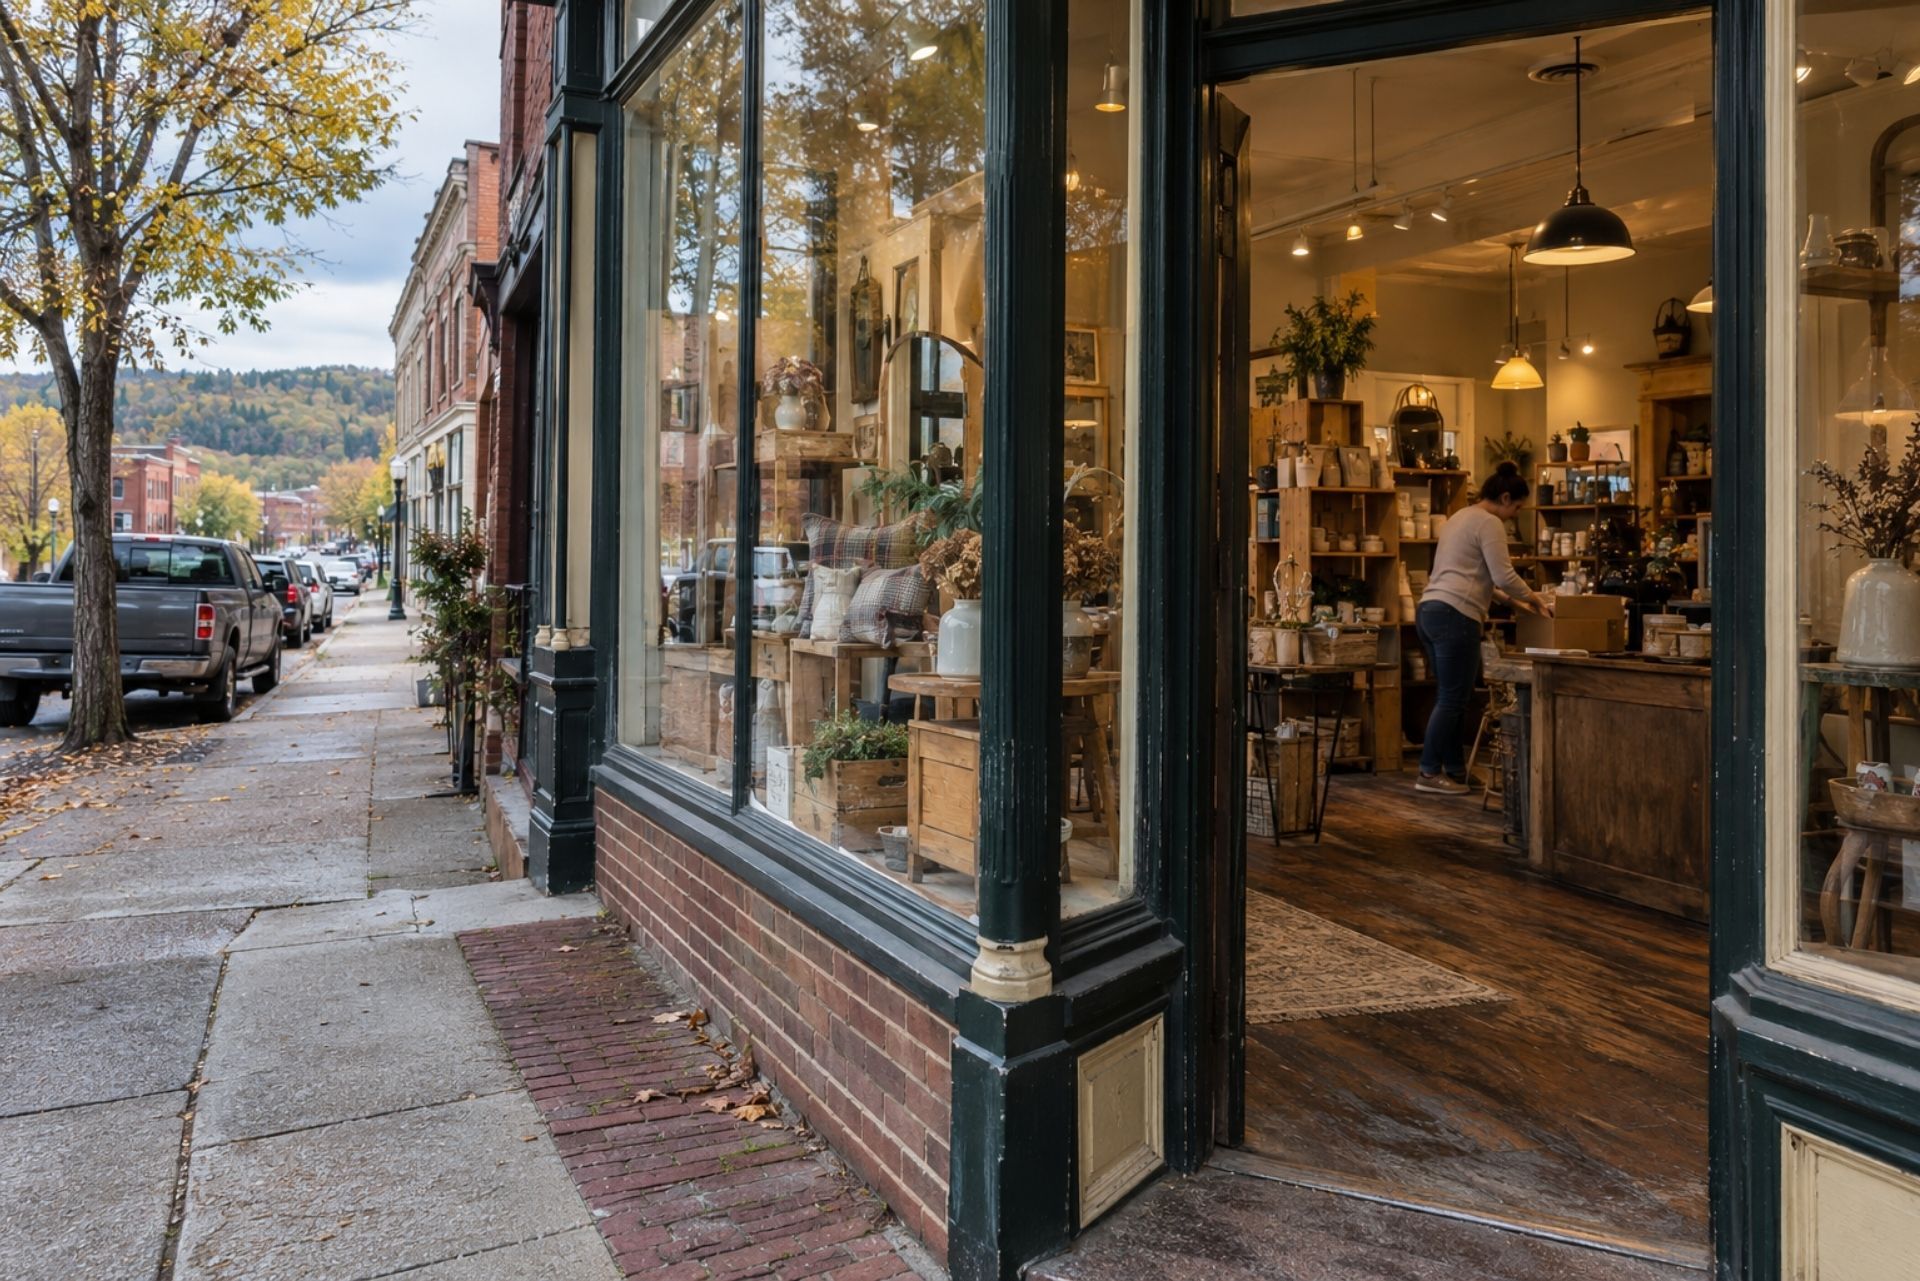
Main Street retailers and restaurants in Zelienople need coverage that matches heavier foot traffic, older storefronts and seasonal swings in inventory and staffing. MVP Insurance builds those policies from our office at 108 E Grandview Ave, just a few blocks from the shops and eateries we insure.
The downtown has earned its new reputation. Joel Grobe, president of the local business association, said revitalization has turned the district from a "jewel in the rough" into a vibrant destination for specialty shops and restaurants. The borough also finished Phase 2 of its downtown project in September 2026, upgrading sidewalks, curbs and electrical components on Main Street. More visitors means more chances for a slip at your entrance or a dropped plate turning into an injury claim.
Event weekends deserve special attention. Gatherings like the Open Air Market and Horse Trading Days (July 16 to 18) bring sidewalk sales, pop-up tents and extra temporary help. A common mistake we see is a shop setting up merchandise outside without confirming that its liability policy extends to that area, or a restaurant hiring weekend staff without updating payroll on its workers comp policy.
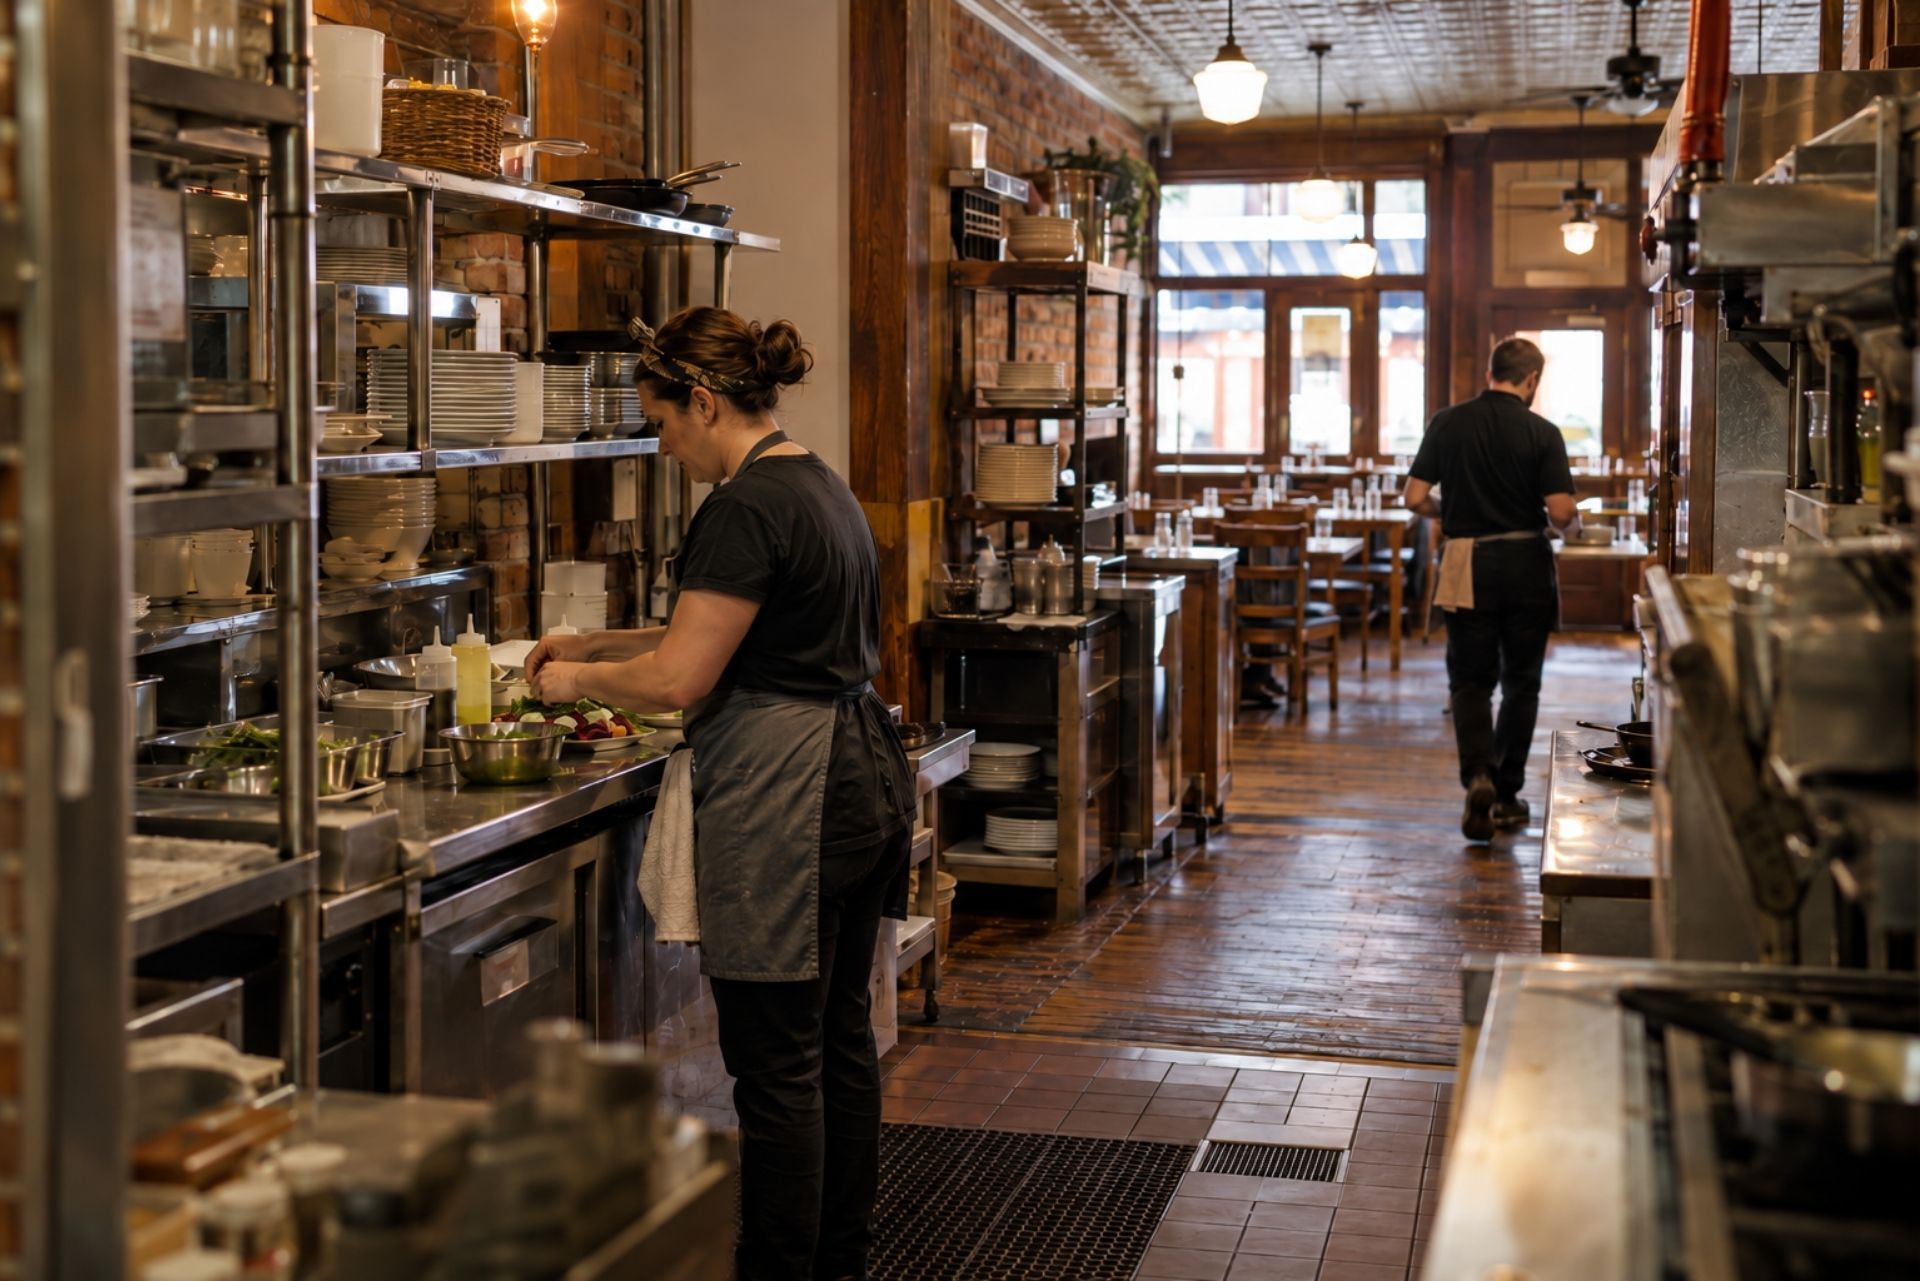
Restaurants carry some extra risks that a generic package often misses:
- Spoilage coverage for food lost when a cooler fails or power goes out
- Liquor liability if you serve alcohol, since standard general liability usually excludes it
- Equipment breakdown for walk-ins, fryers and HVAC units
Shops and eateries near Connoquenessing Creek should also ask about flood coverage, which standard commercial property policies typically exclude. Families from across the Seneca Valley School District shop downtown, and your coverage should keep up with that steady traffic.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page

Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
| Feature | DP-1 (Basic) | DP-3 (Special) |
|---|---|---|
| Covered perils | Named perils only | All risks, minus exclusions |
| Building settlement | Usually actual cash value | Usually replacement cost |
| Sudden water damage | Often excluded | Usually covered |
| Theft/vandalism | Optional, limited | Typically included |
| Loss of rent | Often optional | Usually included |
| Liability | Often an add-on | Add-on or included |
| Best fit | Older, low-value homes | Most modern rentals |
| PA legal requirement | None by state law | None by state law |
Protecting Historic Property and Buildings in Butler County
If your business operates in an older or historic building, you need property coverage built around restoration costs and current building code requirements, not just a basic replacement value. Many Zelienople storefronts share architectural roots with the neighboring Harmony National Historic Landmark District, and those buildings rarely cost the same to repair as modern construction.
Think about what a fire in a 19th-century brick building actually requires. You may need hand-matched brick, custom millwork, period windows and craftsmen who know the materials. A policy written at the wrong value can leave you tens of thousands of dollars short after a serious loss, and this is one of the most frequent gaps we find when reviewing policies written years ago.
Code upgrades are the other trap. When an older building is damaged, rebuilding often triggers modern electrical, sprinkler or accessibility requirements that the original structure never had. Standard property forms usually pay to restore what was there, not what the code now demands. Ordinance or law coverage fills that gap, and owners of heritage buildings should treat it as essential.
Tenants have their own responsibilities. If you lease space, read your lease for who insures improvements like custom counters, lighting and flooring. Those "tenant improvements" often fall on you, even though the landlord owns the building. Business income coverage also matters here, because historic restorations can take far longer than a standard rebuild, and rent and payroll keep coming due in the meantime.

Written By
David Varrati
Owner, MVP Insurance
On this page
HCertificates of Insurance for Pennsylvania Contracts
Canopy import
Share your current policies in a few clicks through Canopy. We see exactly what you have today, so the comparison is apples to apples.
General Liability and Workers Comp for Butler County Employers
General liability protects you against third-party claims, such as a customer injury or damage to someone else's property, while workers compensation covers employees hurt on the job and is required by Pennsylvania law for most businesses with employees. Together, they form the foundation of almost every commercial insurance plan we write.
General liability handles the claims most owners picture first: a customer trips on a rug, a delivery driver falls on an icy step, or your product damages a client's property. It typically pays legal defense costs too, which can run high even when a claim has little merit. What it does not cover is equally important. Your own employees' injuries, professional mistakes and vehicle accidents all need separate policies.
Workers comp in Pennsylvania generally applies once you have even one employee, including part-timers and seasonal help. The cost picture has improved recently: the state Insurance Department approved a 1.22% decrease in workers' compensation loss costs effective April 1, 2026. Loss costs are only one ingredient in your premium, though, so your actual rate still depends on your classification codes, payroll and claims history.
A mistake we correct often is misclassified payroll. If a cafe lists every worker as clerical when several are cooking, an audit can produce a surprise bill months later. Keeping payroll accurate and updated protects you from that headache.
Insurance Solutions for Local Trades and Contractors
Plumbers, electricians, roofers, landscapers and general contractors around Butler County face a different set of risks than storefront businesses. Many jobs require a certificate of insurance before you can start, and general contractors frequently ask to be named as additional insureds on your policy.
Contractors should look closely at several coverages:
- Completed operations for claims that show up after the job is finished
- Inland marine or tools coverage for equipment stored in trucks or on job sites
- Commercial auto for work vehicles, since personal auto policies often exclude business use
If you hire subcontractors, collect their certificates every time. Otherwise, your workers comp carrier may charge you for their payroll at audit.
Comparing Essential Pennsylvania Business Insurance Coverage
Most Butler County employers end up with some combination of the coverages below. The table shows what each one does, who usually needs it and whether Pennsylvania requires it.
| Coverage | What It Covers | Who Needs It | Required in PA? |
|---|---|---|---|
| General Liability | Third-party injuries and property damage | Nearly every business | Not by state law, often by leases and contracts |
| Workers Compensation | Employee medical costs and lost wages | Businesses with employees | Yes, for most employers |
| Commercial Property | Building, inventory, equipment | Owners and tenants with contents | No, but lenders usually require it |
| Ordinance or Law | Code upgrade costs after a loss | Owners of older or historic buildings | No |
| Business Income | Lost income and ongoing expenses during repairs | Businesses that would close after a loss | No |
| Liquor Liability | Claims tied to serving alcohol | Restaurants and bars that serve alcohol | Often required for licensing or leases |
| Commercial Auto | Vehicles used for business | Contractors and delivery businesses | Yes, minimum auto liability for registered vehicles |
Limits are usually set per occurrence and in total for the policy year, and the right numbers depend on your contracts, lease terms and assets. A Business Owners Policy can bundle general liability, property and business income for many small shops, which often simplifies things. You can compare these options in more detail on our Pennsylvania business insurance page.
Frequently Asked Questions About Zelienople Business Insurance
Do I need business insurance if I run a small shop in Zelienople? Pennsylvania does not require general liability by law, but most landlords and lenders do. If you have employees, workers compensation is generally required.
Does my business insurance cover flooding? Standard commercial property policies usually exclude flood. Businesses near Connoquenessing Creek should ask about a separate flood policy.
Do part-time or seasonal workers need workers comp?Yes, in most cases. Pennsylvania counts part-time and seasonal employees, so add festival or holiday help to your payroll estimate.
Will my personal car insurance cover my work truck?Often it won't if the vehicle is used mainly for business. Contractors usually need commercial auto, and you can review personal options on our Zelienople car insurance page.
Why does my historic building cost more to insure?Restoring older materials and meeting modern building codes after a loss costs more than standard repairs. Your policy should reflect those higher rebuilding costs.
Can an independent agent help me compare policies?Yes. An independent agency shops multiple carriers for you, so you can compare coverage and price without calling each company yourself.
Contact MVP Insurance in Zelienople for a Policy Review
The strongest commercial plans in Zelienople start with honest answers about your building, your staff and the way you actually do business. A shop in a century-old storefront, a busy restaurant on Main Street and a roofing crew working across Butler County each need different protection, and a review is the fastest way to find gaps before a claim does.
Josh Medure and David Varrati founded MVP Insurance in 2008, and our Zelienople office at 108 E Grandview Ave (formerly Griffin Insurance) serves business owners throughout the area. Stop by, or call (724) 453-1122 to talk through your coverage with someone who knows the community. Because we're 100% independent, we work for you and shop multiple carriers, and our 24/7 claims service means help is available when something goes wrong.
When you're ready, start your quoteand let us handle the comparison legwork. We also serve Ohio clients from our New Springfield office at 13823 Grant St, (330) 707-9055. MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
Joshua Medure
Owner, MVP Insurance
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.












