

Owner, MVP Insurance
Few places in Pennsylvania put a house through a winter quite like Erie does. Snow piles up fast off the lake, wind hits the shoreline hard, and many of the city's older homes were built long before modern insulation and plumbing standards. If you own property here, your policy needs to match that reality, not a generic statewide template.
Erie PA Homeowners Insurance for Winter Hazards
Erie PA homeowners insurance has to account for heavy lake effect snow, strong winds off the water near Presque Isle, and specific risks like ice dams and frozen pipes in older homes. MVP Insurance, an independent agency with offices in Zelienople, PA and New Springfield, OH, helps Erie-area owners compare policies built around those exposures.
Most standard HO-3 policies cover a lot of winter damage, but the details decide whether a claim gets paid. The policy language around "gradual deterioration," "failure to maintain heat," and "surface water" causes more denied winter claims than anything else we see. A roof that caves in under snow is usually covered. A roof that leaked slowly for three seasons usually is not.
Costs matter too. Pennsylvania homeowners saw a cumulative 44% increase in insurance premiums between 2021 and 2024, the fourth-highest jump in the country. That pressure makes it tempting to raise deductibles or drop endorsements without thinking through what a February in Erie can do.
Erie's weather in 2026 also showed that the risk isn't only a winter problem. The City of Erie declared a State of Emergency on September 3, 2026after severe storms caused widespread wind damage and downed trees. If you're shopping coverage across the state, our overview of homeowners insurance in Pennsylvaniaexplains the base policy structure before you add Erie-specific protection.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Lake Effect Snow Loads and Roof Collapse Coverage
Yes, standard homeowners policies usually cover damage caused by the weight of ice and snow, including partial or full roof collapse. That matters in Erie, which averages heavy lake effect snow each winter and can pick up a foot or more in a single band while towns a few miles inland get a dusting.
Snow load damage shows up in a few common ways:
- Sagging rafters or trusses that crack under sustained weight
- Collapsed porch roofs and carports, which often have lighter framing than the main house
- Detached garage failures, covered under "other structures" (Coverage B), which typically carries a lower limit than the dwelling
- Interior damage to ceilings, drywall, and belongings when the roof gives way
The catch is cause of loss. Insurers look for sudden failure from weight. If an adjuster finds rotted decking or framing that was already compromised, they may argue the collapse came from neglect. Photos of your roof and attic taken each fall give you a record that the structure was sound going into the season.
Neighborhoods around Gannon University downtown and Mercyhurst University on the east side are full of older two-story homes, rental conversions, and add-on porches. Those add-ons are where we see collapse claims most often, because they were frequently built to looser standards than the original house.
One more practical point: local adjusters sometimes provide initial snow-load estimates using outdated pricing. Homeowners often have to file Xactimate supplements to get full repair costs covered. Don't accept a first estimate that won't pay for current lumber and labor rates. Get a contractor's written quote and ask for a supplement if the numbers don't line up.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Preventing and Insuring Ice Dams in Erie
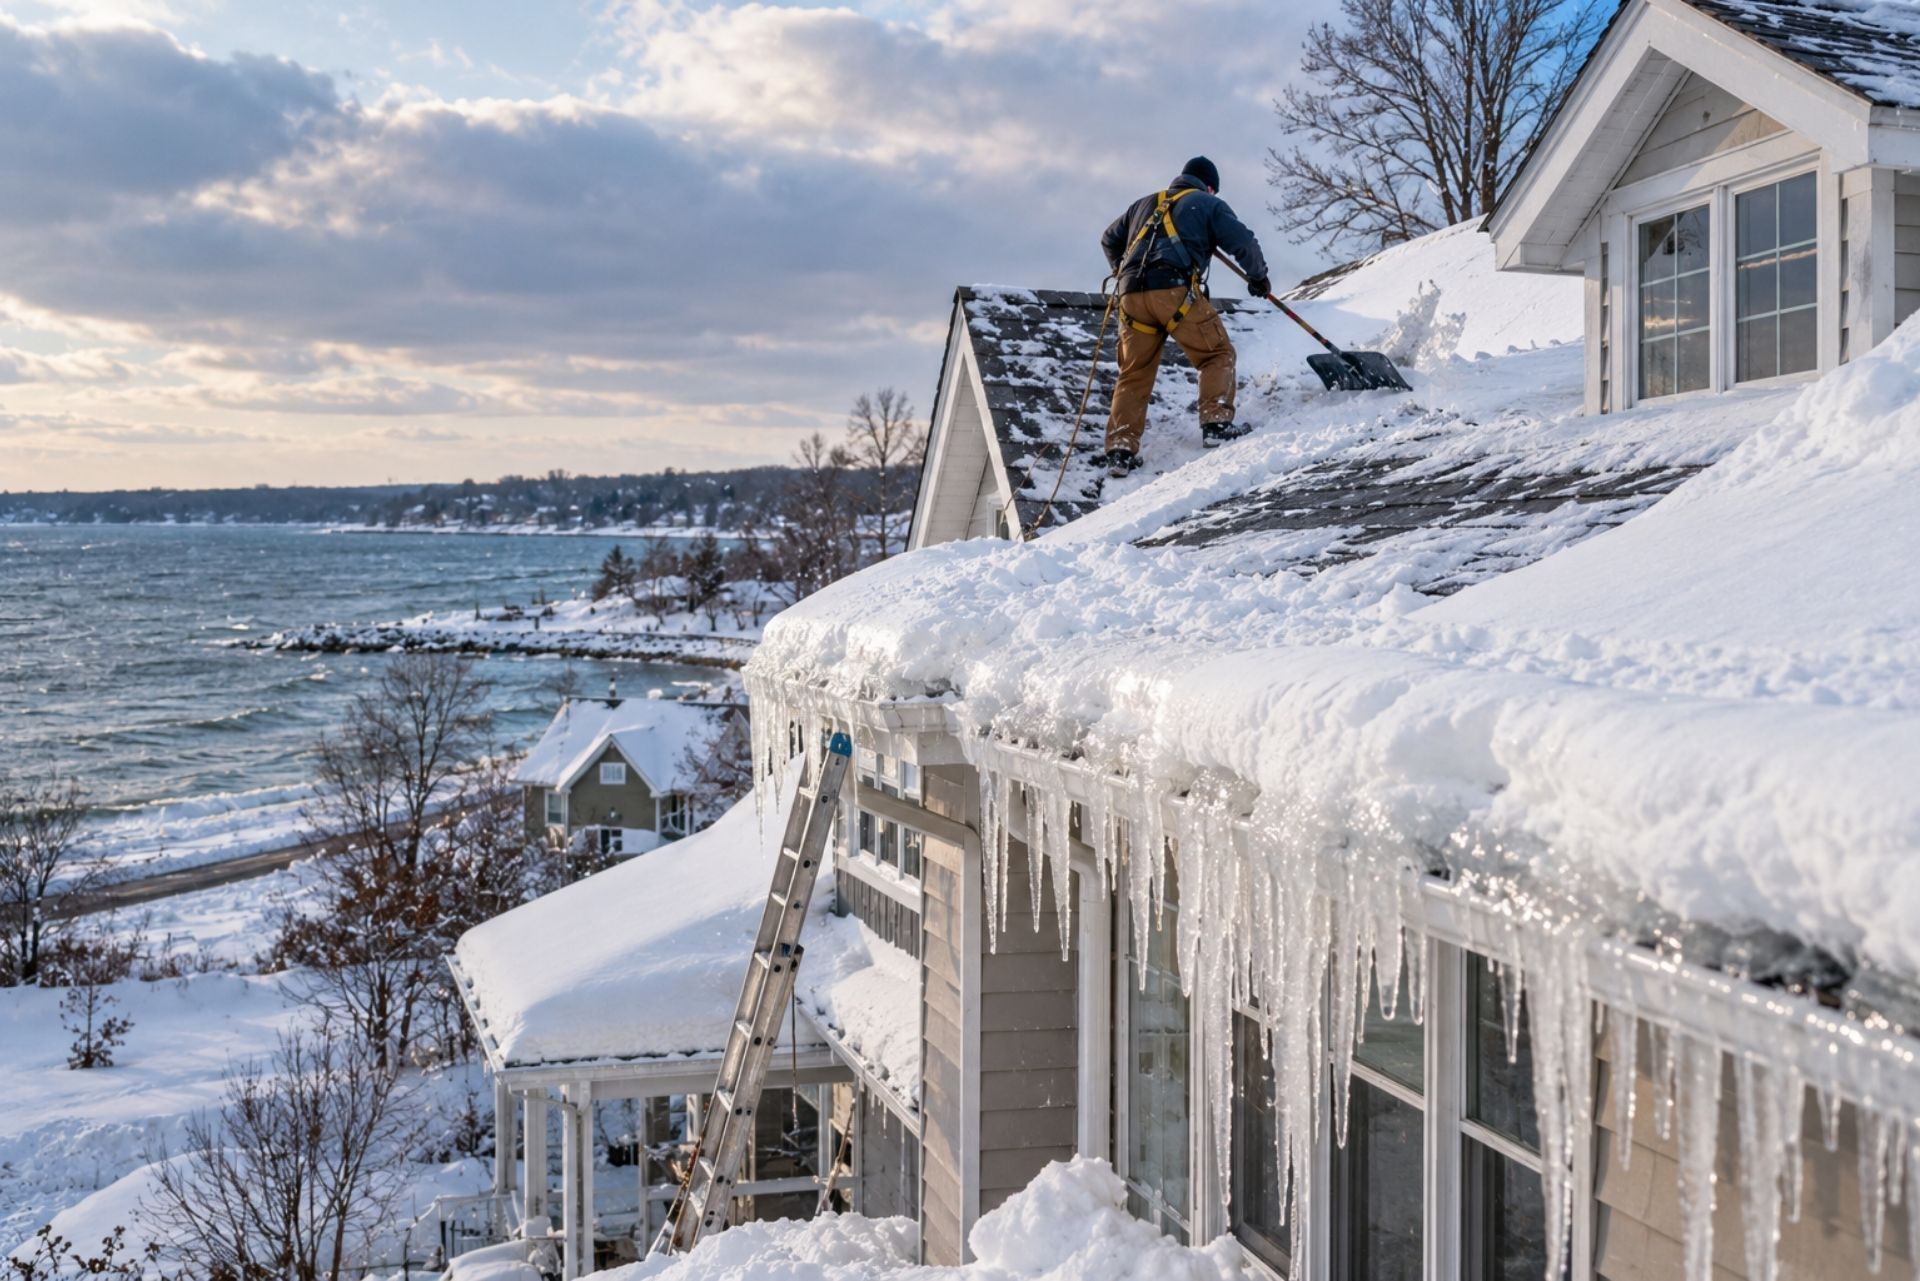
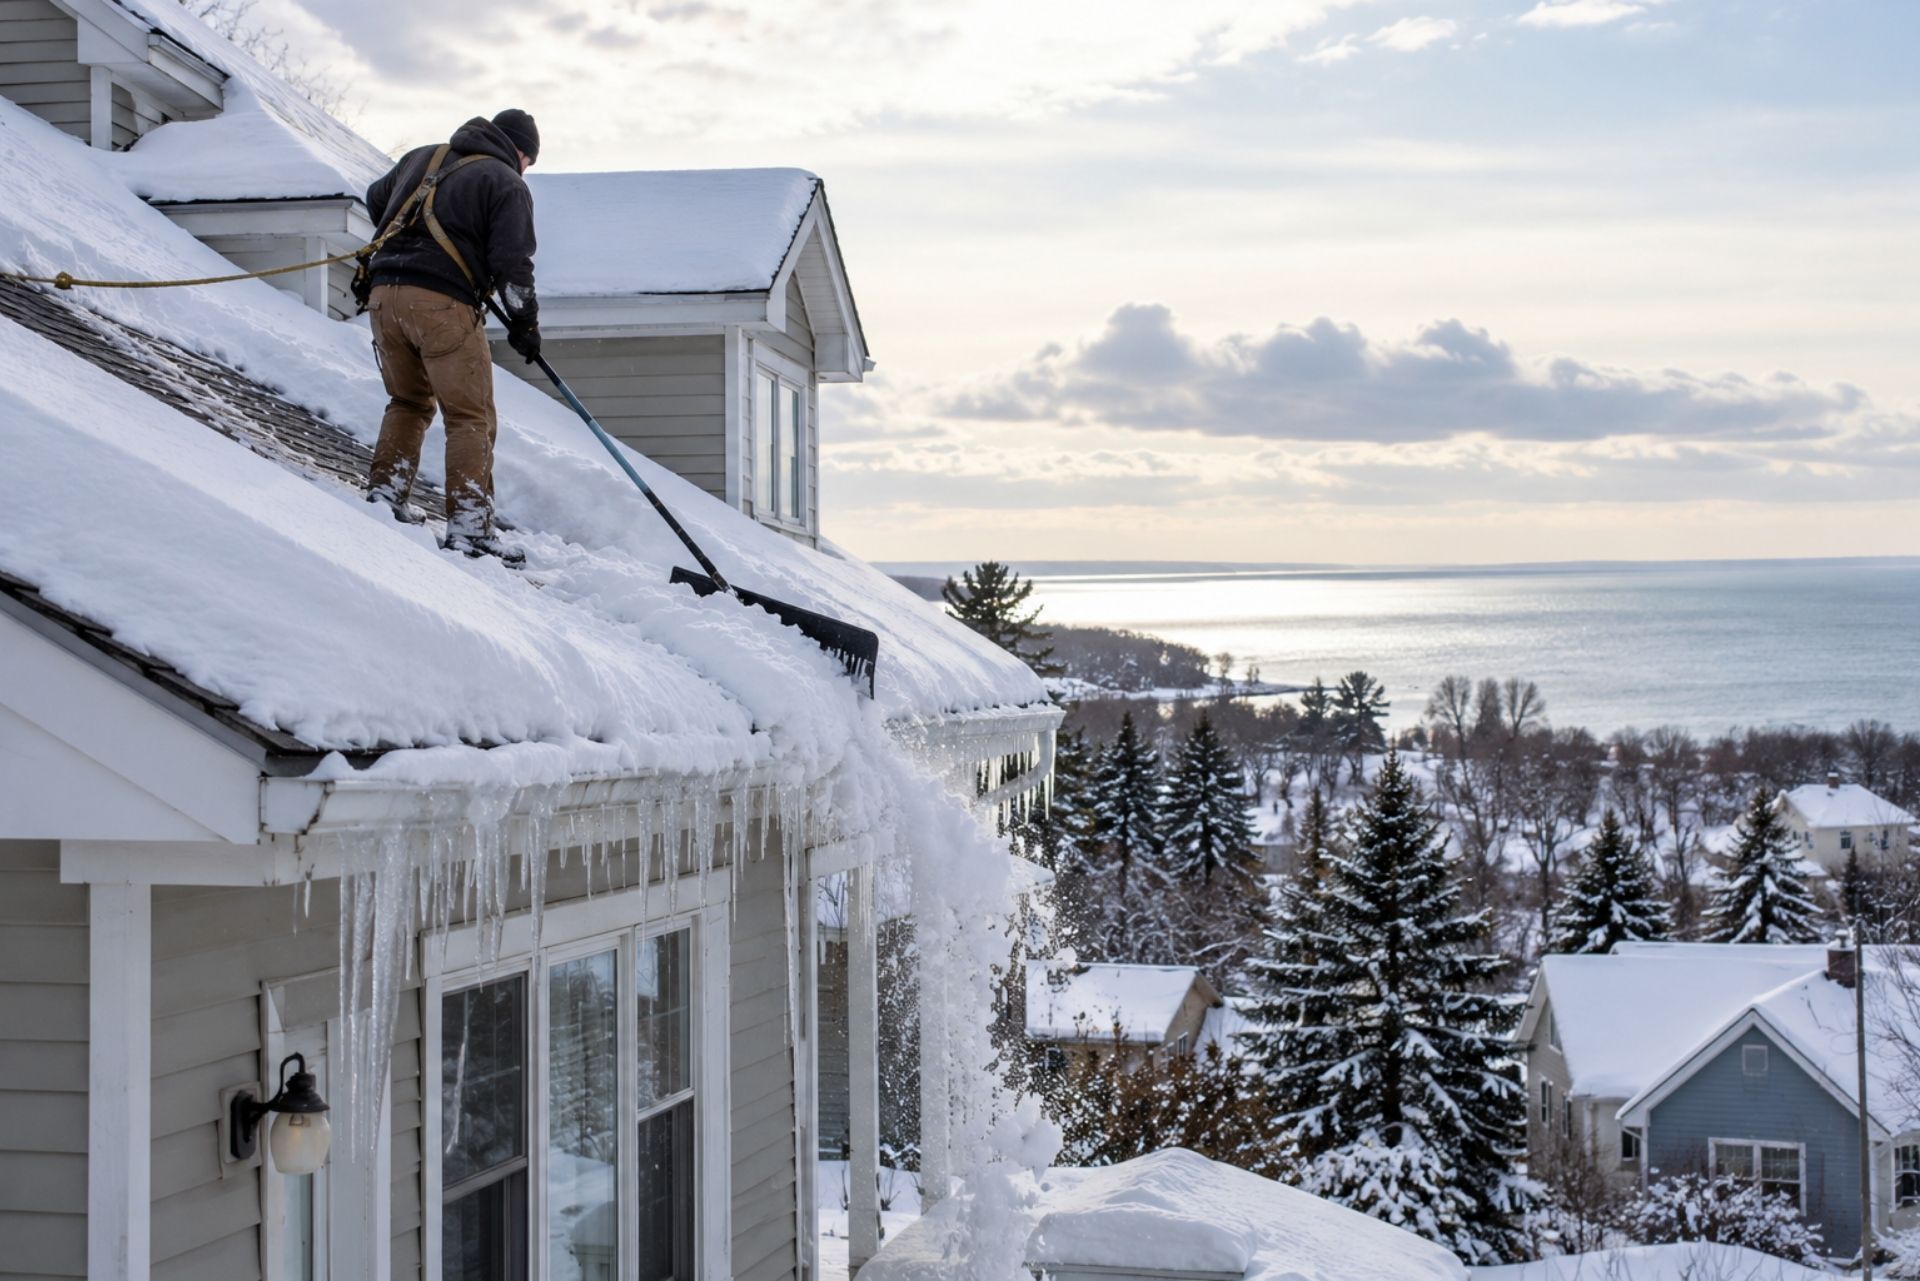
An ice dam is a ridge of ice that forms along the edge of a roof. Heat escaping from the attic melts snow on the upper roof, that water runs down to the colder eaves, and it refreezes. The ridge grows, and meltwater backs up behind it, working under shingles and into walls, ceilings, and insulation.
Here's how coverage typically breaks down. Interior water damage from an ice dam (stained ceilings, ruined drywall, soaked insulation, damaged flooring) is often covered under a standard policy. Removing the ice dam itself usually is not, because insurers treat that as maintenance. So if you hire someone to steam the dam off your roof in January, plan to pay that bill yourself, even if the resulting leak claim gets approved.
A common mistake we see: people wait until water shows up inside to deal with a visible dam, then discover the delay hurt their claim. If you notice a thick ice ridge and icicles hanging from your gutters, document it with photos, have it removed, and check your attic for wet spots. Prompt action supports your claim instead of undermining it.
Attic Insulation for Older Erie Homes
Prevention beats any claim. Much of Erie's housing stock dates to the early and mid-1900s, and many of those homes have thin or settled attic insulation, open top plates, and recessed lights that leak heat straight into the attic.
- Seal air leaks around chimneys, plumbing stacks, light fixtures, and attic hatches before adding insulation
- Bring insulation up to current recommended depths for our climate zone
- Make sure soffit and ridge vents are clear so the roof deck stays cold
- Consider ice and water shield membrane along the eaves at your next reroof
A cold roof deck is the goal. Fix the heat loss, and the dams mostly stop forming.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Lakefront Wind Exposure Near Presque Isle
Wind damage from Lake Erie is covered under standard Pennsylvania homeowners policies, including damage to shingles, siding, and structural components. Homes near the bayfront and close to Presque Isle State Park face stronger, more frequent gusts because there's nothing between the open water and the house to slow the wind down.
Wind claims usually start small. A gust lifts a few shingle tabs, breaks the seal strip, and suddenly you have exposed decking. Lose enough shingles and rain or melting snow gets in. Insurers will pay to repair wind-damaged roofing, but they also look closely at roof age and condition. An older roof may be settled on an actual cash value basis, meaning depreciation comes off the check, while a newer roof is more likely to qualify for replacement cost.
Check your declarations page for these details:
- Roof settlement terms: replacement cost or actual cash value on the roof
- Wind/hail deductible: some policies use a separate deductible for wind, sometimes as a percentage of dwelling coverage
- Matching provisions: whether the carrier will replace undamaged shingles so the roof matches
- Other structures limits: fences, sheds, and detached garages near the water take a beating
Structural integrity matters too. Wind can rack framing, pull gutters, and send tree limbs through a roof. The September 2026 storm was a reminder. Affected residents have until November 23, 2026, to apply for low-interest SBA disaster loans, and City of Erie and Millcreek Township homeowners can apply for Disaster Recovery Assistance Program repair grants until December 24, 2026. Those programs help, but they work alongside insurance, not instead of it.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Home
A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.
Risk of Frozen Pipes in Older Erie Homes
Frozen and burst pipes are generally covered, but only if you took reasonable care to keep the home heated. That condition is written into nearly every homeowners policy, and it's the clause that sinks the most winter water claims we see in older Erie homes.
Older houses carry specific plumbing risks. Many still have galvanized steel supply lines that corrode from the inside, narrowing the pipe and weakening the walls. Others have copper runs through uninsulated exterior walls, crawl spaces, or unheated additions. Add a stretch of single-digit nights with wind off the lake, and a weak spot gives out. When a pipe bursts, it can release a lot of water in a short time, soaking floors, ceilings, and basements before anyone notices.
The heat requirement is where people get into trouble. If you leave for Florida in January and set the thermostat to 50, then the furnace quits and the pipes freeze, your insurer will want to know whether you had someone checking the house or had shut off and drained the water. Vacant homes and rentals between tenants face even stricter rules, and many policies limit coverage after 30 or 60 days of vacancy.
Practical steps that protect both the house and the claim:
- Keep the thermostat at a steady temperature, even when you're away
- Have a neighbor or family member check the home regularly during long trips
- Install a smart leak detector or temperature sensor that alerts your phone
- Insulate pipes in exterior walls, basements, and crawl spaces
- Know where your main water shutoff is before you need it
Also remember that the policy pays for the water damage, not usually the corroded pipe itself. Replacing old galvanized lines is on you, so it's worth budgeting for before a failure forces the issue.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
| Risk | Standard Policy | With Endorsement |
|---|---|---|
| Roof collapse from snow/ice weight | Usually covered | No endorsement needed |
| Ice dam interior water damage | Often covered | No endorsement needed |
| Ice dam removal | Not covered | Not covered |
| Wind damage to shingles | Covered, roof terms vary | Replacement cost roof options vary by carrier |
| Burst pipe water damage | Covered if heat maintained | No endorsement needed |
| Sewer or drain backup | Not covered | Water backup endorsement, set limit |
| Sump pump failure | Not covered | Usually part of water backup endorsement |
| Frozen or broken water/sewer line in yard | Not covered | Service line endorsement |
| Flood or surface water | Not covered | Separate flood policy |
Comparing Winter Coverage Limits and Deductibles
A standard policy handles a lot of Erie's winter risks, but two of the most common gaps are sewer and drain backup and buried service line damage. Both need endorsements, and both are worth pricing out if your home is older.
| Coverage | PA Minimum | Common Recommendation |
|---|---|---|
| Auto bodily injury | $15,000 / $30,000 | $250,000 / $500,000 |
| Auto property damage | $5,000 | $100,000 |
| Medical benefits (auto) | $5,000 | $10,000 or more |
| Home personal liability | None required | $300,000 to $500,000 |
| Umbrella | None required | $1 million or more |
Water backup coverage is the one we push hardest in Erie. Spring thaws and heavy melt can overwhelm sump pumps and municipal lines, sending water into finished basements. Endorsement limits commonly range from a few thousand dollars to much higher amounts, so match the limit to what's actually in your basement.
Service line coverage pays to repair buried pipes running from the street to your house. In an older neighborhood, a frozen or collapsed clay sewer lateral can mean digging up the yard, and the homeowner usually owns that line.
Flood is a separate policy entirely. As of August 2026, the average annual NFIP flood premium for Erie County policyholders was $1,087.
On deductibles, raising yours lowers premium, but run the math on a realistic winter claim. A $2,500 deductible on a $6,000 ice dam leak leaves you covering a big share yourself.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Frequently Asked Questions About Erie Home Insurance
Does insurance cover roof snow removal? No. Shoveling or raking snow off your roof is considered maintenance, so you pay for it. If the weight causes damage before you clear it, that damage is usually covered.
Is wind damage from Lake Erie covered? Yes, standard policies cover wind damage to your roof, siding, and structure. Check whether your roof is paid at replacement cost or actual cash value, and whether you have a separate wind deductible.
Will my policy pay if a pipe freezes while I'm on vacation? It should, as long as you kept the heat on or properly drained the water system. If the house sat unheated and nobody checked on it, the claim may be denied.
Are ice dams covered by homeowners insurance? Water damage inside your home from an ice dam is often covered. Paying someone to remove the ice itself usually is not.
Does homeowners insurance cover a flooded basement? It depends on the source. A burst pipe is usually covered, sewer backup needs an endorsement, and groundwater or surface flooding needs a separate flood policy.
Should I get a home inspection on an older Erie house before buying? Yes. Ask the inspector to look closely at the roof, attic insulation, plumbing materials, and sewer lateral, since those are the areas most likely to cause winter claims.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
| Risk | Standard Policy | With Endorsement |
|---|---|---|
| Roof collapse from snow/ice weight | Usually covered | No endorsement needed |
| Ice dam interior water damage | Often covered | No endorsement needed |
| Ice dam removal | Not covered | Not covered |
| Wind damage to shingles | Covered, roof terms vary | Replacement cost roof options vary by carrier |
| Burst pipe water damage | Covered if heat maintained | No endorsement needed |
| Sewer or drain backup | Not covered | Water backup endorsement, set limit |
| Sump pump failure | Not covered | Usually part of water backup endorsement |
| Frozen or broken water/sewer line in yard | Not covered | Service line endorsement |
| Flood or surface water | Not covered | Separate flood policy |
| Coverage | PA Minimum | Common Recommendation |
|---|---|---|
| Auto bodily injury | $15,000 / $30,000 | $250,000 / $500,000 |
| Auto property damage | $5,000 | $100,000 |
| Medical benefits (auto) | $5,000 | $10,000 or more |
| Home personal liability | None required | $300,000 to $500,000 |
| Umbrella | None required | $1 million or more |
Consult with MVP Insurance for Erie Property Protection
Erie homes deal with a mix of risks that most of the state never sees in the same week: lake effect snow stacking up on older roofs, ice dams forming at the eaves, wind ripping across the bayfront near Presque Isle, and aging pipes freezing in uninsulated walls. A policy that looks fine on paper can leave real gaps once you read the exclusions for maintenance, vacancy, and water backup.
As an independent agency, MVP Insurance works for you, not a carrier. We shop and compare policies from multiple insurers so you can see how roof settlement terms, wind deductibles, and endorsement limits stack up side by side. If you also drive Erie's winter roads, where PennDOT has expanded weather-triggered whiteout warnings on I-79 and I-90,we can review your car insurance in Erie, Pennsylvaniaat the same time.
Call Josh Medure or David Varrati at (724) 453-1122 or (330) 707-9055 for a review of your Erie PA homeowners insurance and auto coverage. Our offices are at 108 E Grandview Ave, Zelienople, PA 16063 and 13823 Grant St, New Springfield, OH 44443. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
Before the next big snow band rolls in off the lake, take ten minutes to compare your options. You can
start your quote hereand we'll handle the comparison work for you.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.