


Owner, MVP Insurance
Pennsylvania inland marine insurance covers the business property that doesn't stay put: tools, contractors equipment, materials headed to a job, and gear sitting overnight in a truck or trailer. For Western Pennsylvania contractors, it fills the gap between a standard property policy (which protects your building) and the reality of work spread across a dozen sites in Butler, Beaver, Allegheny, and Westmoreland counties.
Most contractors find out about this gap the hard way. A crew leaves a job in Cranberry, parks the truck in a driveway, and wakes up to a smashed window and an empty tool box. The general liability policy doesn't respond, the commercial auto policy doesn't cover the tools, and the shop's property policy only protects what's inside the shop. That's the moment people learn the term "inland marine."
What is Pennsylvania Inland Marine Insurance?
Inland marine insurance protects movable business property, such as tools, equipment, and materials, while it's in transit or sitting at job sites across Western Pennsylvania. The name sounds nautical because it grew out of ocean cargo coverage, but today it's built for property that travels over land. If your gear rides in a truck, sits in a trailer, or spends weeks at a customer's site, this is the policy that follows it.
It's a standard item on the MVP Insurance Trello policy checklist, the internal list our team works through when reviewing a business client's coverage. We put it there because so many contractors assume they're covered when they aren't. An electrician with $40,000 in tools and a property policy tied to a single address has a big hole in their protection.
Inland marine policies are usually written as "floaters," meaning the coverage floats with the property instead of staying fixed at one location. Common forms include contractors equipment floaters, tool floaters, installation floaters, and transit coverage. Most contractors carry it alongside their other business insurance in Pennsylvaniaas part of a broader commercial package.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page

Life
Term life pays your family a set amount if you die during the term; whole life lasts your lifetime and builds cash value. We help you size the amount to the mortgage, the kids and the years of income you want to replace.
| Feature | DP-1 (Basic) | DP-3 (Special) |
|---|---|---|
| Covered perils | Named perils only | All risks, minus exclusions |
| Building settlement | Usually actual cash value | Usually replacement cost |
| Sudden water damage | Often excluded | Usually covered |
| Theft/vandalism | Optional, limited | Typically included |
| Loss of rent | Often optional | Usually included |
| Liability | Often an add-on | Add-on or included |
| Best fit | Older, low-value homes | Most modern rentals |
| PA legal requirement | None by state law | None by state law |
Protecting Contractors Equipment and Heavy Machinery
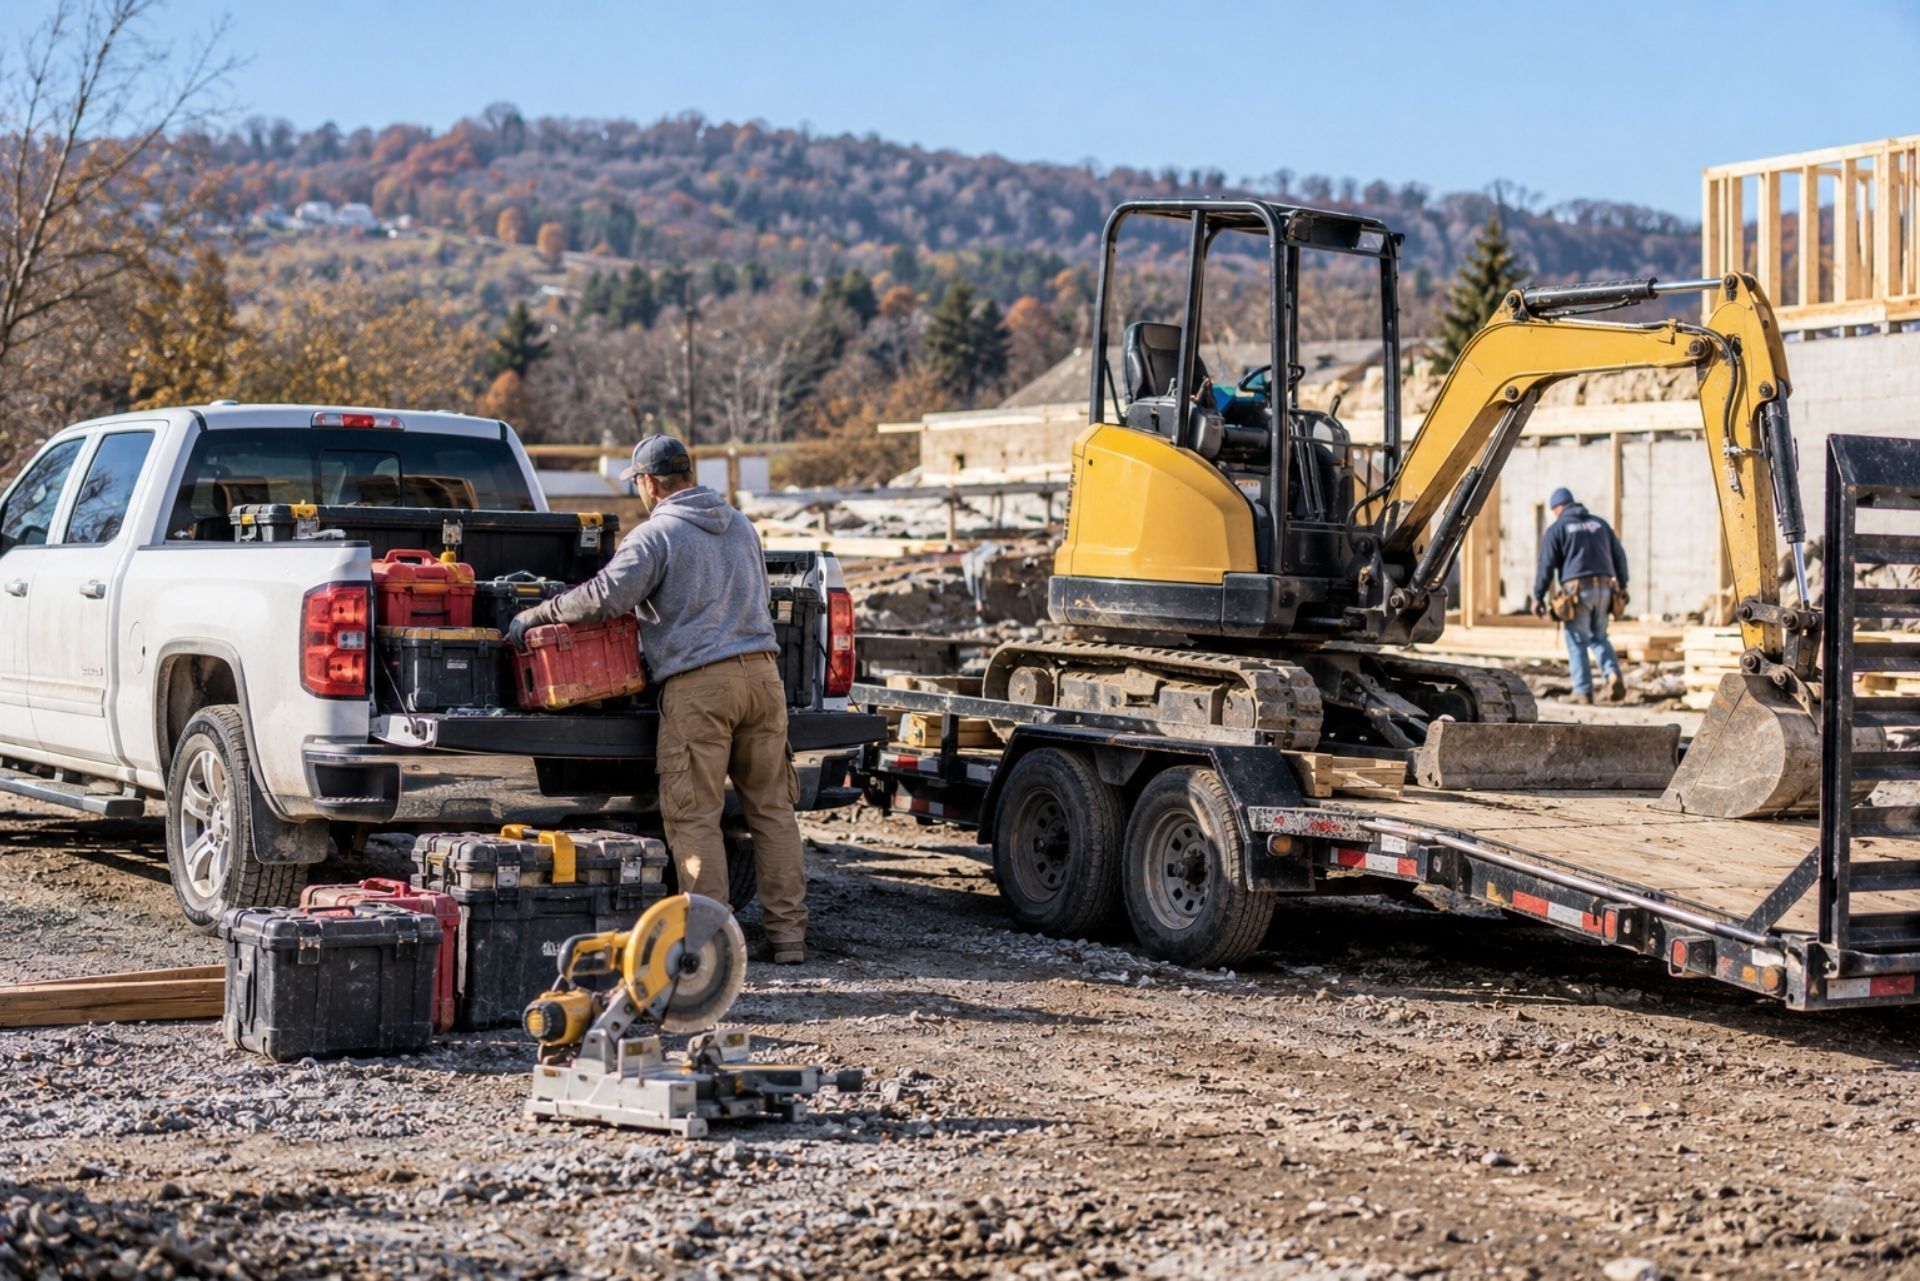
A contractors equipment floater covers machinery like skid steers, mini excavators, compact track loaders, generators, compressors, and scaffolding against theft, vandalism, fire, collision, overturn, and similar perils. It's the backbone of any contractor's inland marine program.
The way you schedule equipment matters more than most people realize. Scheduled coverage lists each item with a serial number and a stated value, which makes claims cleaner. Blanket coverage puts a single limit over a category of smaller items, usually with a per-item cap. A common mistake we see is a contractor scheduling the excavator but forgetting the $18,000 attachments that go with it, or listing equipment at its purchase price from 2019 without checking whether the policy pays actual cash value or replacement cost.
Generators deserve special attention. They're among the highest-value theft targets in Pennsylvania, along with copper wiring and fuel, especially at unguarded staging areas along the I-76 and I-80 corridors. If you rent or borrow equipment, ask about rented equipment coverage too. Many rental agreements make you responsible for the full value, and your floater may not include rented items unless you add them.

Written By
David Varrati
Owner, MVP Insurance
On this page
HCertificates of Insurance for Pennsylvania Contracts
Canopy import
Share your current policies in a few clicks through Canopy. We see exactly what you have today, so the comparison is apples to apples.
Insuring Tools in Transit and Theft from Vehicles
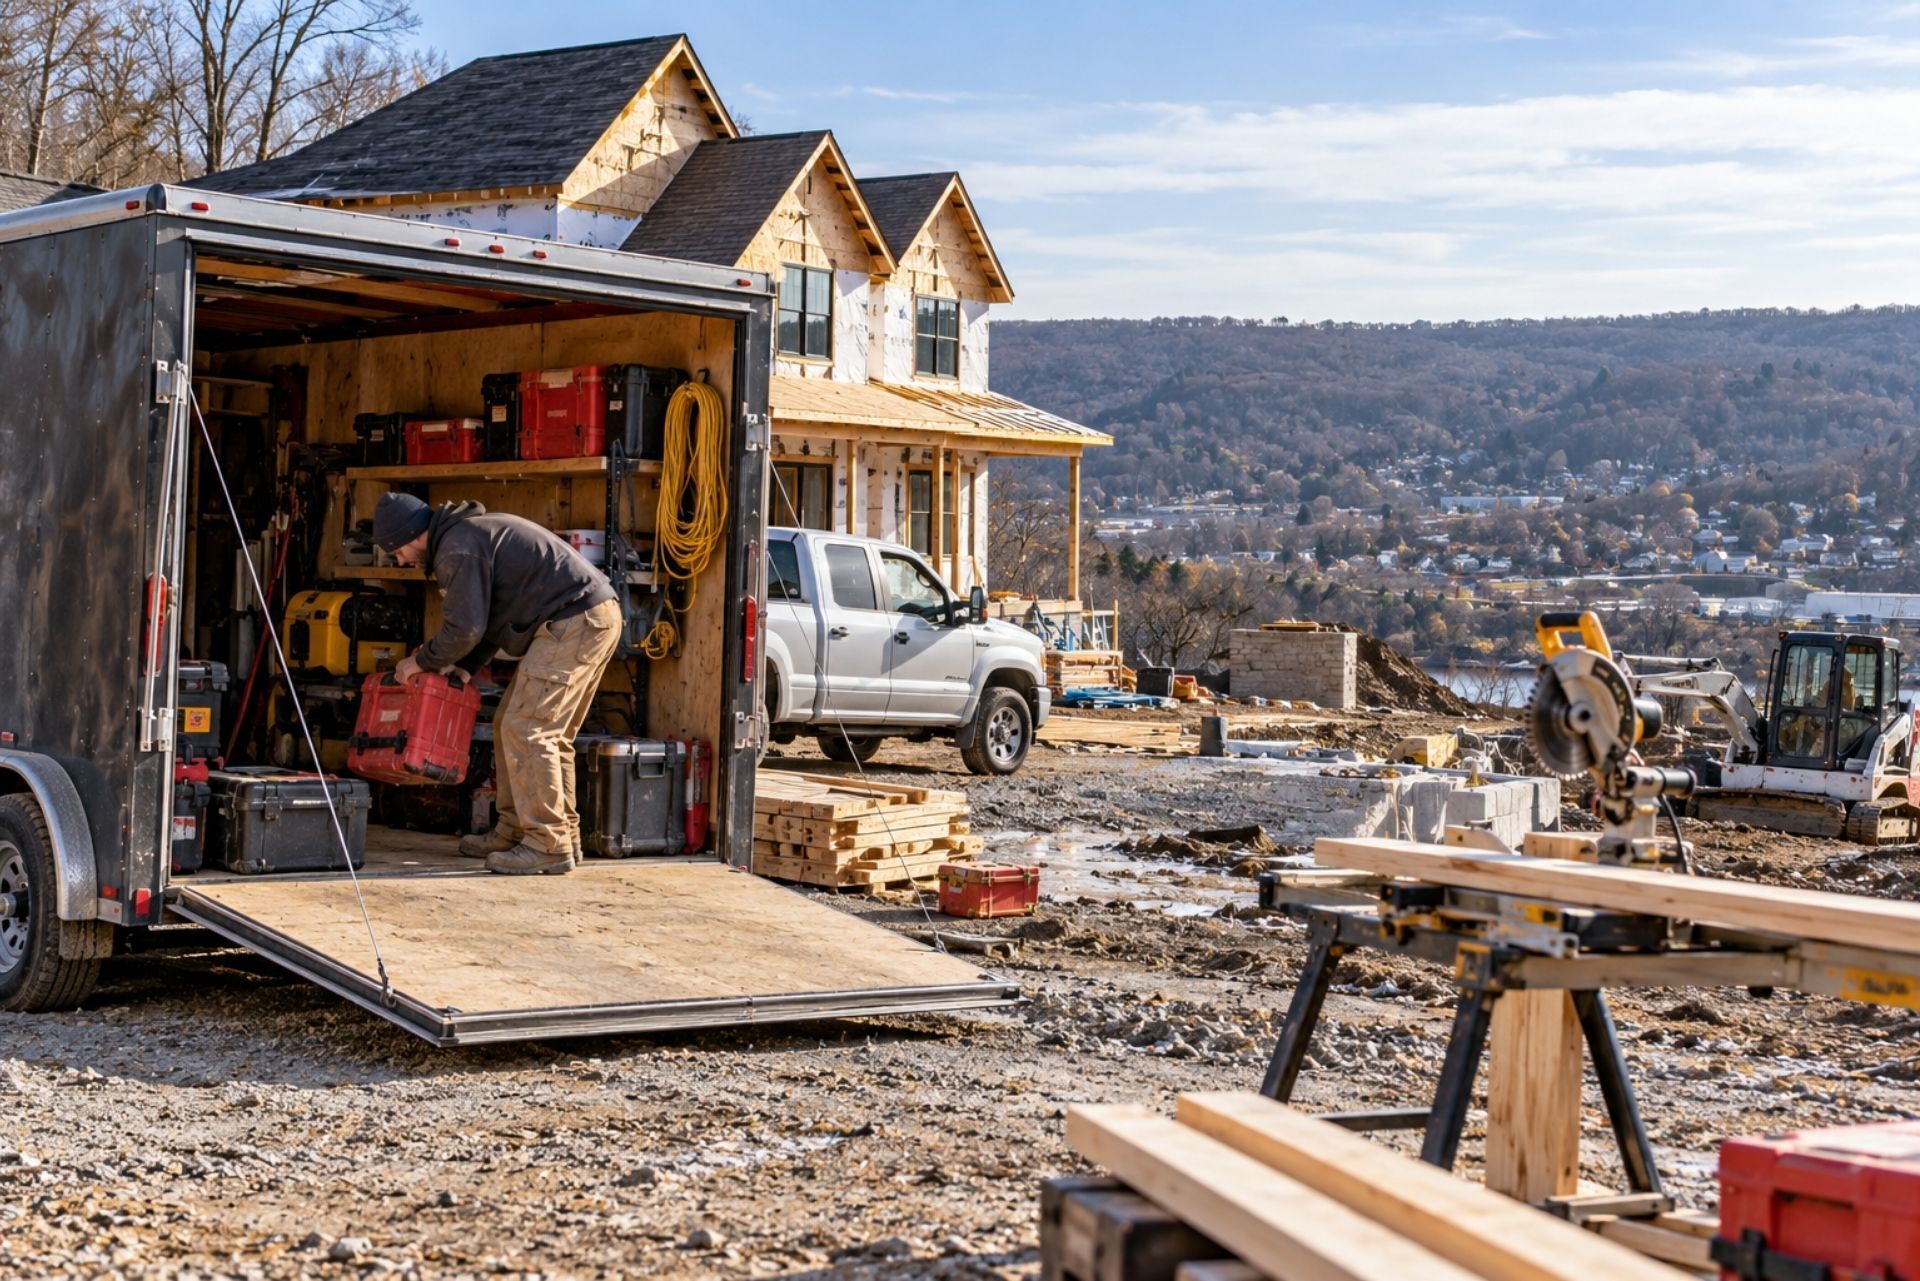
Tools left in trucks overnight are one of the most common theft claims contractors file, and inland marine coverage is how those claims get paid. Commercial auto insurance covers the truck itself. It does not cover the drills, saws, laser levels, and pipe threaders inside it. A tool floater or transit coverage picks up that loss.
The pattern is depressingly familiar. A plumber finishes late, leaves the van at home or at a hotel, and the side door gets punched overnight. Thieves know which vans carry tools, and they know how fast they can resell them. Westmoreland County has seen thefts that targeted trailers at transit hubs, including construction trailers hit at the Flying J Travel Center, which shows how vulnerable equipment is while it's on the move.
Here's what to check in your policy before a claim, not after:
- Vehicle theft conditions: Some forms require visible signs of forced entry or that the vehicle was locked. A missing tool with no broken lock may be denied.
- Unattended vehicle exclusions: Older forms exclude theft from unattended vehicles during certain hours unless the vehicle is in a locked garage. Ask whether yours has this.
- Employee tools: Your crew's personal tools may not be covered under your floater unless you add an employee tools endorsement.
- Deductible per occurrence: A $1,000 deductible on a $1,400 loss doesn't help much. Match the deductible to the size of claim you'd actually file.
Keep an inventory with photos and serial numbers on your phone. When a theft happens at 6 a.m., you'll file faster and get paid sooner.
Installation Floaters for Materials at the Job Site
An installation floater covers materials and equipment you're installing, from the moment they leave your shop until the job is accepted by the owner. Think HVAC units, windows, cabinetry, roofing materials, electrical panels, and copper wire waiting to be pulled.
These floaters bridge a gap that standard property insurance leaves wide open, since that coverage often stops once materials leave a contractor's primary warehouse. Say a mechanical contractor stages $60,000 in rooftop units at a commercial build in Ellwood City. If the units get stolen or damaged before they're set and connected, the property owner's builders risk policy may not apply yet, and your shop policy definitely doesn't. The installation floater does.
Pay attention to three limits: materials at the job site, materials in transit, and materials in temporary storage (like a rented storage unit or a supplier's yard). Each can carry its own cap. Also check when coverage ends. Most forms stop when the work is accepted or the owner takes occupancy, so finishing touches done after acceptance may fall outside it. Contractors who work on several jobs at once should look at a blanket installation floater rather than buying coverage job by job.
Property That Moves Between Job Sites in Western Pennsylvania
Inland marine coverage is designed for property that rotates between jobs, so a generator that spends Monday in Zelienople and Thursday in Greensburg stays covered the whole week. That mobility is exactly why job site theft is so common here: equipment sits overnight in places with no fence, no camera, and no one watching.
The losses can be large. Pennsylvania State Police investigated a case where more than $50,000 in tools and equipment were stolen from a single construction site in South Huntingdon Township, Westmoreland County. One bad night can wipe out a season's profit for a small contractor without the right coverage.
Practical steps that help both prevention and claims: chain equipment to fixed objects, remove batteries or keys from machines overnight, install GPS trackers on high-value items, and document what's on each site. Some carriers credit theft-prevention devices, so mention them when quoting.
Comparing Coverage for Fixed vs. Mobile Property
The confusion usually comes from mixing up where property is versus what policy applies. Here's the plain version:
| Property type | Where it sits | Typical policy |
|---|---|---|
| Office furniture, shop fixtures | Your business address | Commercial property |
| Tools in your truck | Vehicles, job sites | Tool floater (inland marine) |
| Excavator, skid steer | Moves between sites | Contractors equipment floater |
| Materials before install | Job site, transit, storage | Installation floater |
| Materials before install | Job site, transit, storage | Installation floater |
If an item leaves your building regularly, assume your property policy won't follow it.
Comparing Inland Marine Coverage Limits and Options
Inland marine policies are flexible, so limits and terms vary a lot by carrier and by the type of work you do. The right setup depends on what you own, what you rent, and how much material sits on a site at once.
| Option | What to decide | Common pitfall |
|---|---|---|
| Scheduled vs. blanket | List items individually or cover a group under one limit | Per-item caps on blanket coverage are too low |
| Valuation | Actual cash value or replacement cost | ACV pays depreciated value on old tools |
| Deductible | Flat amount per claim | Set too high for frequent small thefts |
| Rented equipment | Add or skip | Rental contract makes you liable for full value |
| Employee tools | Add or skip | Crew's tools left out entirely |
| Transit limit | Max value per trip | Hauling more than the limit on one load |
Pricing flexibility may be changing in Pennsylvania. On April 11, 2026, the Pennsylvania Insurance Department issued a notice deregulating inland marine filings from rate, rule, and policy form requirements, which is intended to give carriers more room in how they price and write these policies. Exactly how carriers respond is still taking shape, so treat it as a reason to compare forms carefully rather than assume every policy reads the same.
Good recordkeeping helps on the underwriting side too. As one construction underwriting guide put it, "you need proof of discipline." Clean inventories, theft-prevention measures, and a short loss history all make you a stronger risk. Contractors often bundle this with their broader contractors insurance in Pennsylvaniato keep everything coordinated.
Frequently Asked Questions About Inland Marine Insurance
Does my general liability cover my tools? No. General liability covers injuries and damage you cause to other people or their property. Your own tools and equipment need inland marine coverage.
What if my equipment is stolen from a locked trailer? A tool or contractors equipment floater typically covers theft from a locked trailer, as long as you meet the policy's security conditions. Check whether your form requires visible signs of forced entry.
Does commercial auto insurance cover tools in my truck? It covers the truck, not the tools inside. You need a tool floater or transit coverage for the contents.
Is inland marine insurance required in Pennsylvania? State law doesn't require it. Many general contractors, project owners, and equipment lenders do require it in their contracts, though.
Are my employees' personal tools covered? Only if you add an employee tools endorsement. Many policies leave them out by default.
How much inland marine coverage do I need? Add up the replacement cost of everything you'd have to rebuy after a total loss, including the largest load of materials you'd have on one site. That number is your starting point.
Securing Your Assets with MVP Insurance
Your tools and equipment are how you get paid. Inland marine coverage keeps a stolen generator, a burglarized van, or a missing load of materials from turning into a business-ending loss. The details matter: valuation, theft conditions, employee tools, and transit limits are where claims get approved or denied.
MVP Insurance, founded in 2008 by Josh Medure and David Varrati, is an independent agency, which means we compare inland marine options from multiple carriers and work for you rather than the insurer. We're licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293, with 24/7 claims support when something goes missing overnight.
If you'd like a second set of eyes on your current coverage, start your quoteor call one of our offices. Reach us in Zelienople at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122, or in New Springfield at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. Walk us through what you haul, rent, and install, and we'll build a policy that follows your gear wherever the next job takes it.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
Joshua Medure
Owner, MVP Insurance
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation
Commercial Auto

Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.


Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.







