

Owner, MVP Insurance
Boardman OH homeowners insurance should protect your house against the risks that actually cause claims here: wind, hail, and water in the basement. It also needs to satisfy your lender and reflect the real age of your roof, wiring, and plumbing. Getting those details right before a storm hits matters more than the premium you see on the first quote.
Boardman Township is full of solid, well-built homes from the postwar boom. Many of them sit on quiet streets a short drive from the US-224 corridor and Southern Park Mall. Those houses have aged, though, and insurance carriers have noticed. A policy that worked fine ten years ago may now carry exclusions, roof restrictions, or gaps you won't find until you file a claim.
Money is tight for a lot of local households, too. Regional research found that roughly 17% of Mahoning Valley homeowners are cost-burdened, spending more than 30% of income on housing costs that include insurance and taxes. When the budget has little room to spare, a denied claim or a surprise non-renewal can do real damage. This guide walks through the issues we see most often with Boardman properties and what you can do about each one.
Securing Boardman OH Homeowners Insurance for Local Properties
The right policy for a Boardman home covers the dwelling at full replacement cost, includes the water and wind protections local weather demands, and meets your mortgage company's requirements. Most lenders want proof of coverage at closing and at every renewal. A lapse can trigger force-placed insurance, which typically costs more and protects the lender, not you.
Mahoning County homes face a fairly predictable set of threats. Spring and summer thunderstorms bring hail and straight-line wind. Heavy rain overwhelms storm sewers and pushes water into basements. Winter adds ice dams and the weight of wet snow on older roofs. A standard policy handles some of this well and some of it poorly, and the difference often comes down to a few endorsements most people never read.
MVP Insurance was founded in 2008 by Josh Medure and David Varrati as an independent agency. That means we don't work for any single carrier. We shop your home across multiple companies, compare coverage side by side, and explain the tradeoffs in plain language. Our New Springfield office is about 15 minutes from Boardman, so we know the neighborhoods, the storm patterns, and the township's housing stock firsthand.
If you want a broader look at state-level coverage, our overview of homeowners insurance in Ohio covers the basics. The rest of this page focuses on what makes Boardman different.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Insuring Mid-Century Ranch Homes in Boardman Township
Mid-century ranches are insurable at competitive rates, but carriers will look closely at the electrical system, the plumbing, and the roof before offering their most favorable terms. Updates in those three areas usually make the biggest difference in both price and eligibility.
Boardman's housing is largely postwar suburban construction built between the late 1940s and 1970s. These homes often have simple rooflines and ventilation deficits, which affects how they hold up under snow loads and high wind. Single-story layouts are a plus for some risks, but long, low roofs can be vulnerable when gusts get under the edges.
Electrical is the first thing underwriters ask about. Insurers are increasingly denying new policies for homes with knob-and-tube wiring or outdated electrical panels, and certain older panel brands raise red flags even when they still work. If you've updated to modern breakers, keep the invoice or permit. That paperwork can move you from a non-standard carrier to a preferred one.
Plumbing comes next. Homes with galvanized steel supply lines, common before 1950, often face mandatory upgrade requirements because those pipes typically fail after 40 to 50 years. A house built in 1952 with original galvanized pipe is living on borrowed time, and carriers price it that way.
Replacement cost is the other piece people underestimate. Rebuilding a 1960s ranch today means modern code, current labor rates, and materials that cost far more than they did a decade ago. We regularly see policies set years ago that would leave a homeowner well short after a total loss. Your dwelling limit should reflect today's rebuild cost, not your purchase price or the county's assessed value.
Understanding Roof Age Rules for Older Homes
Ohio carriers have grown strict about roofs. Many require a full replacement or a specialized inspection once a roof passes 15 to 20 years old, and some won't write a new policy on an older roof at all. Others will cover it, but only on an actual cash value basis, meaning they deduct depreciation and pay a fraction of what a new roof costs.
The common mistake we see is a homeowner who doesn't know the roof's age. Sellers guess, inspection reports estimate, and the number drifts. Then a carrier pulls aerial imagery at renewal, flags wear, and sends a non-renewal notice with 30 days to find new coverage.
A few steps help you stay ahead of it:
- Keep your roofing contract and permit. In Boardman, roof replacements require a township zoning review, while structural permits go through Mahoning County Building Inspection. Those records prove the installation date.
- Ask whether your roof is covered at replacement cost or actual cash value. The answer changes your hail claim payout dramatically.
- Shop before you're forced to. If your roof is approaching 15 years, we can compare which carriers still offer full coverage and plan around the replacement timeline.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Protecting Your Property from Basement Water Backup
Water backup coverage is one of the most important additions for a Boardman home, because standard homeowners policies usually exclude damage from a failed sump pump or a sewer line that backs up through floor drains. Without the endorsement, you're paying the cleanup bill yourself.
Here's a scenario we explain often. A heavy summer storm dumps several inches of rain in an afternoon. The municipal sewer surcharges, and water comes up through the basement floor drain into a finished rec room with carpet, drywall, a sectional, and a second freezer. The homeowner assumes it's covered. It isn't, unless they added water backup.
That endorsement is separate from flood insurance, which covers surface water rising from outside. Backup covers water entering through your drains or from a sump that can't keep up. Many Boardman basements need the first, and some low-lying lots need both.
Limits matter as much as having the coverage at all. Some policies include a small default amount that barely covers carpet removal and drying. For a finished basement, we usually recommend higher limits that reflect the cost of replacing flooring, drywall, furniture, and stored items. Walk through your basement and estimate what it would take to restore it, then set the limit with that number in mind.
Prevention can help on both the claim side and the premium side. The ABC Water and Stormwater District has offered a $1,500 supplemental grant for backflow prevention valve installation (confirm current availability with the district before you plan around it). A backflow valve, a battery backup sump pump, and a water alarm are worth mentioning to us, since some carriers give credit for them.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Navigating Hail and Wind Claims in Mahoning County
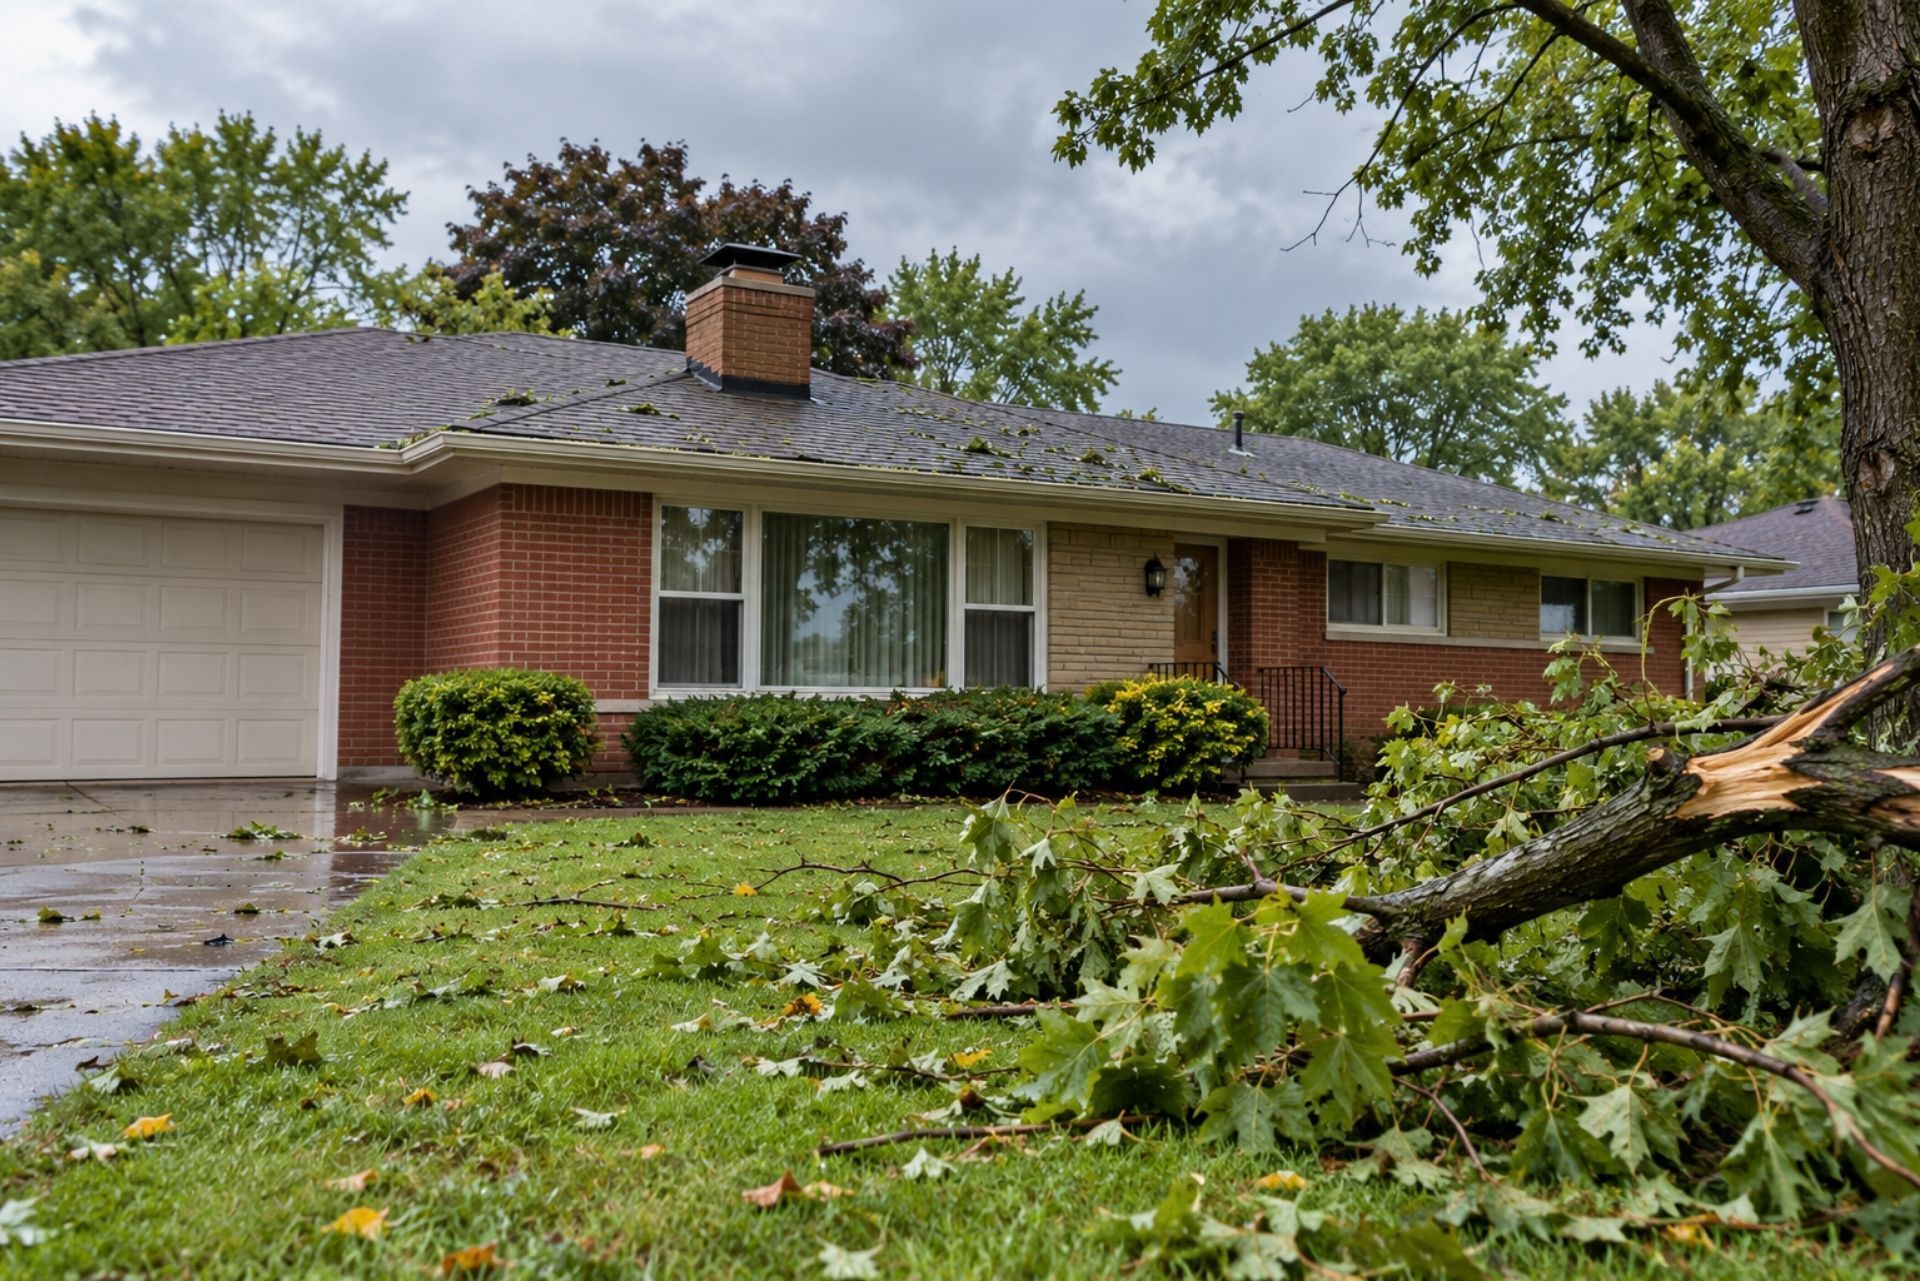
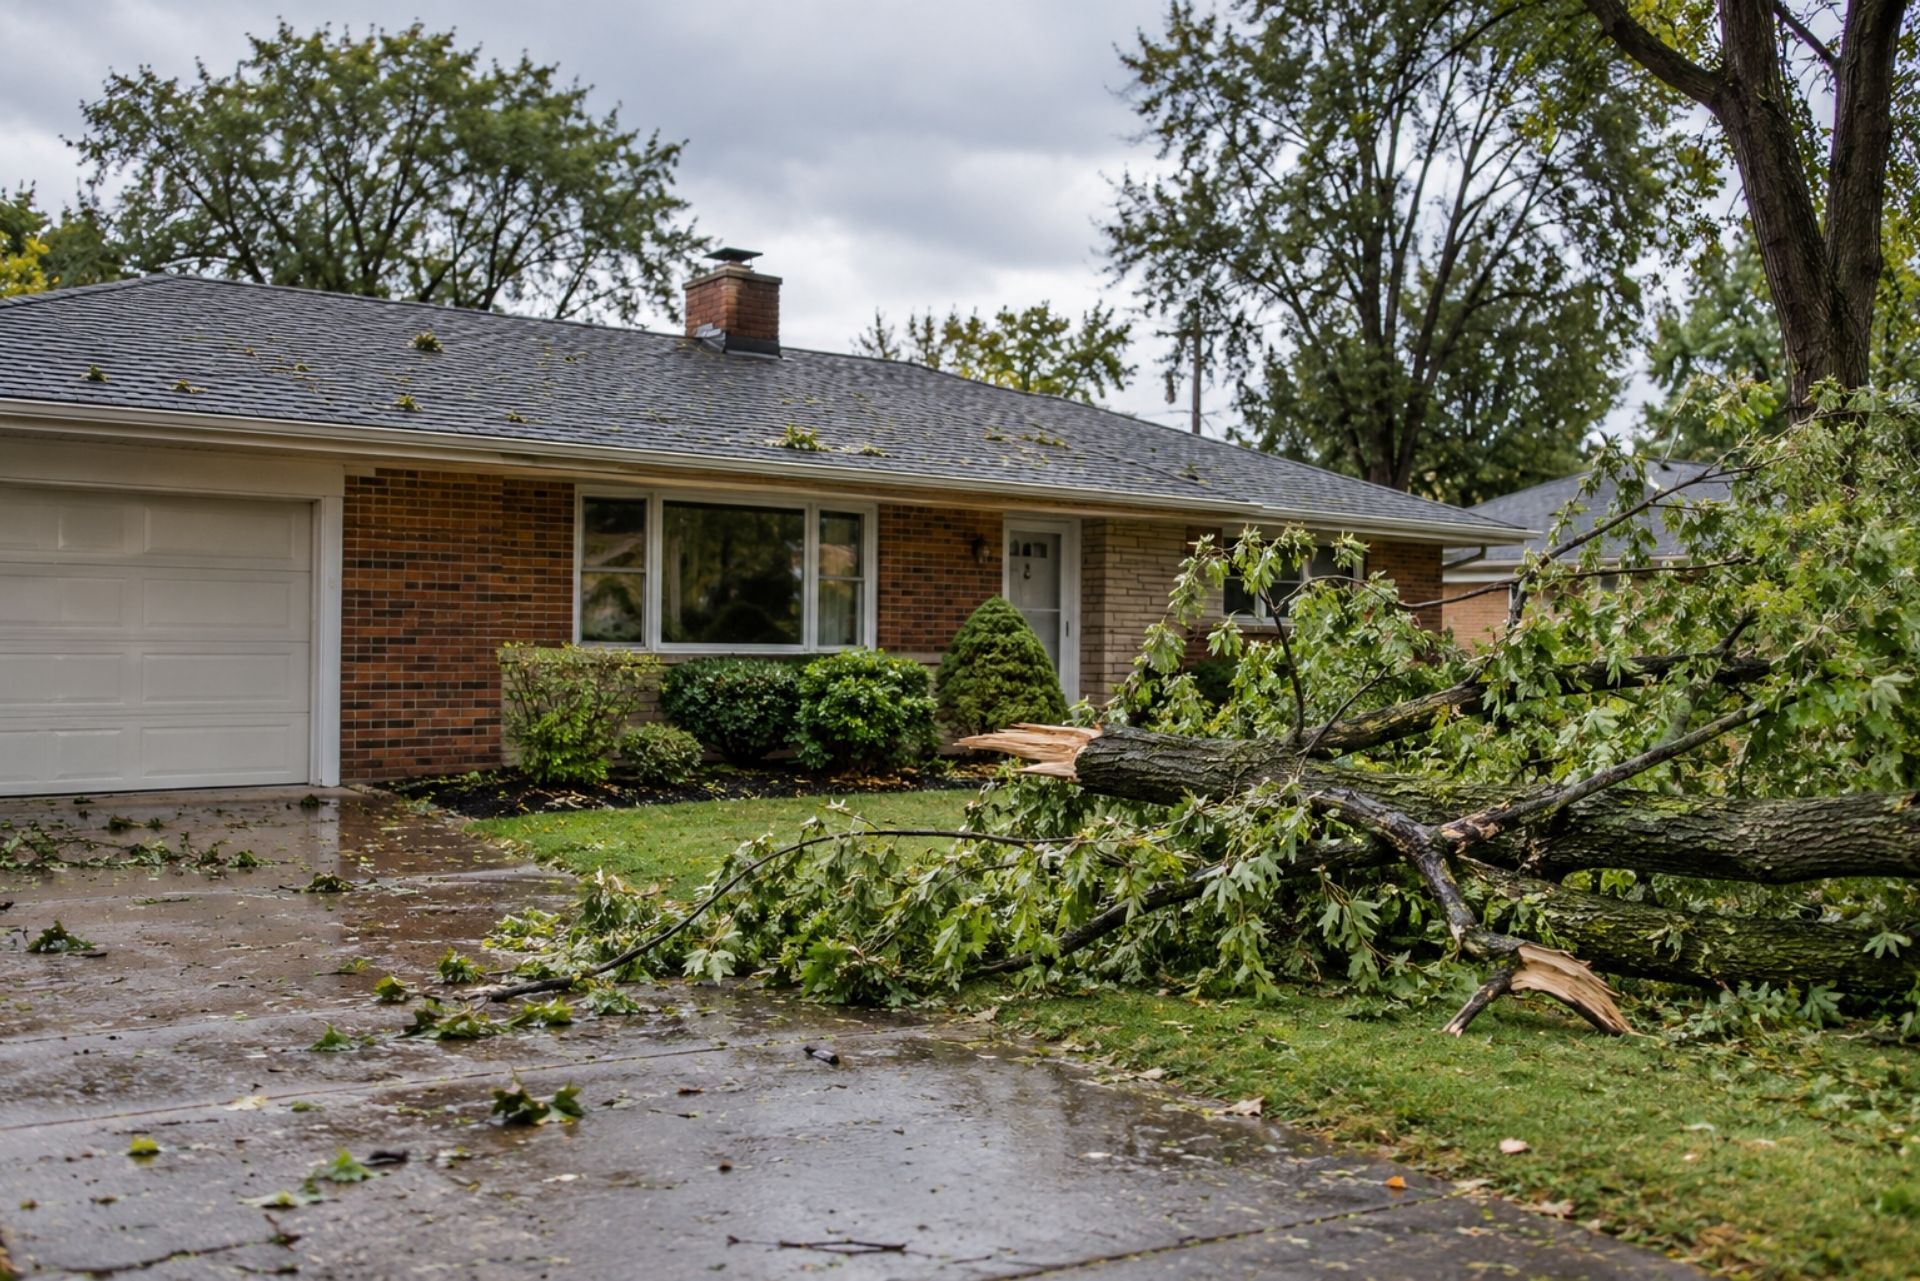
Wind and hail cause the largest share of property claims in Boardman Township. Seasonal storms move across the US-224 corridor with enough force to strip shingles, dent siding and gutters, and drop limbs on roofs. The two things that decide how well you come out of those claims are your wind/hail deductible and your dwelling limit.
Many policies now carry a separate wind/hail deductible that differs from the all-perils deductible. Some are a flat dollar amount, while others are a percentage of your dwelling coverage. A percentage deductible on a home insured for a higher amount can mean a much larger out-of-pocket cost than people expect. We walk clients through the actual dollar figure before they sign, because that's the number that matters after a storm.
Cosmetic damage exclusions are the other surprise. Some carriers exclude hail dents on metal roofing, siding, or gutters if the damage doesn't affect function. That might be acceptable on a detached garage and unacceptable on your main house.
When a storm does hit, a few habits make claims go smoother:
- Photograph your roof, siding, and gutters now, before any damage, and store the images somewhere off your phone.
- After the storm, take date-stamped photos and note the time of the event.
- Make temporary repairs, like tarping, to prevent further damage, and keep receipts.
- Be cautious with door-to-door contractors who show up the next morning offering to handle your claim.
- Call your agent early so someone is checking that the adjuster's estimate covers full repairs, including code upgrades.
MVP Insurance offers 24/7 claims support, so you're not waiting until Monday to get the process started.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Home
A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.
Bundling Home and Car in Boardman Township
For most Boardman households, bundling home and auto is the most effective way to lower total insurance spending. Carriers offer multi-policy credits that aren't available when you buy each policy separately, and you get one renewal date, one agency, and simpler billing.
The savings aren't automatic, though. Sometimes a bundle from one carrier costs more than a strong homeowners policy from one company paired with auto from another. That's where working with an independent agency pays off. We price both ways and show you the actual totals, so you're not assuming a package is the better deal just because it's labeled one.
Bundling also helps at claim time. If a storm drops a tree across your driveway and damages both your car and the garage, having both policies through the same agency means one point of contact. Some carriers even apply a single deductible when one event damages both your home and your vehicle, which is worth asking about.
Your driving profile matters too. Commuting along US-224, the number of drivers in the household, and teen drivers all affect the auto side of the bundle. Our page on Boardman car insurancecovers the local driving factors in more detail.
Common Coverage Options and Limits Comparison
| Coverage | What It Covers | Typical Setup to Review |
|---|---|---|
| Dwelling (Coverage A) | Rebuilding the house | Full replacement cost at today's rebuild price |
| Roof settlement | Roof repair or replacement | Replacement cost vs. actual cash value |
| Water backup | Sump failure, sewer backup | Limit sized to finished basement contents |
| Wind/hail deductible | Storm damage out-of-pocket | Flat dollar vs. percentage of dwelling |
| Personal property | Furniture, electronics, clothing | Replacement cost, not depreciated value |
| Liability | Injuries and damage to others | Consider an umbrella for added protection |
| Auto bundle | Car and home together | Compare bundled vs. separate totals |
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Frequently Asked Questions About Boardman Insurance
Does homeowners insurance cover a flooded basement in Boardman? Only if the cause is covered. Sewer or sump backup needs a water backup endorsement, and rising surface water needs a separate flood policy.
Will my insurance drop me if my roof is old? It can happen. Many Ohio carriers restrict or non-renew homes with roofs over 15 to 20 years old, so shopping early gives you more options.
Do you insure homes near Southern Park Mall and the US-224 area? Yes. We cover homes throughout Boardman Township, including neighborhoods near Southern Park Mall and the US-224 commercial corridor.
How far is your office from Boardman? Our New Springfield office is about 15 minutes away. We also have a Zelienople, PA office, and most of the quoting and policy work can be handled by phone or online.
Can I get insured if my house has knob-and-tube wiring? It's harder, and many carriers will decline. Updating the wiring or panel usually opens up more companies and better terms.
Is bundling home and car always less expensive? Usually, but not always. We compare bundled and separate pricing so you can see the real difference.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
| Coverage | What It Protects | Common Gap to Watch |
|---|---|---|
| Homeowners | Dwelling, belongings, liability | High wind/hail deductibles |
| Renters | Belongings, liability, living costs | Low liability limits |
| Auto | Vehicle damage, injury liability | State minimum limits only |
| Motorcycle | Bike, gear, liability | Custom parts excluded |
| Boat | Hull, motor, liability on water | Trailer or navigation limits |
| Umbrella | Excess liability above other policies | Underlying limits too low |
| Life | Income replacement for family | Only employer coverage |
Consult with MVP Insurance at Our New Springfield Office
Boardman homes reward a careful review. Know your roof's age and settlement type, confirm your wiring and plumbing won't trip up underwriting, add water backup with a limit that fits your basement, and understand your wind/hail deductible in dollars. Then price your home and auto together and separately before deciding.
Call Josh Medure or David Varrati at our New Springfield office at (330) 707-9055, or reach our Zelienople office at (724) 453-1122, to go over your Boardman OH homeowners insurance. As an independent agency, we shop multiple carriers for the right fit for your property, not the policy that suits one insurer. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
If your renewal is coming up or your roof is getting older, now is a good time to compare. Start your quoteand we'll handle the legwork of finding coverage that holds up when the next storm rolls through.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.