


Owner, MVP Insurance
Condo and renters
If you own a condo, your association covers the building and you cover your unit, your belongings and your liability. Renters cover their belongings and liability only. Both policies cost less than most people expect.
Canfield homes tend to be larger, newer and often on acreage, so a basic policy can leave real gaps. The coverage pieces that matter most are replacement cost that matches modern construction, separate limits for barns and outbuildings, a water backup endorsement for finished basements, and liability limits high enough to protect what you've built.
That's the short version. The longer version depends on your street, your lot and what's in your basement.
Protecting Canfield OH Homeowners Insurance and Property Values
A home near the Route 11 corridor or a few minutes from the Mahoning County fairgrounds needs a policy built around its actual value. Generic limits rarely fit. Canfield has grown quickly, with larger homes, bigger lots and more finished square footage than many older Mahoning Valley neighborhoods. Policies written years ago often haven't kept up with that growth.
The numbers back this up. The average home value in Canfield reached $330,246 in August 2026, up 4.5% year over year. Median list prices for larger homes climbed past $405,000. Mahoning County also saw a 24% spike in property valuations during the recent reappraisal, and that shift should prompt a policy review.
MVP Insurance was founded in 2008 by Josh Medure and David Varrati as an independent agency. That means we compare policies from multiple carriers instead of selling one company's product. For Canfield homeowners, that matters because no single carrier handles every type of property well. A carrier that's great for a starter home in Boardman may be a poor fit for a four-bedroom build on three acres off Route 46.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Insuring Larger Homes and Newer Subdivisions
Newer Canfield homes cost more to rebuild than many owners expect, and your dwelling limit should reflect reconstruction cost, not purchase price or market value. These two numbers can drift far apart, especially with custom work.
Building costs explain why. New construction in Northeast Ohio typically runs $130 to over $300 per square foot in 2026, depending on finishes. A 3,500-square-foot home with quartz counters, custom millwork, a finished lower level and a three-car garage can land toward the top of that range. Run the math and the rebuild figure can easily outpace what the home sold for.
Standard policies fall short on custom builds for a few specific reasons:
- Automated estimators miss details. Many carriers calculate dwelling limits using software that assumes builder-grade materials. Coffered ceilings, stone exteriors and specialty windows get underweighted.
- Extended replacement cost isn't automatic. Some policies pay only up to the stated limit. An endorsement that adds 25% or more above the limit gives you a cushion if material and labor prices jump after a regional storm.
- Code upgrade costs are limited. Rebuilding to current Ohio code can add expense. Ordinance or law coverage pays for that, but default limits are often small.
At the upper end, specialized high value policies in Ohio typically target homes with reconstruction values starting around $1 million. Most Canfield homes sit below that line, which puts them in an awkward middle zone. They're too valuable for a bare-bones policy but not quite big enough for a high value program. That's where careful endorsement selection does the heavy lifting.

Written By
David Varrati
Owner, MVP Insurance
On this page
Multiple carriers
We quote your home, auto and other policies across the carriers we represent, look at how they pair for discounts, and show you the differences in coverage, not just the price.
Managing Acreage and Outbuildings
If you own several acres in Canfield or Canfield Township, your detached structures probably need more coverage than a standard policy provides. Most homeowners policies cap "other structures" at 10% of the dwelling limit. That sounds generous until you add up what's actually on the property.
Picture a home insured for $500,000. That gives you $50,000 for everything detached. A pole barn, a detached garage with a heated workshop, a fence line around a pasture and a shed full of equipment can blow past that number quickly. One fire in the barn could exhaust the whole limit and leave the fence and shed uncovered.
A few things we see trip people up on acreage:
- New structures never get reported. Someone builds a 40x60 pole barn in 2025 and the policy still reflects the property as it looked in 2019.
- Business use voids coverage. If the outbuilding houses a side business, a homeowners policy may exclude it. That needs separate commercial or home business coverage.
- Contents are a separate question. Your barn's structure and the tractor, mowers and tools inside it are covered under different parts of the policy, often with sub-limits.
- Farm activity changes the picture. Horses, livestock or selling hay can push you toward a farm or hobby farm policy.
The fix is straightforward. You can raise the other structures percentage or schedule specific buildings with their own limits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Pennsylvania FAIR Plan as a Last Resort
Some older homes can't find coverage in the voluntary market because of age, condition or a past claim. For those homes, the Pennsylvania FAIR Plan generally serves as the state's market of last resort for basic property insurance. It typically offers narrower protection than a standard homeowners policy and often lacks liability coverage. Treat it as a bridge while you update the roof, electrical or plumbing, then shop the regular market again.
Water Backup in Finished Basements
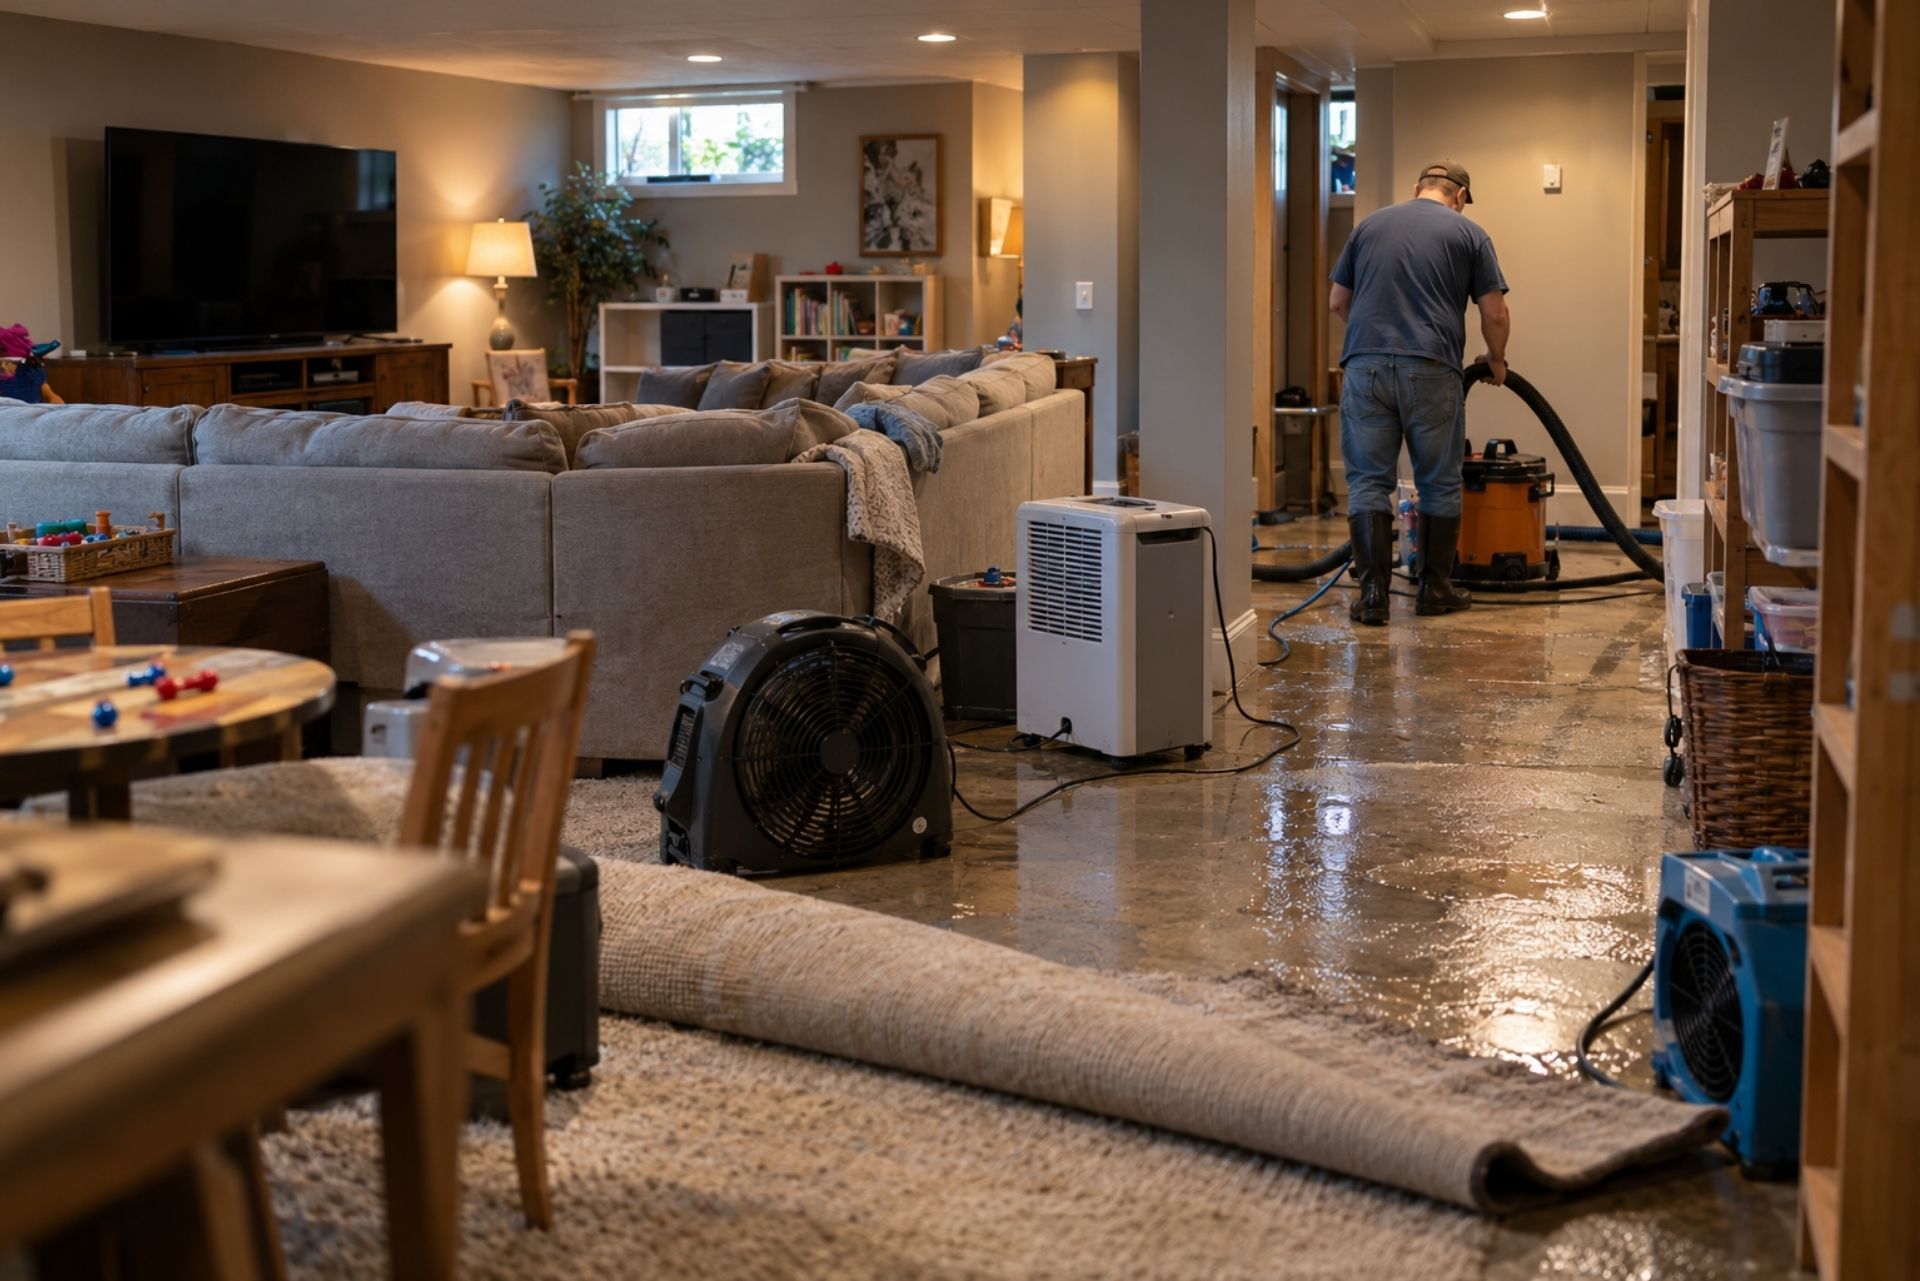
Most standard homeowners policies exclude water that backs up through drains or overflows from a sump pump. You need a separate endorsement to cover it. This is the single most common gap we find on Canfield policies, and it hurts most in homes with finished lower levels.
Think about what's down there in a typical newer build: carpet or luxury vinyl plank, drywall, a wet bar, a sectional, maybe a home theater setup. When a summer storm knocks out power and the sump pump stops, water rises fast. Sewer lines can also push water back up through floor drains when municipal systems get overwhelmed during heavy rain.
The July 2026 storms showed how quickly this becomes a personal problem. Mahoning County EMA noted that federal thresholds for individual FEMA assistance might not be met, with local public funds going toward community recovery instead. In plain terms, individual homeowners may not get disaster aid for their own basements. Your policy is the backstop.
Water backup endorsements come with their own limit, and the default amount is often too low for a fully finished basement. Price out what it would cost to replace your flooring, drywall and furnishings, then pick a limit that matches. A battery backup on your sump pump is also a smart, low-cost move that some carriers reward. One more thing: backup coverage is different from flood insurance, which covers surface water from outside and is purchased separately.
Why Higher Liability Limits Matter
Homeowners with significant assets should carry liability limits above $300,000, and many should add an umbrella policy on top. Lawsuits target what you own, and a Canfield household with home equity, retirement accounts and college savings presents a much bigger target than the default limit was designed to protect.
Consider the everyday risks on a larger property. Teenagers using a backyard pool. A guest falling on the deck stairs. A neighbor's kid hurt on a trampoline or riding a golf cart across your acreage. A dog bite during a graduation party. Serious injury claims involving medical bills, lost wages and pain and suffering can climb well past $300,000, and anything above your limit can come out of your own pocket.
An umbrella policy sits above both your homeowners and auto liability. It typically starts at $1 million and is usually affordable compared to the protection it provides. Carriers generally require you to carry certain underlying limits on home and auto first, so the two policies need to be coordinated. If you're reviewing your home policy, it makes sense to look at car insurance in Canfieldat the same time so the limits line up and nothing falls through the gap.
Comparing Coverage Options for Canfield Residents
The right setup depends on your home's size, lot and lifestyle. Here's how a basic policy typically compares with one tailored to a larger, newer Canfield property.
| Coverage Area | Basic Policy | Tailored for Canfield |
|---|---|---|
| Dwelling | Estimator-based limit | Rebuild cost with extended replacement |
| Other structures | 10% of dwelling | Raised percentage or scheduled buildings |
| Water backup | Usually excluded | Endorsement sized to finished basement |
| Liability | Often $100K to $300K | $500K or more, plus umbrella |
| Ordinance or law | Small default limit | Higher limit for code upgrades |
| Personal property | Sub-limits on jewelry, art | Scheduled valuables |
The point of a comparison like this isn't to load up on every add-on. It's to match coverage to what you actually own. A ranch on a quarter acre with an unfinished basement doesn't need the same policy as a two-story build on five acres with a pole barn.
As an independent agency, we shop these options across several carriers. You can read more about how we approach homeowners insurance in Ohioand what drives pricing statewide. Then compare that with the specific risks on your own property.
Common Questions About Canfield OH Homeowners Insurance
How does the CanfieldFair affect my local risk?The Canfield Fair runs Labor Day weekend at the Mahoning County fairgrounds and brings heavy traffic, parked cars and visitors into nearby neighborhoods. If you host guests or let people park on your property, your liability exposure goes up, which is one more reason to carry solid limits.
Does my policy cover new outbuildings? Usually yes, under the other structures portion, but only up to that limit, which is often 10% of your dwelling coverage. Report new barns, garages or sheds to your agent so the limit can be raised to fit.
What is water backup coverage?It's an endorsement that pays for damage when water backs up through drains or a sump pump fails. Most standard policies exclude it, so you have to add it.
Is my home insured for what I paid for it?Not necessarily, and it shouldn't be. Your dwelling limit should reflect what it costs to rebuild, which can be higher or lower than your purchase price.
Do I need an umbrella policy?If your assets exceed your liability limits, an umbrella is worth considering. It adds a layer of protection above your home and auto policies, typically starting at $1 million.
How do I reach the New Springfield office?Our Ohio office is at 13823 Grant St, New Springfield, OH 44443. You can call (330) 707-9055.
Canfield homes have grown in size and value, and a lot of policies haven't caught up. The biggest gaps we see are predictable: rebuild limits that miss custom finishes, outbuildings squeezed under a 10% cap, finished basements with no backup coverage, and liability limits that wouldn't survive a serious lawsuit. Fixing them usually takes one careful review, not a complete overhaul.
If it's been a few years since anyone looked closely at your policy, now is a good time. MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH, and we'll compare options across multiple carriers for you. Start your quoteand we'll help you build coverage that fits the home you actually own.
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













