


Zelienople PA Homeowners Insurance

Owner, MVP Insurance

Zelienople homeowners face a mix of risks you won't find in a generic policy quote: a creek that rises fast in spring, brick houses built long before modern building codes, and coal seams under parts of Butler County. A policy that works for a 2005 vinyl colonial in Cranberry can leave serious gaps on a 1920s brick home off Main Street.

Protecting Your Assets with Zelienople PA Homeowners Insurance

Zelienople homeowners insurance protects your house, belongings, and liability when a covered event like fire, wind, hail, or theft causes damage. Flooding and mine subsidence are excluded unless you add separate coverage. For older brick homes, the policy also needs a rebuild figure based on construction costs rather than sale price.


MVP Insurance is an independent agency located at 108 E Grandview Ave, Zelienople, PA 16063, and you can reach the office at (724) 453-1122. If the building looks familiar, that's because it was formerly Griffin Insurance. Because MVP is independent, the team compares policies from multiple carriers. You don't have to accept whatever one company decides to offer.


That matters here more than in many towns. A carrier that prices a newer home well may be strict about knob-and-tube wiring, slate roofs, or homes close to the water. Comparing several carriers side by side usually shows which ones understand older Butler County housing stock. For a broader look at statewide coverage rules, see our guide to Pennsylvania homeowners insurance.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Managing Connoquenessing Creek Flood Exposure

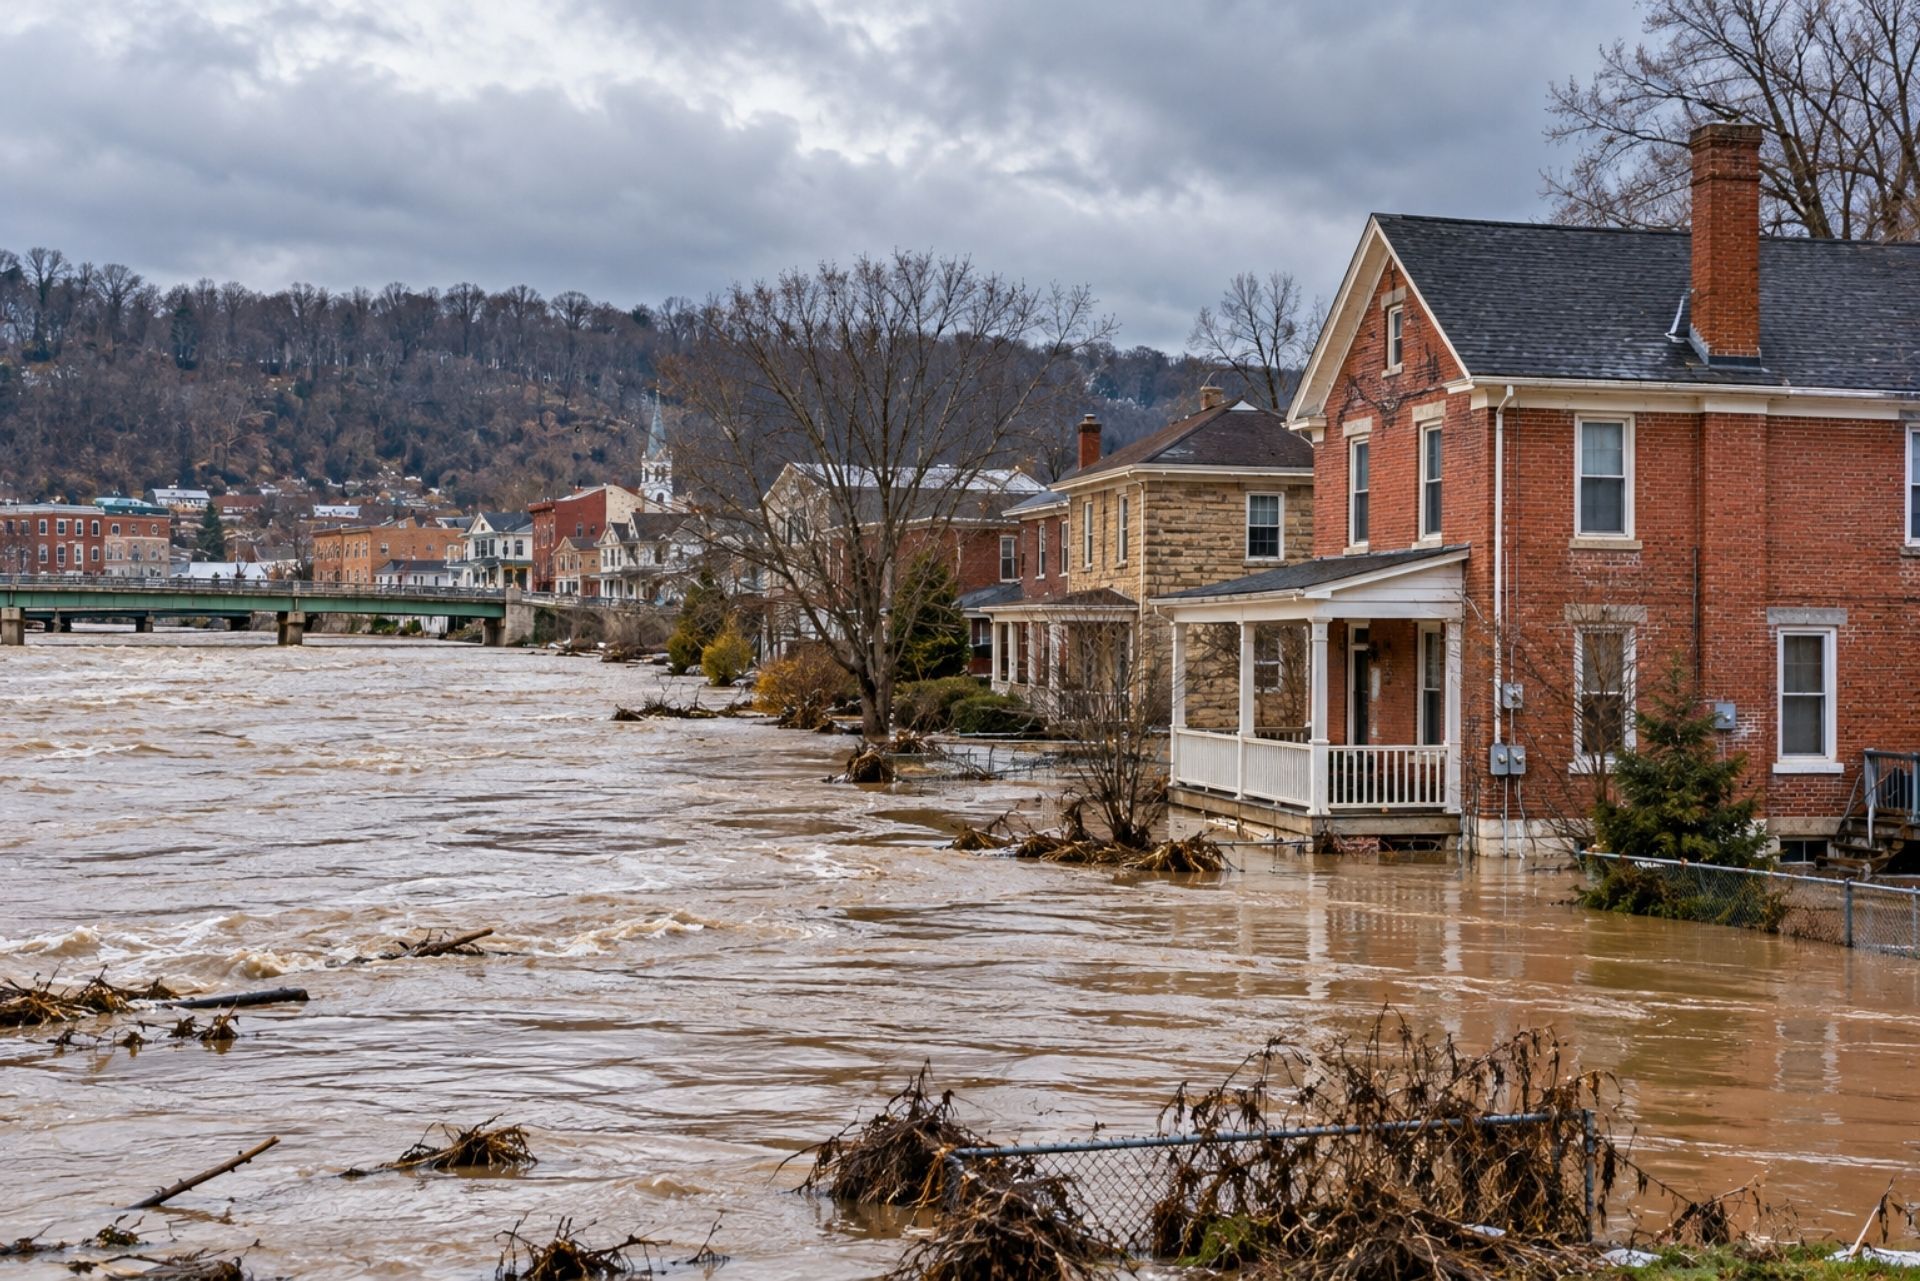
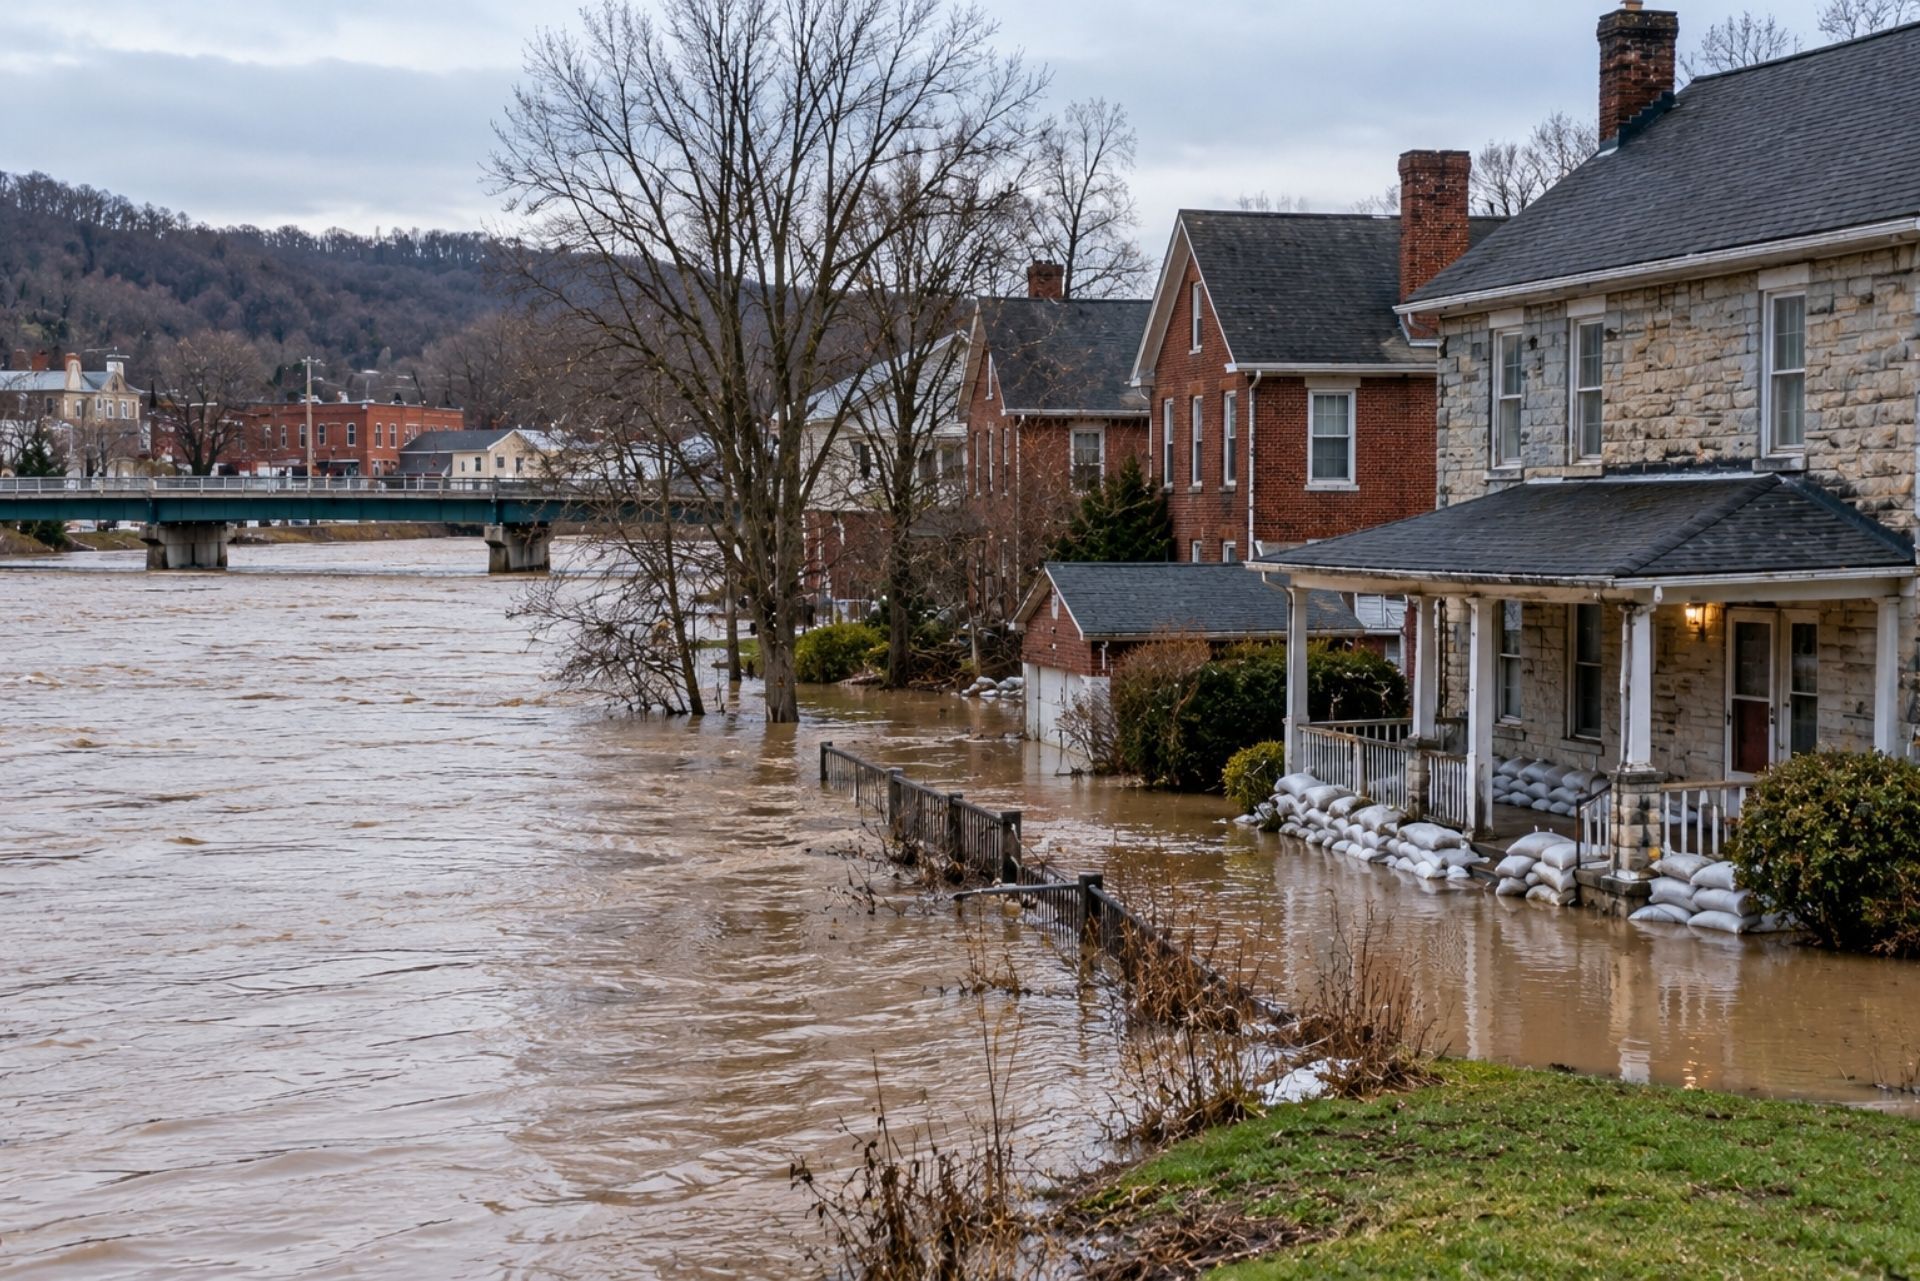
Standard homeowners policies do not cover flood damage from the Connoquenessing Creek, period. If water rises from the creek and enters your basement or first floor, your homeowners carrier will deny the claim. You need a separate flood policy, either through the National Flood Insurance Program or a private flood carrier.


The most common mistake we see is assuming "I'm not in a flood zone, so I'm fine." Flood maps lag behind real conditions. Heavy rain overwhelms storm drains and pushes water into neighborhoods that sit outside the mapped high-risk areas. Neighboring Harmony recently finished an $898,000 stormwater project to reduce flooding on Mercer Street and improve drainage into the creek. That's a clear sign local officials take runoff seriously, and homeowners should too.


How close you are to the water should drive the decision:


  • Creekside or low-lying lots: A flood policy is strongly advised, and your lender may require one.
  • A few blocks away, on lower ground: Get a quote. Premiums outside high-risk zones are often modest.
  • Higher elevation: Consider a sewer and drain backup endorsement, which is a different coverage than flood.


One more gap: NFIP policies typically have a waiting period before coverage starts. Don't wait for a storm forecast to buy one.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Insuring Historic Homes Near Main Street and Harmony

Historic homes need coverage that pays to restore original architectural details, not just patch them with modern substitutes. That includes plaster walls, hand-cut stone, wood trim, and period windows. Many homes near Main Street and the Harmony National Historic Landmark District carry exactly these features.


Harmony adds a regulatory layer. Owners inside the district must get a Certificate of Appropriateness from the Historic Architectural Review Board before making exterior alterations or additions. The board exists to protect the district's historic character. After a fire or windstorm, you may not be allowed to swap slate for asphalt shingles or replace wood windows with vinyl. Rebuilding to those standards costs more and takes longer.


That's where ordinance or law coverage comes in. Standard policies often provide only a small percentage for code and ordinance upgrades, which can run out quickly on a historic rebuild. Ask your agent to raise that limit, and confirm your loss-of-use coverage can handle a longer repair timeline.


Families in the Seneca Valley School District often buy older homes for the walkable neighborhoods and character. Before closing, have an agent review the roof, wiring, and heating system. Those three items decide which carriers will write the policy.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

The Importance of Mine Subsidence Checks in Butler County

Before you buy or renew, check whether abandoned coal mines lie beneath your property. Mine subsidence is excluded from standard Pennsylvania homeowners policies and is available as separate, optional coverage. Damage from ground collapsing into old mine voids can crack foundations, shift walls, and break utility lines, and your regular policy won't pay for it.


Pennsylvania runs a state-administered mine subsidence insurance program. Coverage details and pricing can change, so confirm current terms before you rely on any figure (verify at publish). The state also offers mapping tools that show known mined areas. These maps aren't perfect, since some older workings were never fully recorded.


Here's a practical approach:


  1. Look up your address on the state's mine map resources.
  2. Ask the seller or neighbors about past settlement problems or repaired foundation cracks.
  3. Watch for warning signs: sticking doors, diagonal wall cracks, or uneven floors that appear suddenly.
  4. Ask your agent to price the coverage even if the map shows nothing nearby.


Brick homes are especially vulnerable because masonry doesn't flex. A small shift that a wood-frame house might absorb can split a brick wall from foundation to eave.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Home

A homeowners policy rebuilds your house after a fire or storm, replaces your belongings, and pays if someone is hurt on your property. We check the rebuild cost against local construction prices so you are not short when it matters.

Replacement Cost Challenges on Older Brick Homes

Rebuilding an older brick home with original materials often costs far more than the house would sell for. A 1915 home on a modest lot might list for a reasonable price, but reconstructing solid structural brick walls, plaster, and custom millwork can exceed that figure by a wide margin. Insuring to market value leaves you short.


Labor drives much of the gap. Experienced masons in Pennsylvania charge roughly $75 to $109 per hour as of 2026, and solid brick work is slow, skilled labor. Add matching reclaimed brick, lime-based mortar, and plaster crews, and costs climb fast.


You generally have two paths. Full replacement cost pays to rebuild with like kind and quality, which suits historic homes and anyone in Harmony's district. Functional replacement cost pays to rebuild with modern materials that serve the same purpose, such as brick veneer over a frame wall instead of solid structural brick. Functional coverage costs less, but it won't match the original. It may also fail to satisfy a historic review board.


An extended or guaranteed replacement cost endorsement adds a cushion above your dwelling limit. That's valuable when material prices jump after a regional storm.

Comparing Coverage Options for Zelienople Residents

Coverage Feature Standard Policy Specialized Endorsement
Dwelling rebuild Rebuilds to stated limit Extended replacement adds a buffer above the limit
Materials used Often modern equivalents Like kind and quality (original style)
Brick construction May price as veneer Accounts for solid structural masonry
Code and ordinance Small percentage of dwelling Higher limits for historic or code upgrades
Flood Excluded Separate flood policy required
Mine subsidence Excluded Optional Pennsylvania coverage
Sewer backup Usually excluded Available as an add-on

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Common Questions About Zelienople Home Insurance

Does homeowners insurance cover flooding from the Connoquenessing Creek?No. Creek flooding requires a separate flood policy, even if your home sits outside a mapped flood zone.


How do I know if I'm in a flood zone in Zelienople?Check the FEMA flood maps for your address, then ask an agent to review your elevation and distance from the creek. Being outside a mapped zone doesn't mean zero risk.


Is mine subsidence insurance required in Pennsylvania?No, it's optional. Many Butler County homeowners still buy it because standard policies exclude damage from old mine collapse.


Does living in Harmony's historic district raise my insurance?It can, because repairs must meet review board standards and often take longer. Higher ordinance or law limits help cover those added costs.


Should I insure my brick home for what I paid for it?Usually not. Insure for the cost to rebuild, which on older brick homes often exceeds market value.


Can I bundle home and car insurance in Zelienople?Yes, and bundling often lowers your combined premium. See our page on Zelienople car insurancefor auto details.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Coverage What It Protects Common Gap to Watch
Homeowners Dwelling, belongings, liability High wind/hail deductibles
Renters Belongings, liability, living costs Low liability limits
Auto Vehicle damage, injury liability State minimum limits only
Motorcycle Bike, gear, liability Custom parts excluded
Boat Hull, motor, liability on water Trailer or navigation limits
Umbrella Excess liability above other policies Underlying limits too low
Life Income replacement for family Only employer coverage

Consulting with Local Independent Agents at MVP Insurance

The right policy for a Zelienople home depends on specifics: your distance from the creek, what's under the ground, whether your walls are solid brick or veneer, and whether a review board will weigh in on repairs. A national call center won't ask those questions. A local agent will.


Josh Medure and David Varrati founded MVP Insurance in 2008, and they're glad to review your property's risks with you in person or by phone. Visit the Zelienople office at 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122. You can also reach the New Springfield office at 13823 Grant St, New Springfield, OH 44443, (330) 707-9055. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


Bring your current declarations page and any notes about your home's age, roof, and foundation. If you'd like a head start, request your quoteonline and the team will compare carriers for you. A short conversation now costs far less than finding a coverage gap after the creek rises or a wall cracks.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








