

Owner, MVP Insurance
Coverage
Columbus drivers get the right car insurance by comparing several carriers at once, then setting limits that fit Franklin County's real risks. Those risks include heavy I-270 and I-70 traffic, a fast-growing population, Ohio State students living away from home, and a meaningful share of uninsured drivers. An independent agent can do that comparison for you.
That is the short version. The longer version matters because Columbus is not the same city it was ten years ago. New subdivisions keep spreading toward Delaware, Pickerington, and Grove City. Warehouse traffic keeps growing near Rickenbacker. Every August, thousands of students arrive with cars registered at a parent's address two counties or two states away.
All of that shapes what a claim looks like here. A fender bender at the 315 interchange, a stolen catalytic converter in a campus lot, and an injury crash with a driver who has no insurance at all each need different parts of your policy. Below, we walk through each local risk, what the state requires, what we suggest instead, and the common mistakes that leave Columbus households paying out of pocket.
Finding Reliable Columbus OH Car Insurance for Local Drivers
The most dependable way to find Columbus OH car insurance is to work with an independent agency that quotes multiple carriers side by side, rather than calling one company at a time. MVP Insurance, founded in 2008 by Josh Medure and David Varrati, does exactly that for drivers across Ohio and Pennsylvania. You share your details once, and the agency shops the market for you.
Why does that matter so much in Columbus? Carriers price the same driver very differently depending on how they view Franklin County ZIP codes, commute distance, and claim history. A household in Hilliard might see one carrier come in well above another for nearly identical coverage. If you only check one or two companies, you never see that spread.
Being independent also changes whose side the agent is on. MVP works for the client, not for any single carrier, so the goal is a policy that actually fits your life instead of whatever one company happens to sell. The agency also uses modern tools and apps to make managing your policy easier, and claims support is available 24/7.
Here is what to have ready before you request quotes:
- Your current declarations page so limits can be matched or improved
- Driver's license numbers for everyone in the household
- VINs and annual mileage for each vehicle
- Garaging address (especially important for students or second homes)
- Any accidents or tickets from the last three to five years
With those in hand, a comparison usually moves quickly and keeps the process low-stress.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Navigating I-270 and I-70 Commuting Risks
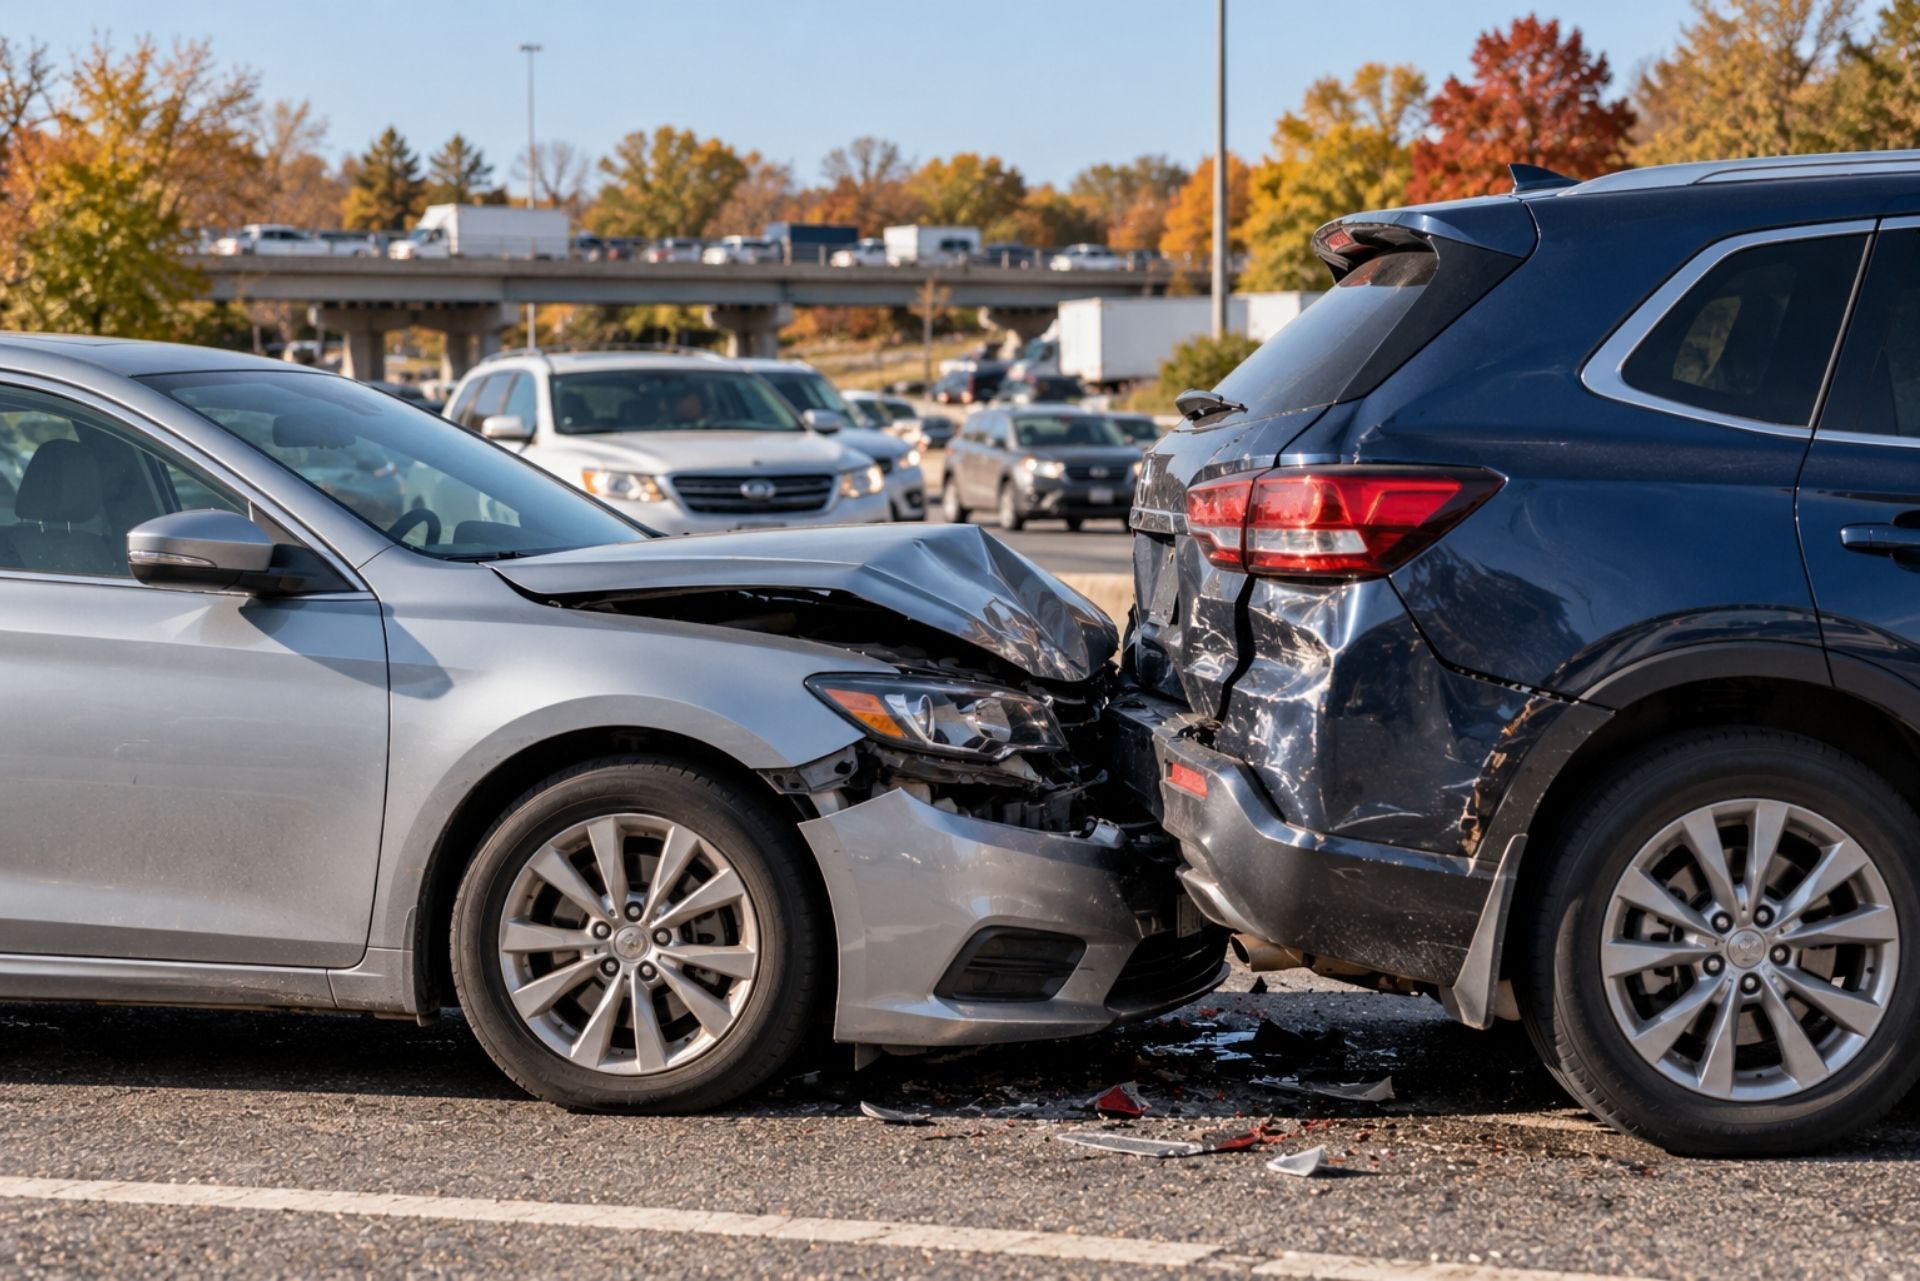
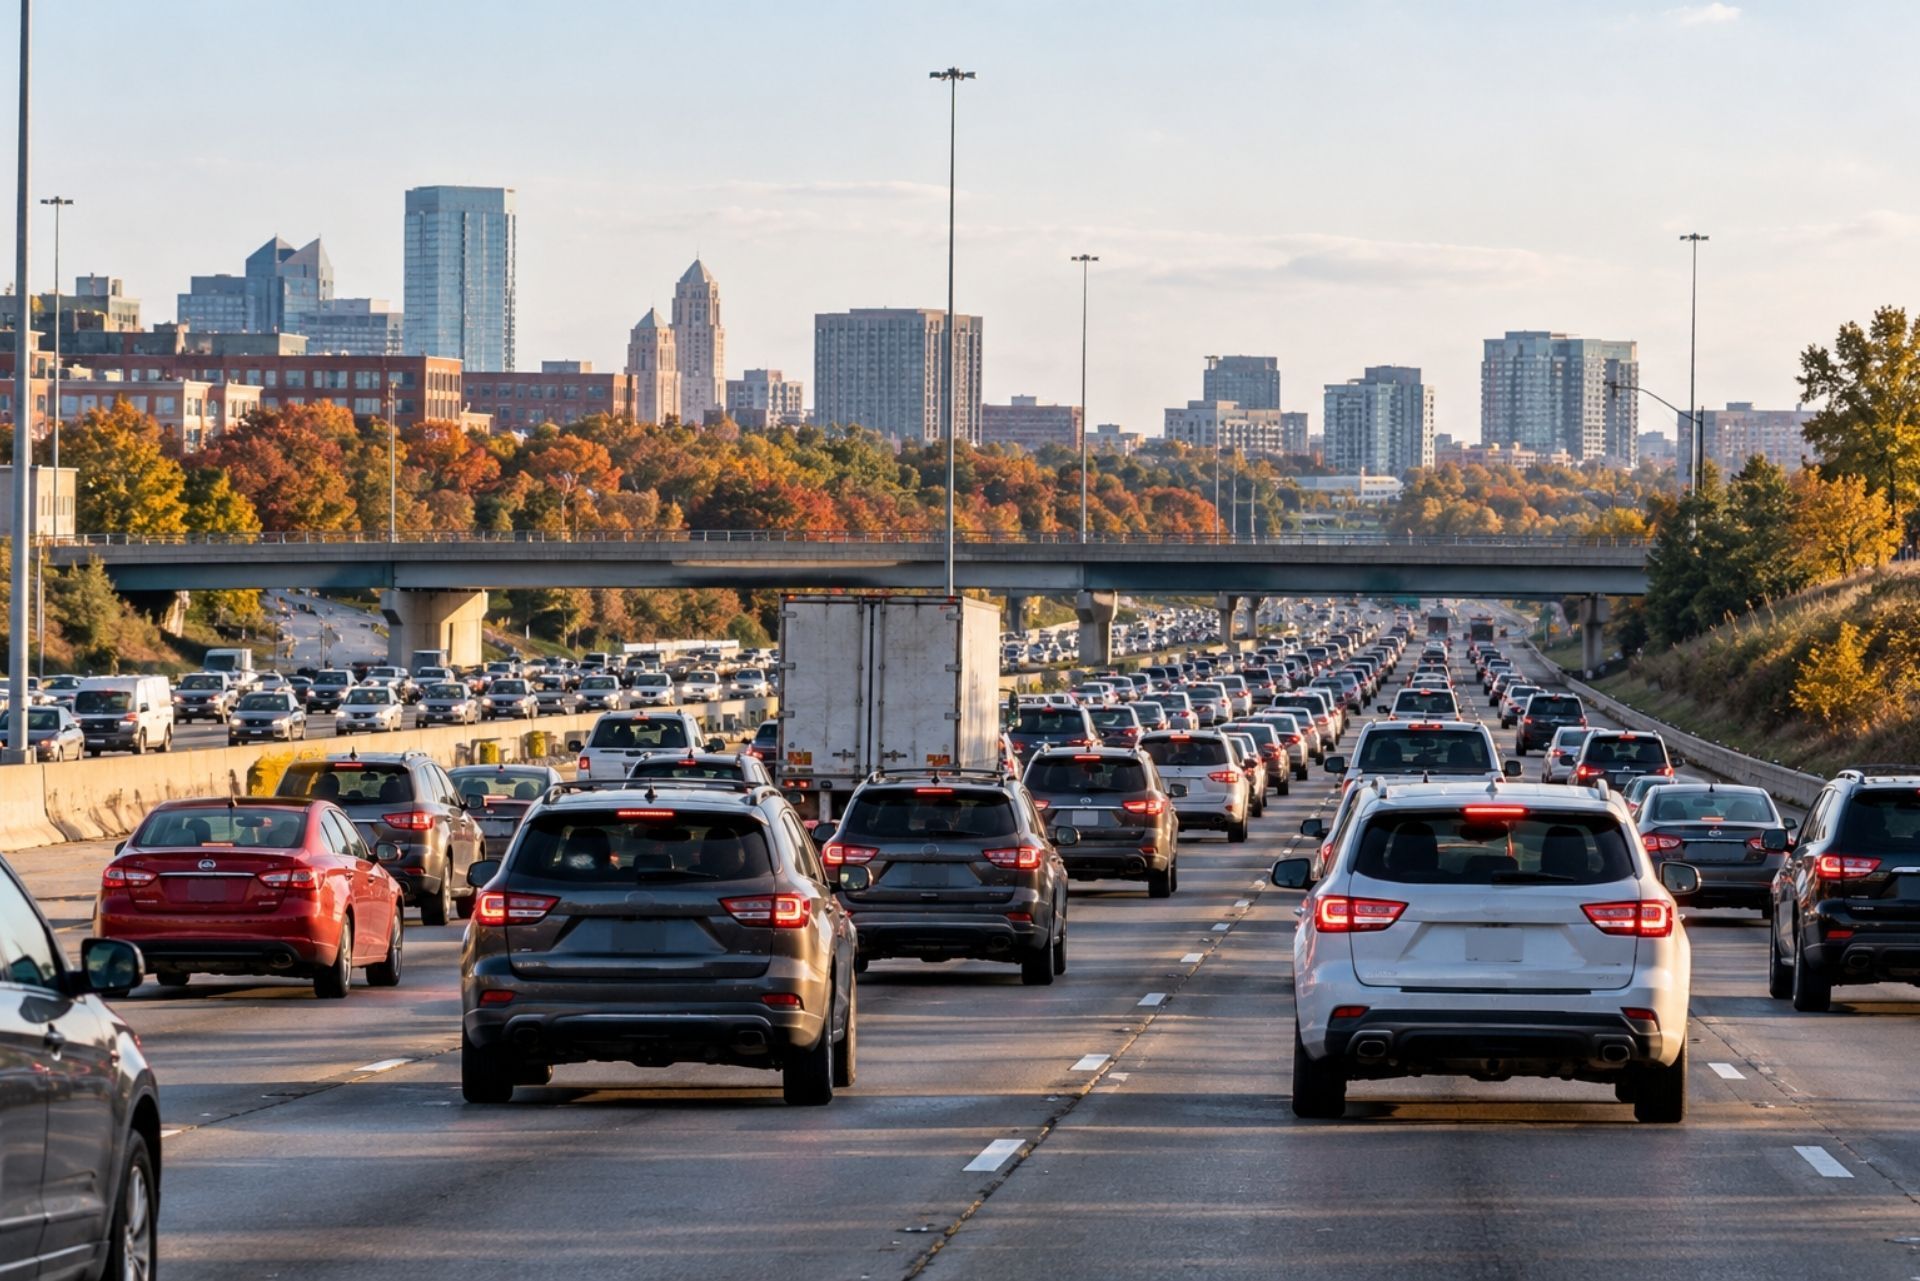
Heavy traffic on I-270 and I-70 raises both your odds of a claim and the way carriers price Franklin County policies. More hours in stop-and-go traffic means more exposure to rear-end collisions, merge crashes, and chain-reaction accidents, and insurers track that exposure closely.
The numbers on congestion are hard to ignore. Columbus metro drivers spend an average of 2.5 hours each weekday dealing with traffic delays, a figure that shows up again in local discussions about how traffic in Columbus feels day to day. That is a lot of time spent in exactly the conditions where low-speed collisions happen.
The outerbelt is its own animal. I-270 loops roughly 55 miles around the city, and the interchanges at SR-315, US-23, I-71, and I-70 funnel commuters, delivery vans, and semis into tight merge zones. On I-70, the downtown split with I-71 has long been a stress point for drivers heading east toward Reynoldsburg or west toward the airport.
What does this mean for your policy? A few practical points:
- Commute miles count. Reporting accurate annual mileage helps, since an underestimate can create problems at claim time.
- Rear-end claims are common. Collision coverage pays for your car when you hit someone in slowing traffic.
- Multi-car pileups get messy. Higher liability limits protect you when several vehicles and injured people are involved.
If you've switched to hybrid or remote work since your last renewal, tell your agent. Fewer commuting days can change how a carrier rates you.
Fast Growth and Rising Accident Rates in Franklin County
Columbus is the fastest growing metro in Ohio, and more residents generally means more cars, more congestion, and more opportunities for crashes. How closely the population surge tracks with rising local accident rates is something we'd suggest confirming with the latest state crash data when you review your policy, because yearly figures shift.
What you can see without a spreadsheet is the pattern on the ground. New housing in Delaware County, Canal Winchester, and the western suburbs puts more drivers on roads that were built for lighter traffic. Construction zones pop up and move around. Two-lane roads that used to feel rural now carry commuter volume at rush hour.
From an insurance standpoint, growth affects you in two ways. First, carriers price for claim frequency in an area, so a busier region tends to push premiums upward over time. Second, the cost of each claim has climbed as vehicles carry more sensors, cameras, and electronics that are expensive to repair after even a minor hit.
One mistake we see often: people who moved to Columbus from a smaller Ohio town keep the same limits they had back home. A policy that felt fine in a quiet county can leave real gaps in a metro where injury claims and repair bills run higher. If you've relocated within the last few years, it's worth a fresh look at your liability limits and your collision deductible.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
Specialized Coverage for Ohio State Students
Ohio State students usually have three options: stay on a parent's policy, buy their own, or skip bringing a car altogether. For most families, keeping the student on the household policy with the correct garaging address is the simplest and most affordable route, but the details matter.
Start with where the car actually lives. If a student keeps a vehicle in a lot near campus for nine months, the carrier needs to know it's garaged in Columbus, not at home in Youngstown or Pittsburgh. Listing the wrong address can create a claim dispute later, and that's a headache no family wants in the middle of a semester.
Theft and vandalism are real campus concerns. Motor vehicle thefts held steady at 70 reported incidents on or near the Ohio State campus in the latest annual security report. Comprehensive coverage is what pays if a car is stolen or broken into, so dropping it to save money on an older student car is a gamble worth thinking through.
Seasonal driving habits also matter. A few things to consider:
- Distant student options: Some carriers offer reduced rates when a student attends school far from home without a car.
- Good grades: Many carriers reward solid GPAs, so ask about it.
- Summer driving: Students often drive more in summer and over breaks, so make sure coverage stays active year-round.
- Friends borrowing the car: Permissive use rules vary by policy; know yours before handing over keys in a crowded campus area.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Deductibles are where you can trim premium without gutting protection. Industry voices suggest raising deductibles to $1,000 to offset higher urban base rates. Just make sure you can actually pay that amount after a February break-in.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Protecting Older Housing Stock and Garaged Vehicles
Cleveland's older housing stock creates an auto insurance angle people don't expect. Many homes in Ohio City, Tremont, Slavic Village, and the inner-ring suburbs have detached garages built decades ago, often narrow, aging, or unusable for modern vehicles. That pushes cars onto driveways and streets, which raises theft and weather exposure.
If your garage does house your car, its condition matters. A collapsed roof from heavy snow damages the vehicle (a comprehensive auto claim) and the structure (a homeowners claim). Coordinating both policies avoids finger-pointing between coverages, and Cleveland residents can save up to 20% by bundling auto with homeowners or renters policies.
Review your homeowners insurance options in Cleveland alongside your Ohio car insurance coverage so the gaps between them close.
Why Uninsured Motorist Protection is Essential in Columbus
Uninsured motorist coverage is essential in Columbus because a large share of drivers may not carry the insurance Ohio requires. If one of them hits you, this coverage pays for your injuries and related losses so you are not stuck chasing someone who cannot pay.
The gap is bigger than most people assume. Legal experts strongly advise Columbus drivers to carry UM/UIM coverage, since nearly 1 in 5 drivers in the city may lack state-required minimums. In a metro packed with commuters, that means the odds of sharing I-270 with an uninsured driver on any given morning are high.
Underinsured coverage solves a related problem. Picture this: a driver carrying only the state minimum causes a crash that sends you to Riverside or Wexner Medical Center for surgery and weeks off work. Their $25,000 bodily injury limit can disappear fast. Underinsured coverage steps in for the difference, up to your own limits.
Lawmakers are working on enforcement. Ohio House Bill 678 proposes a real-time online system that lets law enforcement instantly verify insurance status. To fund it, the bill includes optional "Blackout" license plates carrying a $40 fee, a detail you can see in the text of the proposed legislation. Until something like that passes and takes effect, though, your own UM/UIM limits are your real protection. We generally suggest matching them to your liability limits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
These suggestions are a starting point, not a universal rule. Your agent can tailor them to your assets, vehicles, and budget.
Ohio Minimum Liability Requirements vs Recommended Limits
Ohio requires every driver to carry at least 25/50/25 in liability coverage, but those minimums rarely cover a serious Columbus crash. Most households with a home, savings, or steady income should carry considerably more.
Here's a simple side-by-side:
| Coverage | Ohio Minimum | Suggested for Columbus |
|---|---|---|
| Bodily injury (per person) | $25,000 | $100,000 or more |
| Bodily injury (per accident) | $50,000 | $300,000 or more |
| Property damage | $25,000 | $100,000 |
| Uninsured/underinsured motorist | Not required | Match your liability limits |
| Comprehensive | Not required | Yes, for most vehicles |
| Collision | Not required | Yes, for financed or newer cars |
| Umbrella policy | Not required | Consider if you own a home |
These suggestions are a starting point, not a universal rule. Your agent can tailor them to your assets, vehicles, and budget.
Bodily Injury and Property Damage Limits
Bodily injury liability pays for other people's medical bills and lost income when you cause a crash. At $25,000 per person, one ambulance ride, an ER visit, and a short hospital stay can come close to exhausting it. Anything above your limit can become your personal responsibility.
Property damage limits get tested more often than people expect. A $25,000 limit may not cover a newer pickup or SUV, let alone damage to multiple cars in an outerbelt pileup. Raising this limit usually costs relatively little compared with the protection you gain.
Comprehensive and Collision Options
Collision covers damage to your own car after a crash, regardless of fault. Comprehensive handles nearly everything else: theft, hail, deer strikes on rural roads outside the outerbelt, falling branches, and broken glass. If your car is financed or leased, the lender almost certainly requires both.
Your deductible is the main lever here. A higher deductible lowers your premium, but only choose one you could pay tomorrow without stress. For older cars worth a few thousand dollars, dropping collision can make sense. Comprehensive often stays worthwhile given theft risk in busy neighborhoods.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
How Stacking Protects Multi-Vehicle Households
Say your household insures three cars, each with $50,000 in underinsured motorist coverage. Stacked, an injured family member could typically access up to $150,000. Unstacked, they get $50,000.
Here's where stacking usually makes the most sense:
- Households with two or more vehicles, since each added car increases the available limit
- Families without strong disability coverage who would struggle if a breadwinner couldn't work
- Drivers who chose limited tort, because uninsured motorist claims can help offset restricted lawsuit rights
- Commuters on busy corridors where uninsured drivers are more common
Single-car owners get less benefit from stacking, so unstacked may be reasonable there.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Bundling Columbus OH Car Insurance with Homeowners Policies
Bundling your auto and home coverage with the same carrier often lowers your combined premium and simplifies billing, renewals, and claims. For Columbus homeowners in places like Westerville, Dublin, or German Village, it's usually one of the easiest savings to find.
The convenience goes beyond price. One renewal date, one point of contact, and fewer gaps between policies. Some carriers also offer a single deductible when the same event damages both your home and your car, such as a tree falling on the garage during a summer storm.
Bundling isn't automatically the right move, though. Sometimes one carrier is strong on auto but priced high on home, and splitting the policies saves more. That's where an independent agency earns its keep: MVP can compare bundled and unbundled options across multiple carriers and show you the actual numbers.
If you want more detail on statewide auto requirements and options, our guide to car insurance in Ohiocovers the basics. And for coverage on the house itself, including dwelling limits and liability, see our page on homeowners insurance in Ohio. Renters near campus or downtown can often bundle too, since renters policies pair well with auto.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
These suggestions are a starting point, not a universal rule. Your agent can tailor them to your assets, vehicles, and budget.
Frequently Asked Questions About Columbus Insurance
How much car insurance do I need in Columbus, Ohio? Ohio requires 25/50/25 liability, but most Columbus drivers should carry more. Limits around 100/300/100, plus matching uninsured motorist coverage, are a common starting point.
Does commuting on I-270 raise my car insurance? It can. Carriers consider mileage and local claim trends, and heavy outerbelt traffic contributes to higher claim activity in Franklin County.
Why is car insurance in Columbus higher than in small Ohio towns? Busier roads, more crashes, more theft, and higher repair costs all play a role. Rural areas usually have fewer claims per driver.
Can an Ohio State student stay on their parents' car insurance? Usually, yes. Just make sure the carrier knows the car is kept in Columbus during the school year.
Do I really need uninsured motorist coverage in Ohio? It isn't required, but it's strongly recommended. A large share of Columbus drivers may lack proper insurance, and this coverage pays your bills if one of them hits you.
Will bundling home and auto always save money? Often, but not always. Comparing both options across several carriers is the only way to know for sure.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
How Stacking Protects Multi-Vehicle Households
Say your household insures three cars, each with $50,000 in underinsured motorist coverage. Stacked, an injured family member could typically access up to $150,000. Unstacked, they get $50,000.
Here's where stacking usually makes the most sense:
- Households with two or more vehicles, since each added car increases the available limit
- Families without strong disability coverage who would struggle if a breadwinner couldn't work
- Drivers who chose limited tort, because uninsured motorist claims can help offset restricted lawsuit rights
- Commuters on busy corridors where uninsured drivers are more common
Single-car owners get less benefit from stacking, so unstacked may be reasonable there.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Contact MVP Insurance for a Quote in Columbus
Columbus keeps growing, and so do the risks that come with it: crowded outerbelt commutes, more cars on suburban roads, campus parking lots with real theft exposure, and too many drivers without proper coverage. The fix isn't buying the bare minimum and hoping. It's carrying limits that match your life, keeping uninsured motorist coverage strong, and checking your policy whenever your commute, address, or household changes.
If you'd like someone to do the comparison for you, start your quotewith MVP Insurance. We'll shop multiple carriers, explain the trade-offs in plain language, and help you pick coverage you understand.
You can reach either office directly:
- Pennsylvania office:108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122
- Ohio office:13823 Grant St, New Springfield, OH 44443, (330) 707-9055
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293. A short conversation now can save you from learning about a coverage gap at the worst possible moment.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.