


Cranberry Township PA Homeowners Insurance

Owner, MVP Insurance

Cranberry Township homeowners insurance needs to do three jobs well: carry a dwelling limit high enough to rebuild a newer home at today's prices, cover the finished basement that a standard policy leaves exposed to sewer backup, and handle frequent hail and wind claims without a painful deductible. For growing families, pairing it with auto coverage often ties the whole plan together.


That's the short version. The longer version depends on when your home was built, what's below the main floor, and how many drivers are about to share your driveway.

Cranberry Township PA Homeowners Insurance for Growing Families

Insurance in Cranberry Township has to keep pace with a community that keeps adding rooftops. It is one of the fastest-growing townships in western Pennsylvania, and that growth affects rebuild pricing, contractor availability and the number of homes exposed when a storm rolls through Butler County.


Location shapes a lot of this. The township sits at the I-79, I-76 Turnpike and Route 19 interchange, so many residents commute daily and rack up real mileage. The Route 228 business corridor brings retail, offices and steady construction. All of that matters for both your home and auto policies. Busy roads mean more driving exposure. Ongoing building means local labor and materials stay in demand.


A policy written five years ago for a home in a new plan off Rochester Road or Freedom Road may no longer match what it would cost to rebuild today. That's the starting point for every review we do here.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Newer Subdivisions and Rebuild Costs in Western Pennsylvania

Newer homes in Cranberry Township often need higher replacement cost limits than owners expect. Open floor plans, nine-foot ceilings, upgraded trim, quartz counters and attached garages all add to rebuild cost. Current labor and material prices in a fast-growing market push that number higher still.


The most common mistake is anchoring the dwelling limit to the purchase price or the mortgage balance. Neither one tells you what a contractor would charge to rebuild after a total loss. Industry reports from 2025-2026 suggest that two out of three U.S. homes are underinsured because dwelling limits haven't kept up with rising costs. A shortfall like that only shows up on the worst day of your life.


A few things worth checking on your declarations page:


  • Replacement cost, not actual cash value, on the dwelling
  • Extended or guaranteed replacement cost, which adds a cushion above your limit
  • Building code (ordinance or law) coverage for upgrades required during a rebuild
  • Inflation guard, so limits adjust at each renewal


MVP Insurance is right next door in Zelienople at 108 E Grandview Ave, so we know these subdivisions well. We can run a fresh replacement cost estimate that reflects your actual finishes rather than a generic square-foot guess.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Basement Finishes and Water Backup Protection

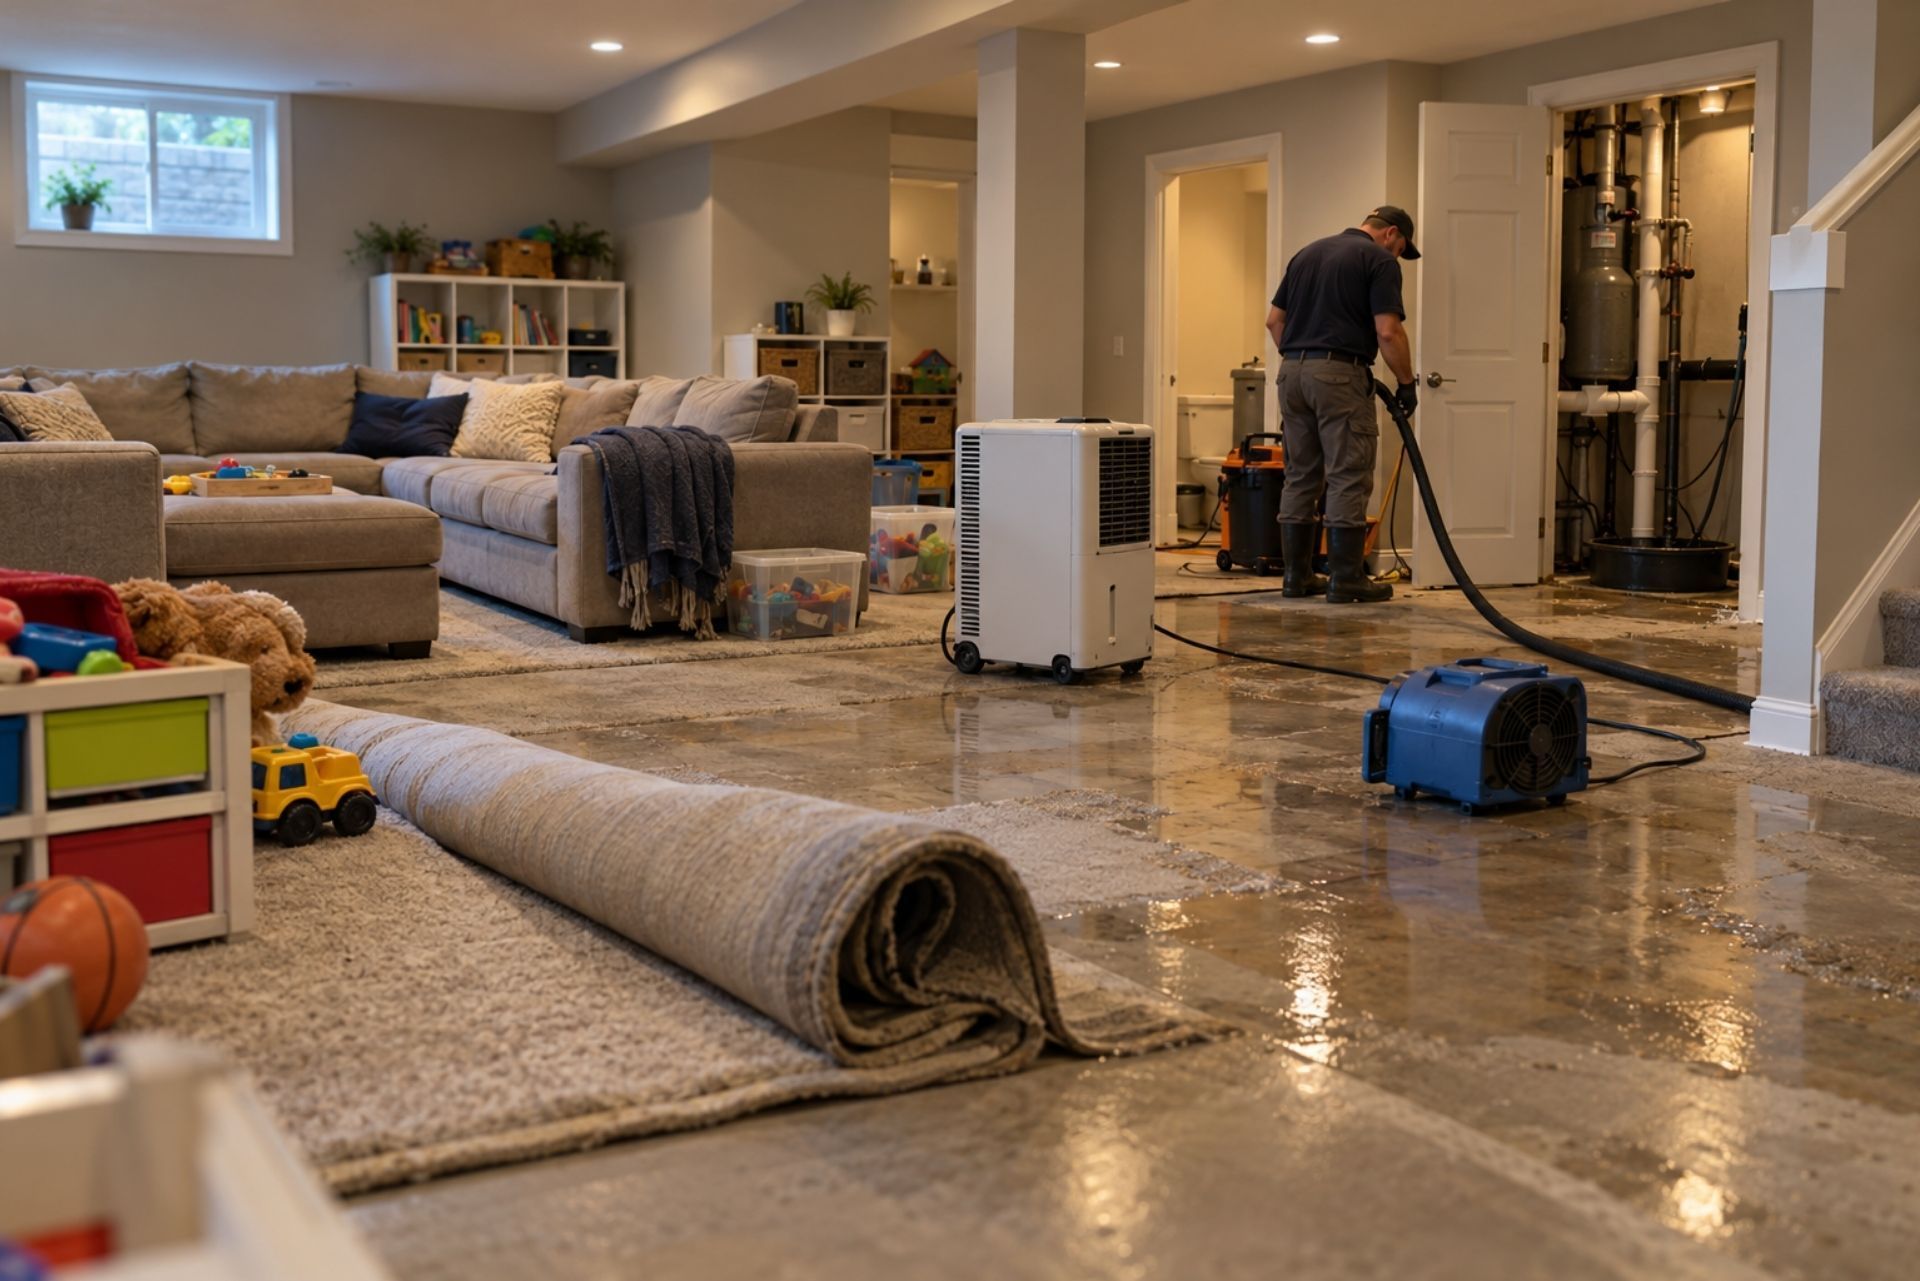
Standard Pennsylvania homeowners policies exclude water that backs up through drains or sewer lines. If you have a finished basement, and many homes in local subdivisions do, you need a separate water backup endorsement.


Here's a typical claim scenario. A heavy summer storm overwhelms the municipal line or your sump pump fails during a power outage. Two inches of water come up through the floor drain. Without the endorsement, the carpet, drywall, sectional sofa and the kids' playroom are on you. With it, the claim is usually straightforward.


The stakes are real because basements add real value. In the 2026 market, a finished basement typically recoups 70% to 75% of its cost at resale, so owners invest in them. The endorsement itself typically costs between $40 and $250 a year in 2026, which is modest compared with replacing a finished lower level.


Keep in mind that water backup is not flood insurance. Surface water rising from outside requires a separate flood policy.

Comparing Water Backup Coverage Limits

Endorsements come in tiers, and the default limit is often too low for a fully finished space. Match the limit to what's actually down there.

Basement Setup Suggested Limit Why
Unfinished, storage only $5,000 to $10,000 Covers cleanup and stored items
Partly finished $10,000 to $25,000 Drywall, flooring, some furniture
Fully finished living space $25,000 to $50,000+ Bathroom, bar, electronics, guest room
Home office or gym below grade $25,000+ Equipment adds up quickly

Also ask whether the endorsement has its own deductible and whether it covers sump pump discharge failure specifically.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Managing Hail and Wind Claims in Cranberry Township

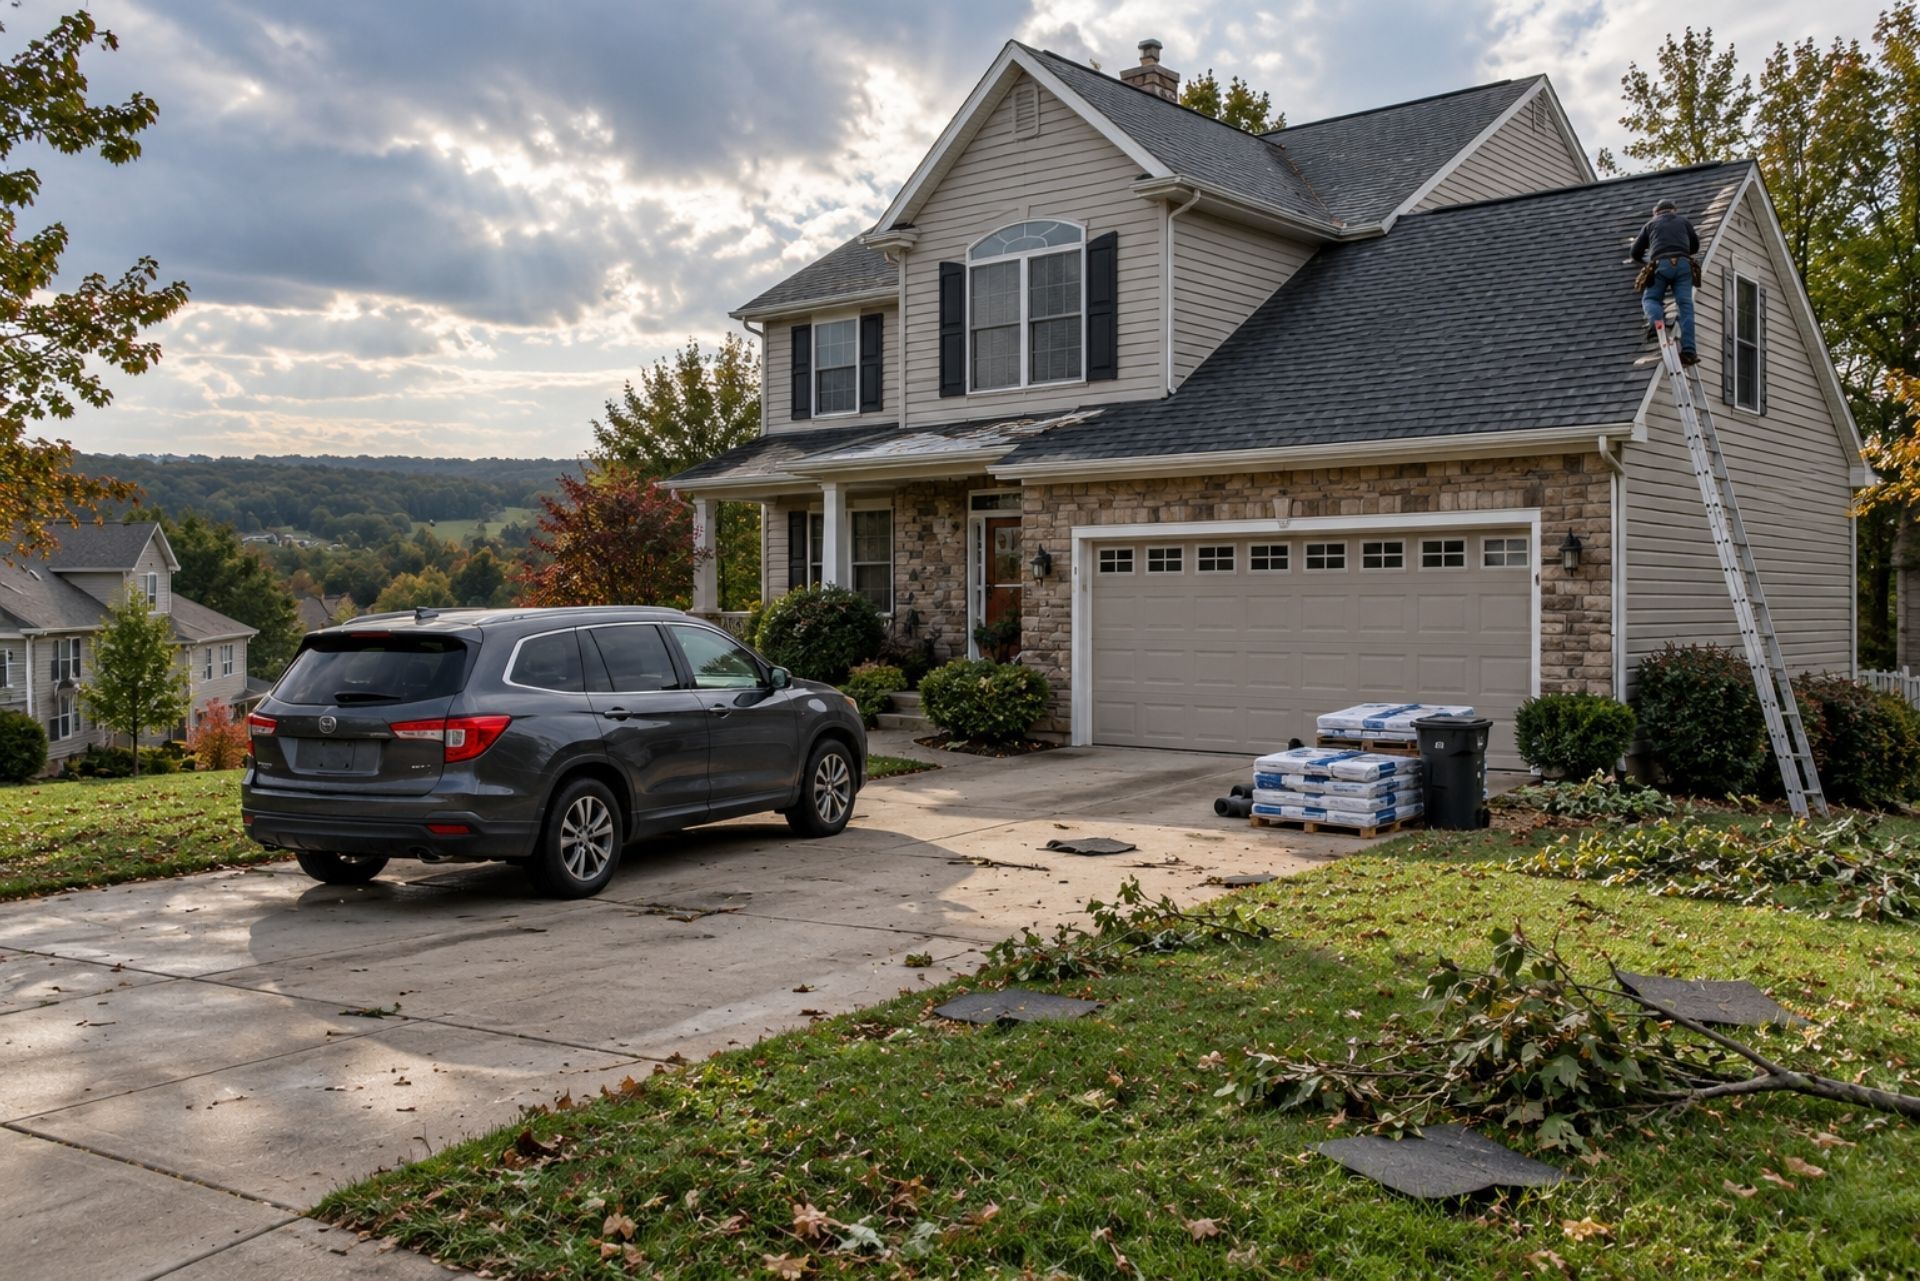
Hail and wind are the most common reasons Cranberry Township homeowners file roof and siding claims. The deductible you choose determines how much of each claim you'll actually pay.


The local weather history explains why. Butler County ranks among the most hail-active regions in Western PA, with 58 verified hail days involving stones 1 inch or larger since 2014. This year has been especially rough: a September 2026 storm produced hail up to 1.5 inches in the Butler area, and Pennsylvania has recorded 50 confirmed tornadoes statewide as of late September.


Newer subdivisions often have similar roofs installed around the same time, so one storm can trigger claims across an entire street. Vinyl siding cracks, gutters dent and shingles lose granules. Some damage is easy to miss from the ground.


Some practical habits help:


  1. Check your policy for a separate wind/hail deductible. Some carriers use a percentage of the dwelling limit, which can be far higher than your standard deductible.
  2. Photograph your roof and siding now, so you have a "before" record.
  3. Ask whether your roof is covered at replacement cost or on a depreciation schedule. Older roofs sometimes get paid at actual cash value.
  4. Pick a deductible you could pay this month without strain.


A higher deductible lowers your premium, but if hail hits every few years, that savings can disappear fast.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Bundling With Car Coverage for Growing Families

For families with two, three or four vehicles in the driveway, combining home and auto usually means a multi-policy credit, one renewal date and one agent who sees the full picture. That last part matters more than most people think.


Commuting on I-79 or the Turnpike adds mileage, and a teen driver can change your auto premium dramatically. Many Pennsylvania families now use telematics programs to offset high teen driver premiums, such as Nationwide's SmartRide and GEICO's DriveEasy. Pairing those programs with a bundle can soften the jump when a 16-year-old gets licensed.


Bundling also helps align your liability limits. If your auto liability is low while your home equity is growing, an umbrella policy may make sense, and many carriers require matching underlying limits.


That said, a bundle isn't automatically the right answer. Sometimes one carrier wins on home while another prices auto far better. As an independent agency, we compare both ways. You can read more about Pennsylvania homeowners coverage or see options for car insurance in Cranberry Township.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Common Questions About Cranberry Township Insurance

How much is homeowners insurance in Cranberry Township PA? Rates depend on your home's rebuild cost, roof age, claims history, credit-based insurance score and deductible. Newer homes with higher replacement values often carry higher premiums, so a personalized quote is the only reliable number.


Does homeowners insurance cover a flooded basement? It depends on the source. Sewer or drain backup needs a water backup endorsement, while surface flooding from outside requires a separate flood policy.


Is water backup the same as flood insurance? No. Water backup covers water coming up through drains or a failed sump pump, and flood insurance covers rising water from outside the home.


Will a hail claim raise my premium? It can, depending on the carrier and your claim history. Weather claims are often treated differently from liability claims, but frequent claims can affect renewal pricing.


Is bundling home and auto worth it for families? Usually, especially with multiple vehicles or a new teen driver. It's still smart to compare bundled and separate pricing, since the numbers don't always favor one carrier.


Should my dwelling limit match my purchase price? No. Your limit should reflect what it costs to rebuild the house, which can be higher or lower than what you paid.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Contact MVP Insurance in Zelienople or New Springfield

The right policy for a Cranberry Township family covers the full rebuild cost of a newer home, protects the finished basement against backup, and uses a deductible that makes sense for a hail-prone county. Pairing it with auto can help keep the whole household's coverage aligned as kids start driving.


Josh Medure and David Varrati founded MVP Insurance in 2008 as an independent agency. That means we work for you and shop multiple carriers rather than pushing one company's product. We're licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


Reach either office:


  • Zelienople, PA: 108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122
  • New Springfield, OH: 13823 Grant St, New Springfield, OH 44443, (330) 707-9055


If your policy hasn't been reviewed since you moved in, or the basement got finished after you bought it, now is a good time to check it. We'll compare carriers for you and flag any gaps before the next storm finds them. Start your quoteand see how your coverage stacks up.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








