


Pennsylvania Electrician Insurance

Owner, MVP Insurance

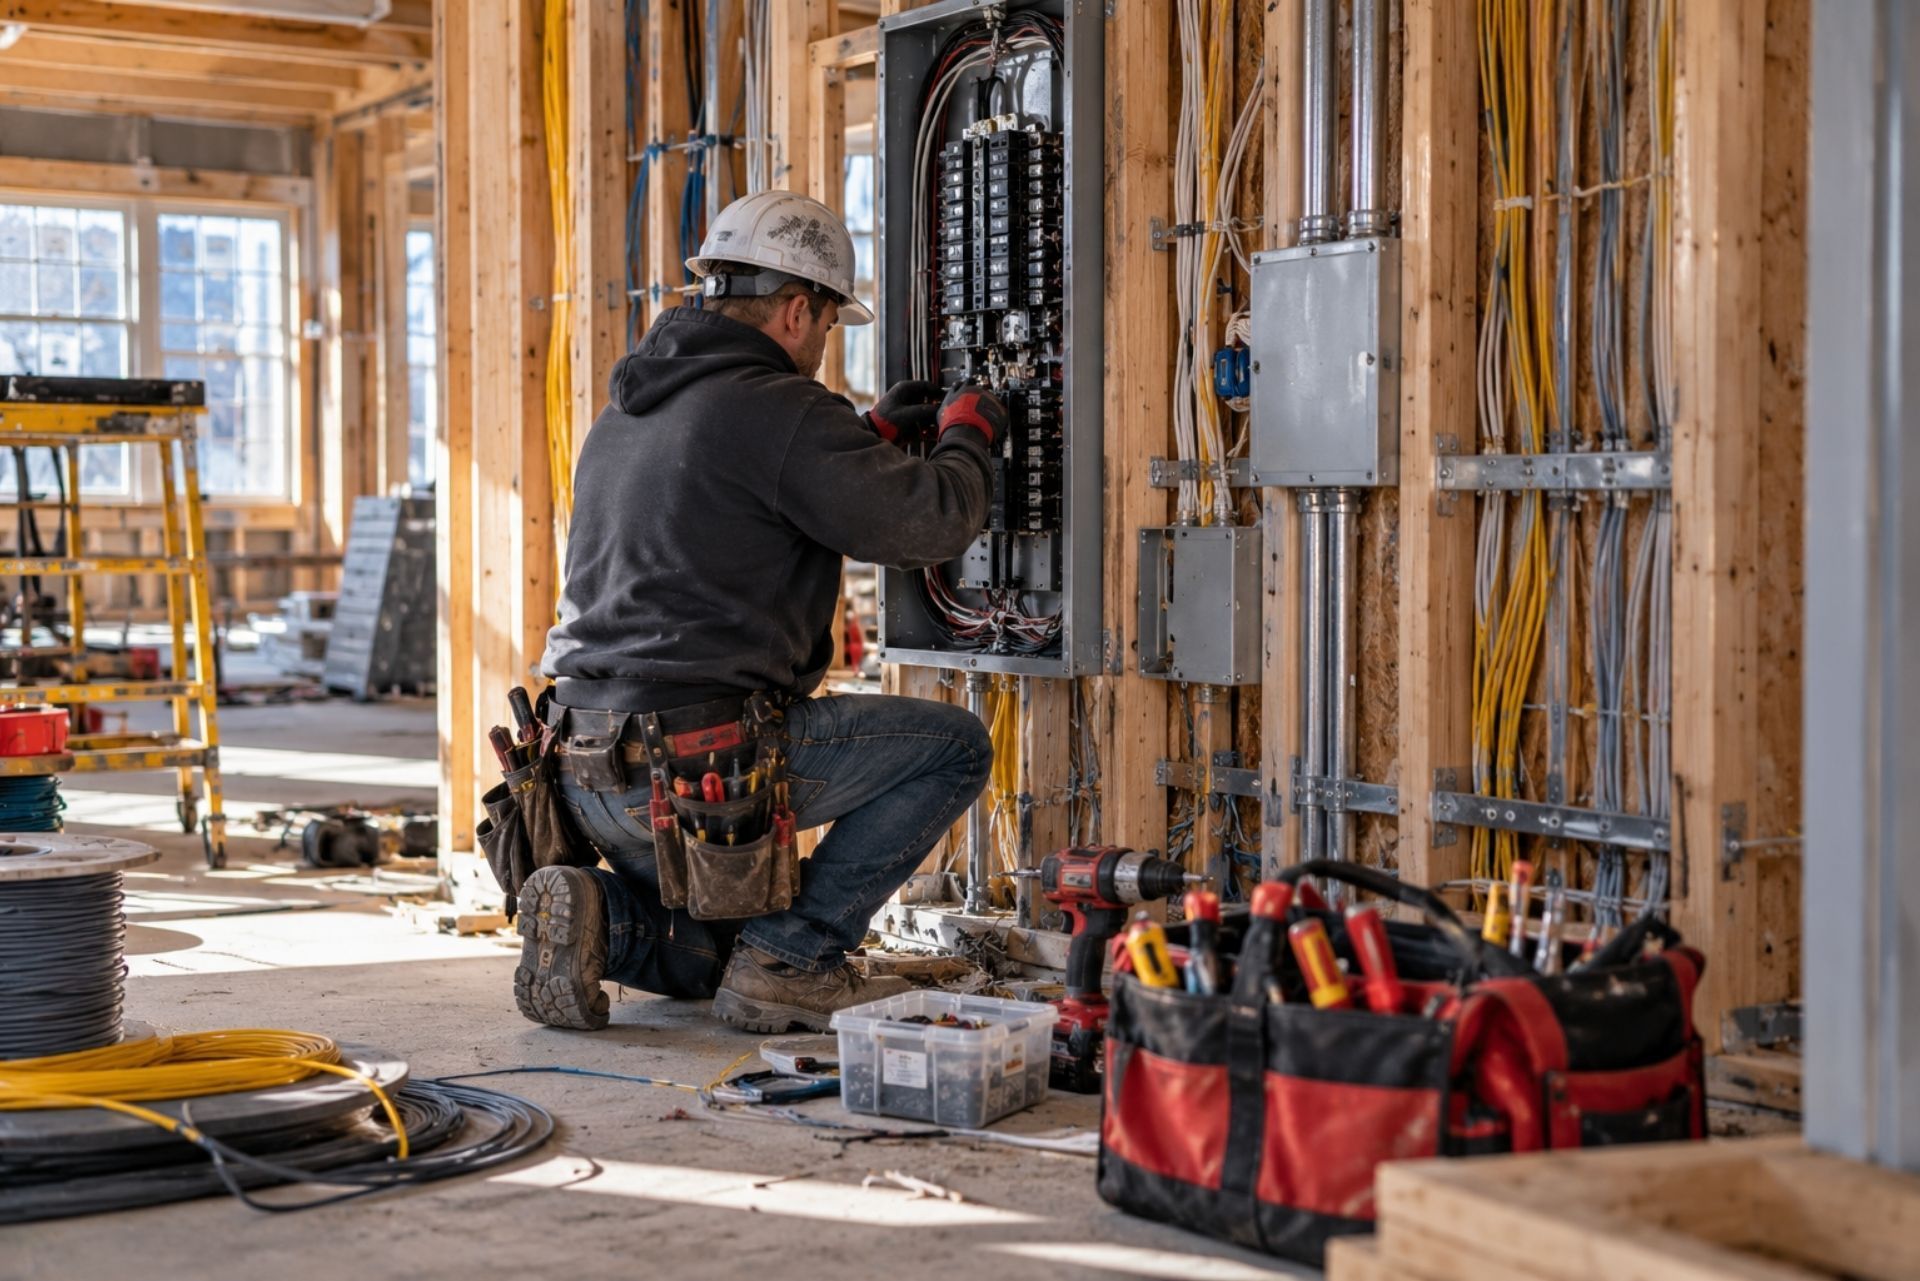
Pennsylvania electrician insurance generally starts with general liability for fire, shock and property damage claims, then adds completed operations, an equipment floater, workers' comp and commercial auto. There is no statewide license. Your local municipality and your contracts usually set the insurance limits you need to carry.


Pennsylvania has had a rough start to 2026. The state led the nation in home fire-related deaths in the first two months of the year, with 26 fatalities. That is more than larger states like Texas and New York recorded over the same period. For electricians, every one of those headlines raises the same question: if a fire traced back to my work, would my policy actually respond?

Essential Pennsylvania Electrician Insurance Coverages

Pennsylvania electrician insurance protects you when your work causes property damage or bodily injury to someone else. The state has no universal licensing requirement, but many local municipalities require specific insurance limits before you can pull permits. Those limits exist mainly to cover fire and electrical shock hazards.


Most electrical contractors in the Commonwealth carry some version of this core package:


  • General liability: Covers third-party injury and property damage, including fire and shock claims.
  • Completed operations: Extends liability protection to work you have already finished.
  • Workers' compensation: Required in Pennsylvania once you have employees. It covers falls, burns and arc flash injuries.
  • Commercial auto: Covers vans and trucks titled to the business.
  • Inland marine or equipment floater: Protects tools and gear that move between job sites.
  • Umbrella: Adds limits on top of liability and auto policies when contracts demand more.


You can see how these pieces fit other trades on our contractors insurance Pennsylvaniapage.

David Varrati

By: Joshua Medure

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Managing Risks of Fire and Shock Claims From Faulty Work

General liability is the policy that pays when faulty wiring or an installation error injures someone or damages property. It typically covers the injured party's medical bills, repairs to the damaged building, and your legal defense, even if the claim turns out to be groundless.


The size of these claims can be startling. Home electrical fires cause an average of $2.4 billion in direct property damage each year, and 15% of them start in kitchens. A loose neutral on a range circuit or an overloaded backstab connection can turn into a six-figure subrogation demand from the homeowner's insurer.


Shock claims work differently but can be just as serious. Picture a tenant shocked by an ungrounded outlet you replaced, or a maintenance worker hurt by a mislabeled panel. Both are bodily injury claims under general liability.


There is a nuance that often surprises contractors. General liability pays for the damage your work causes. It does not usually pay to redo the faulty work itself. That gap catches many electricians off guard, so ask your agent how your policy handles your own work.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Protecting Your Business With Completed Operations Coverage

PCompleted operations coverage protects you after the job is done and you have left the site. That timing matters because many electrical fires start weeks or months after the final inspection. Completed operations is a standard component of general liability that responds to fire or shock claims arising once a project is finished.


A 2026 claim in Baden, PA shows how this plays out. A panel failed six months after installation, and the completed operations trigger covered $22,000 in equipment damage. Without that coverage, the contractor would have paid the full bill out of pocket.


Here are the mistakes that tend to cause trouble:


  • Buying a policy that excludes or sublimits products-completed operations to save on premium
  • Letting coverage lapse after retiring or closing the business, while old installations are still in service
  • Assuming the general contractor's policy covers your finished work


Look at the "products-completed operations aggregate" line on your declarations page. Many electricians aim to have it match their general aggregate limit.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Understanding Municipal Electrical Licensing and Insurance

Pennsylvania does not have a statewide electrician license. Licensing is generally handled locally. As of this writing, Pittsburgh and a number of other municipalities run their own electrician licensing programs, and each one sets its own insurance requirements. If you work in three townships, you might face three sets of rules.


These local programs typically ask for:


  1. A certificate of insurance showing minimum general liability limits
  2. The municipality named as certificate holder, and sometimes as an additional insured
  3. Proof of workers' compensation, or an exemption form if you work solo
  4. Renewal paperwork each year with updated certificates


That may change. As of October 19, 2026, Senate Bill 1260 was re-reported as amended in the House to create a uniform statewide licensure system. The proposed Electrical Services Licensure Act (HB 2619) would require contractors to maintain professional liability insurance to obtain or renew a license. If a policy lapses, the State Board would have to be notified within 30 days, or the license would go inactive. Even before any bill passes, a lapse is a bad idea.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Securing Tools With Equipment Floaters and Inland Marine

PAn equipment floater covers your tools and gear wherever they are: in the van, at the supply house, or on a job site in Erie or Allentown. Standard commercial property policies usually protect items only at your listed business address. That leaves thermal imagers, insulation testers, conduit benders and generators uncovered for most of the workday.


Theft is the biggest concern. Construction sites along the I-76 and I-80 corridors are currently considered high-risk hotspots for organized theft of generators and copper wiring. If thieves clean out a gang box overnight, a floater can replace the contents so you are not stuck waiting before you can bill again.


When you set up a floater, keep these points in mind:


  • Scheduled vs. blanket: List high-value items individually, and use a blanket limit for smaller hand tools.
  • Replacement cost vs. actual cash value: Actual cash value subtracts depreciation, which can sharply reduce payouts on older gear.
  • Unattended vehicle conditions: Some forms require that the vehicle be locked or that you show signs of forced entry.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Meeting Common Contract Insurance Requirements

General contractors and commercial clients ask for certificates of insurance because they do not want your mistake landing on their policy. A typical commercial subcontract will ask for specific limits, additional insured status, a waiver of subrogation and primary/noncontributory wording. If your certificate does not match the contract, you may not be allowed on site, and your first draw can be delayed.


The usual sticking points are endorsements, not limits. A contract may require additional insured status for completed operations as well as ongoing work, and some policies include only the ongoing form. MVP Insurance reviews the insurance section of your contract against your policy before you sign. We issue certificates quickly through our technology-driven service tools and shop multiple carriers when an endorsement is not available on your current policy.

Comparing Electrician Insurance Limits and Options

Coverage Common Limits Who Usually Requires It
General liability $1M per occurrence / $2M aggregate Municipalities, GCs, property managers
Completed operations Often matches general aggregate Commercial contracts
Workers' comp State statutory limits Pennsylvania law, once you hire employees
Commercial auto $1M combined single limit GCs, commercial clients
Umbrella $1M to $5M Larger commercial and municipal jobs
Equipment floater Value of your tools Lenders, your own protection

As a benchmark, the median cost of general liability for a small Pennsylvania electrical firm is about $61 per month, or $732 per year. Your rate will depend on payroll, the type of work you do and your claims history.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Frequently Asked Questions About Pennsylvania Electrician Insurance

Do I need a license to be an electrician in Pennsylvania? There is no statewide license right now. Pittsburgh and many municipalities generally require local licensing, so check with each town where you pull permits.


Does general liability cover my faulty wiring? It covers fire damage and injuries caused by your faulty wiring. It typically does not pay to fix or redo the wiring itself.


What happens if a fire starts after I finish a job? Completed operations coverage, which is part of most general liability policies, responds to claims that arise after you leave the site.


Are my tools covered in my van? Usually not under a standard property policy. An equipment floater covers tools in transit and on job sites.


How much liability insurance do contractors usually ask for? Most contracts ask for $1 million per occurrence and $2 million aggregate. Larger commercial jobs often add an umbrella.


Is workers' comp required if it's just me? Sole proprietors with no employees are generally exempt. Many GCs still want an exemption certificate on file.


Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Partner With MVP Insurance for Professional Contractor Coverage

The electricians who come through claims in good shape usually have the same things in common. They carry completed operations at full limits. They schedule their expensive tools on a floater. And they read the insurance section of a contract before they sign it, not after a GC rejects their certificate. With Pennsylvania's fire numbers and possible statewide licensing on the way, the gaps in a bare-bones policy are getting harder to live with.


MVP Insurance was founded in 2008 by Josh Medure and David Varrati. As a 100% independent agency, we work for you, not for any single carrier. We compare options from carriers such as Erie, Westfield and Liberty Mutual to build contractor coverage that fits how you actually work, and our 24/7 claims service means someone answers when a call comes in at 2 a.m. You can browse the other trades we cover on our industriespage. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263 and NPN 10588293.


If you are bidding on new work or renewing soon, start your quoteand we will do the comparison for you. Stop by our Zelienople office at 108 E Grandview Ave, (724) 453-1122, or our New Springfield office at 13823 Grant St, (330) 707-9055. Your wiring should outlast your policy questions.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

Joshua Medure

Owner, MVP Insurance


I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania







