

Pennsylvania teens move from a learner's permit to a junior license to a senior license. Each step requires a minimum amount of time, practice, or clean driving before the next one unlocks. Here's what each stage actually requires and what it means at home.
CG 20 37: Coverage After the Project is Finished
Can my 16-year-old drive their friends home from school in Pennsylvania? During the first six months of a junior license, they can carry only one passenger under 18 who isn't an immediate family member, unless a parent or guardian is in the car. After that window, the limit eases if your teen has stayed violation-free.
Does a teen with a learner's permit need to be on my car insurance? It depends on the carrier. Some require permit holders to be listed, and others don't rate them until they're licensed. Tell your agent when the permit is issued so there's no gap if something happens.
Can a junior license holder drive home from work after 11 PM? Yes. Pennsylvania's curfew includes an exception for travel to and from employment. Your teen should keep proof of their work schedule in the car in case they're stopped.
Pennsylvania's licensing rules work because they ease teens into risk instead of handing them full privileges on day one. Supervised hours, passenger caps, and the overnight curfew all target the situations where new drivers get hurt most. For families, those same rules shape the insurance conversation. A clean junior year, solid liability limits, and the right car assignment can keep your teen safer and your premium more manageable.
If your teen's road test is coming up, now is a good moment to see how different carriers would price your household. MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH. We compare policies across multiple carriers so you don't have to. When you're ready, you can start your quote here, and we'll walk you through the options. MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
Pennsylvania still offers homeowners insurance below the national average, but recent increases have been steep, and Western PA homeowners have felt it through storms and rising rebuilding costs. Your location sets the starting point. Your deductible, your roof and home systems, and how you use your policy decide much of the rest.
The most useful step is seeing real numbers side by side instead of accepting a single renewal at face value. MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH, and the team compares multiple carriers so you don't have to. When you're ready, start your quote here and get a clearer picture of what your home should cost to insure.
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
Pennsylvania follows modified comparative negligence. You can recover damages from other drivers as long as your share of fault isn't greater than theirs combined. Your recovery is reduced by your own percentage. If you're found 30% at fault for a $10,000 loss, you'd typically recover $7,000 from the other side. Once you cross 50%, you can't recover from them at all.
Icy-road claims are full of split percentages. Say one driver was following too closely and another changed lanes abruptly on packed snow. Fault might land at 60/40 or 70/30. In a pileup, three or four drivers might each carry a slice. These percentages shape your claim history too, which is why it's worth disputing a split you think is wrong before it becomes final.
Common Questions About Ohio BWC True-Up
These two get confused all the time, and they pay for different situations.
- Emergency roadside service (sometimes called towing and labor) covers breakdowns: dead batteries on a zero-degree morning, flat tires, lockouts, or a winch-out when you've slid into a snowbank without damaging the car. It typically has a per-incident limit and is a low-cost add-on.
- Collision towing is part of your collision claim. When your car is damaged in a crash, the tow to a shop and reasonable storage are usually paid as part of the loss, subject to your deductible.
- Comprehensive can cover towing tied to non-collision losses, such as a tree limb crushing your hood during an ice storm.
A common mistake is assuming roadside service covers a crash tow, or that collision covers a simple winch-out. Check which one applies before you call, especially if you belong to an auto club as well.
Common Questions About Ohio Deer Accident Claims
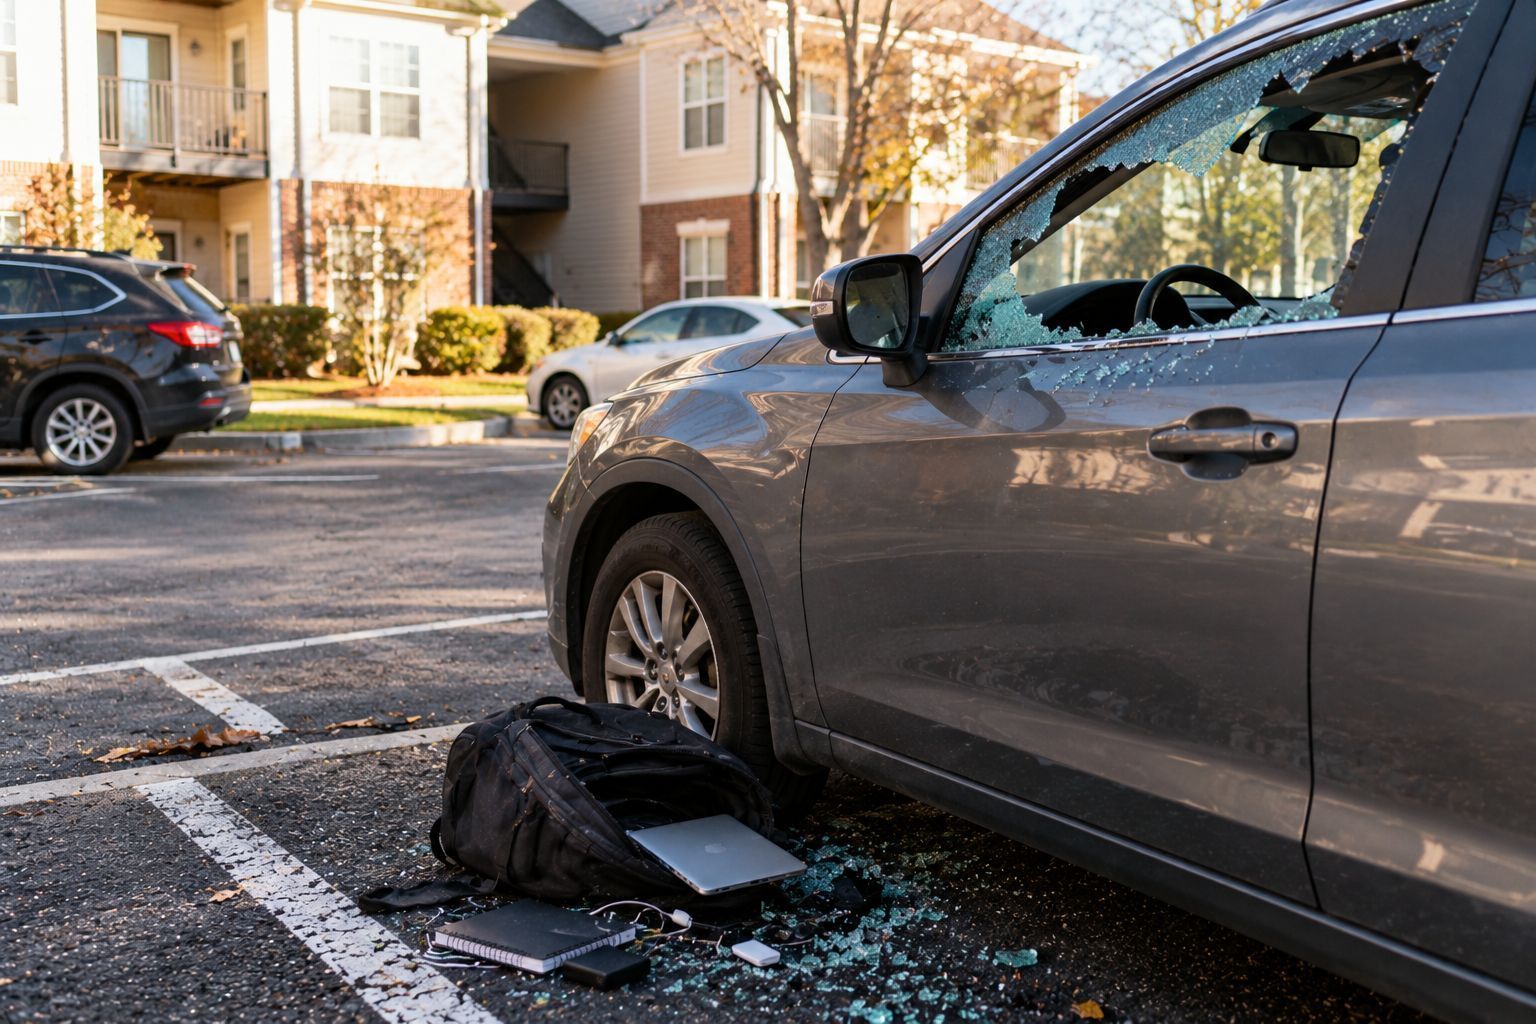
Yes. Ohio renters insurance typically covers personal belongings stolen from your car, such as a laptop, gym bag, or tools, through its off-premises personal property coverage. Your deductible applies, and payouts may be capped below your full limit. Auto insurance handles damage to the car itself, like a broken window, but not the stuff that was inside.
That split catches many Ohio drivers off guard. Someone smashes a window in a Columbus parking garage, grabs a backpack, and suddenly there are two policies, two deductibles, and two claims to think about. Car break-ins are still a real concern here: even though U.S. vehicle thefts fell by 21% in the first half of 2026, Ohio ranked 6th nationally for thefts the year before. Knowing which policy pays for what before it happens saves you a frustrating week of phone calls.
Does Renters Insurance Cover Theft From a Car in Ohio?
Yes, in most cases. A standard renters policy protects your belongings against theft even when they aren't inside your apartment. That includes items locked in your trunk, sitting on the back seat, or tucked under a floor mat. It doesn't matter whether the car was parked in your apartment lot, at a Cleveland Browns tailgate, or outside a grocery store in Youngstown.
This protection comes from the off-premises provision. The Insurance Information Institute explains that standard renters insurance protects belongings against theft even when they are not inside the rental unit. Your policy follows your stuff, not your address.
Here's what usually qualifies:
- Laptops, tablets, and headphones
- Clothing, shoes, and bags
- Sports equipment like golf clubs or bikes stored inside the vehicle
- Textbooks, work tools you personally own, and sunglasses
What it won't cover is the car itself, or anything permanently attached to it. A stolen catalytic converter, factory stereo, or the car as a whole falls under your auto policy, not your renters policy. One common mistake: assuming an aftermarket dash cam or speaker system counts as personal property. If it's wired in, it's usually treated as part of the vehicle.
How Off-Premises Personal Property Coverage Protects Your Belongings
Off-premises coverage generally applies anywhere in the world, but often at a reduced limit. So your belongings are protected in a car in Akron, a hotel in Florida, or a rental car overseas. The catch is how much the policy will pay when the theft happens away from home.
Many policies cap off-premises claims below your main personal property limit. A common structure is 10% of the total personal property limit or $1,000, whichever is greater. If you carry $30,000 in personal property coverage, that could mean only $3,000 available for items stolen from your car. Some policies don't reduce off-premises coverage at all, which is why the declarations page and policy wording matter more than the policy's marketing name.
Valuation is the other piece. Many Ohio policies default to Actual Cash Value, which subtracts depreciation. A three-year-old laptop that cost $1,400 might be valued at a few hundred dollars. Replacement Cost Value pays what it costs to buy a comparable new item, and as of this writing, upgrading typically adds only about 10% to 15% to the annual premium. With average Ohio renters premiums running roughly $165 to $215 per year, that upgrade is often a small line item. If you want to see how these options fit together, our page on ohio renters insurance walks through the basics. (Link: ohio renters insurance)
Common Limits and Sub-limits for High-Value Items
Even within the off-premises limit, certain categories carry their own caps. These special sub-limits apply no matter where the theft happens, and they're where people get surprised.
Typical categories with sub-limits include:
- Jewelry and watches: often capped at a low fixed amount for theft
- Firearms: frequently limited, which matters for hunters driving to a lease
- Cash and gift cards: usually a few hundred dollars at most
- Business property: equipment used for side work may be limited or excluded
If you regularly carry a camera kit, an engagement ring, or tools for a side business in your car, ask about scheduling those items separately. Scheduled items often have no deductible and broader protection.
Understanding Deductibles and Claim Payouts
Your renters deductible comes off the top of every theft claim, which can make small claims barely worth filing. The deductible is the amount you pay before insurance contributes anything, and it applies per claim.
Here's a straightforward example. Someone breaks into your car and takes a laptop worth $1,000. Your renters deductible is $500. The insurer pays $500, and you absorb the other $500. If that laptop is valued on an Actual Cash Value basis and has depreciated to $700, the payout drops to $200.
Before filing, run the numbers honestly. A $600 claim with a $500 deductible nets you $100, and claims history can follow you when you shop for coverage later. On the other hand, if thieves took a laptop, a backpack, a winter coat, and a pair of prescription glasses, the total can climb past $2,000 fast, and the claim makes clear sense.
Deductibles are getting more regulatory attention, too. A nationwide data call launched in March 2026 is
collecting granular data on Ohio deductibles and claims by peril to study how accessible coverage really is. For renters, the practical takeaway is simple: choose a deductible you could pay tomorrow without stress.
What Auto Insurance Pays vs. Renters Insurance
Auto insurance pays for physical damage to your vehicle, never for the personal items inside it. If a thief smashes your window and pries open the glove box, comprehensive coverage handles the glass and the damaged trim. The stolen sunglasses, wallet, and laptop go to your renters policy.
Ohio draws a clear line here. Auto insurance covers permanent vehicle parts, while renters insurance covers unattached property like laptops. Liability-only auto policies won't pay for the window at all, since comprehensive is optional coverage. Plenty of drivers with older cars drop comprehensive to save money and only realize the gap after a break-in.
Carriers such as Erie, Westfield, and Progressive write these as separate policies, each with its own deductible. That means one break-in can trigger two deductibles. Some carriers offer glass coverage with a low or zero deductible on the auto side, which softens the blow.
Comparing Coverage Responsibilities
| What was damaged or stolen | Which policy pays | Deductible |
|---|---|---|
| Smashed window | Auto (comprehensive) | Auto deductible |
| Laptop, phone, bags | Renters | Renters deductible |
| Factory stereo or catalytic converter | Auto (comprehensive) | Auto deductible |
| Clothing and personal items | Renters | Renters deductible |
| The car itself | Auto (comprehensive) | Auto deductible |
Frequently Asked Questions About Vehicle Theft in Ohio
Does my car insurance cover my stolen phone? No. Car insurance only covers the vehicle and its permanently attached parts. Your phone falls under renters insurance, or a separate device protection plan if you have one.
Do I need to file a police report for a renters insurance claim? In practice, yes. Most insurers expect a police report for any theft claim, and having the report number ready speeds things up considerably.
Does renters insurance cover theft if the car was unlocked? Usually, yes, since standard policies generally don't require signs of forced entry for personal property theft. Some policies do include wording about it, so the language in yours determines the answer.
A car break-in in Ohio usually means two policies working side by side: renters for your belongings, auto for the vehicle. Off-premises limits, item sub-limits, and your deductibles decide how much actually comes back to you, so it pays to know those numbers before anything happens. Replacement cost coverage and scheduled items close the most common gaps for very little added premium.
MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH, and we compare renters and auto options from multiple carriers so the pieces fit together. If you'd like a second look at how your coverage lines up, you can start your quote here. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
Search
Recent Posts



MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.