

The practical takeaway: a furnished lake house you use every summer probably belongs in the middle column. An inherited house waiting on probate, with the furniture gone, fits the right column. Putting either one in the left column is how coverage gaps happen.
The Ohio Valley sits in a corridor where warm, humid air from the south meets colder systems from the west. The result is a steady run of thunderstorms, straight-line winds, hail, and heavy downpours that overwhelm older storm drains. For homeowners, that translates into very specific claims: shingles peeled off in a wind event, siding dented by hail, trees through the roof, and basements flooded by sewer backup.
Sewer backup is a gap we see catch people off guard constantly. A standard policy usually excludes water that backs up through drains unless you've added a specific endorsement, and in a hillside neighborhood with aging municipal lines, one heavy storm can leave several inches of water in a finished basement. Carriers have watched these losses pile up across the region and priced accordingly.
Misclassification is the most common expensive mistake we see. A business gets lumped into one high-rated code, even though half the staff works in an office. Pennsylvania generally rates a business by its governing classification, but separate codes can apply when operations meet the PCRB's rules for division.
Take a small HVAC company where the owner's spouse handles billing full time. That clerical payroll may qualify for a far lower code than the field technicians' code. Review the classification page of your policy every year. If the description doesn't match what your people actually do, ask questions before the audit.
Your experience modifier compares your claims history to that of similar businesses. A 1.00 mod is average. A 0.85 mod cuts your premium by 15%, and a 1.25 mod raises it by 25%. Mods generally use three years of claims, excluding the most recent year, so today's injury affects your bill for years.
Frequency hurts more than severity. Five small medical-only claims often damage a mod more than one larger claim. Pennsylvania offers medical-only claim handling, but small injuries still need to be reported properly, so check how claims are counted before you decide how to handle minor incidents.
Frequently Asked Questions About PA Workers Comp Costs
Social Inflation and Legal Trends in the Commonwealth
Payroll" for workers comp means more than base wages. It generally includes overtime pay (with the premium portion often excluded), bonuses, commissions, holiday and vacation pay, and certain other compensation. Business owners often miscount this, and the error shows up at audit.
Corporate officers follow special rules. For policies effective April 1, 2026, officer payroll ranges from $70,044 to $280,800 per year for rating purposes. An officer who pays themselves very little still gets rated at the minimum, and high earners get capped at the maximum. That ceiling rose sharply this year, so owners who pay themselves well may see more of their salary counted than they did in past years.
Have this ready before the auditor calls:
- Certificates of insurance for every sub, with workers comp coverage dates that match the dates they worked for you
- Written contracts for each independent contractor, signed before work began
- 1099 list and payment totals that tie back to your general ledger
- Payroll records broken out by class code, including overtime
- Exemption documentation for any sole proprietor or partner claiming they're not required to carry coverage
Get the COIs directly from the sub's agent when you can. A certificate emailed by the sub themselves is easier to doctor or let lapse without notice.
Successful Pennsylvania winterization comes down to matching the house, the plumbing and the policy. Choose heat or drain (or both), keep a real inspection log, file your Act 29 information if it applies, and make sure your policy reflects how the home is actually used. The owners who struggle after a loss are rarely the ones who skipped a step on the checklist. They are the ones whose coverage never fit the property in the first place.
If you are not sure your current policy holds up through a long empty winter, now is the time to find out, before the first hard freeze. MVP Insurance, with offices in Zelienople, PA and New Springfield, OH, can compare seasonal and vacant home options across multiple carriers for you. Start your quote and get answers before you lock the door for the season.
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
Two lines in that table cause the most trouble. Hired and non-owned coverage gets skipped by businesses that "don't have company vehicles," then an office manager rear-ends someone on a bank run and the claim lands on the business. Uninsured motorist coverage gets rejected to save a few dollars, then a driver gets hit by someone with no insurance and the business has nothing to pay medical costs beyond basic benefits.
Deer deserve their own mention in Pennsylvania. Comprehensive claims from deer strikes run heavy in the fall, which is exactly when many renewals arrive. Dropping comprehensive on an older truck can make sense, but do the math on what a deer collision would cost you first.
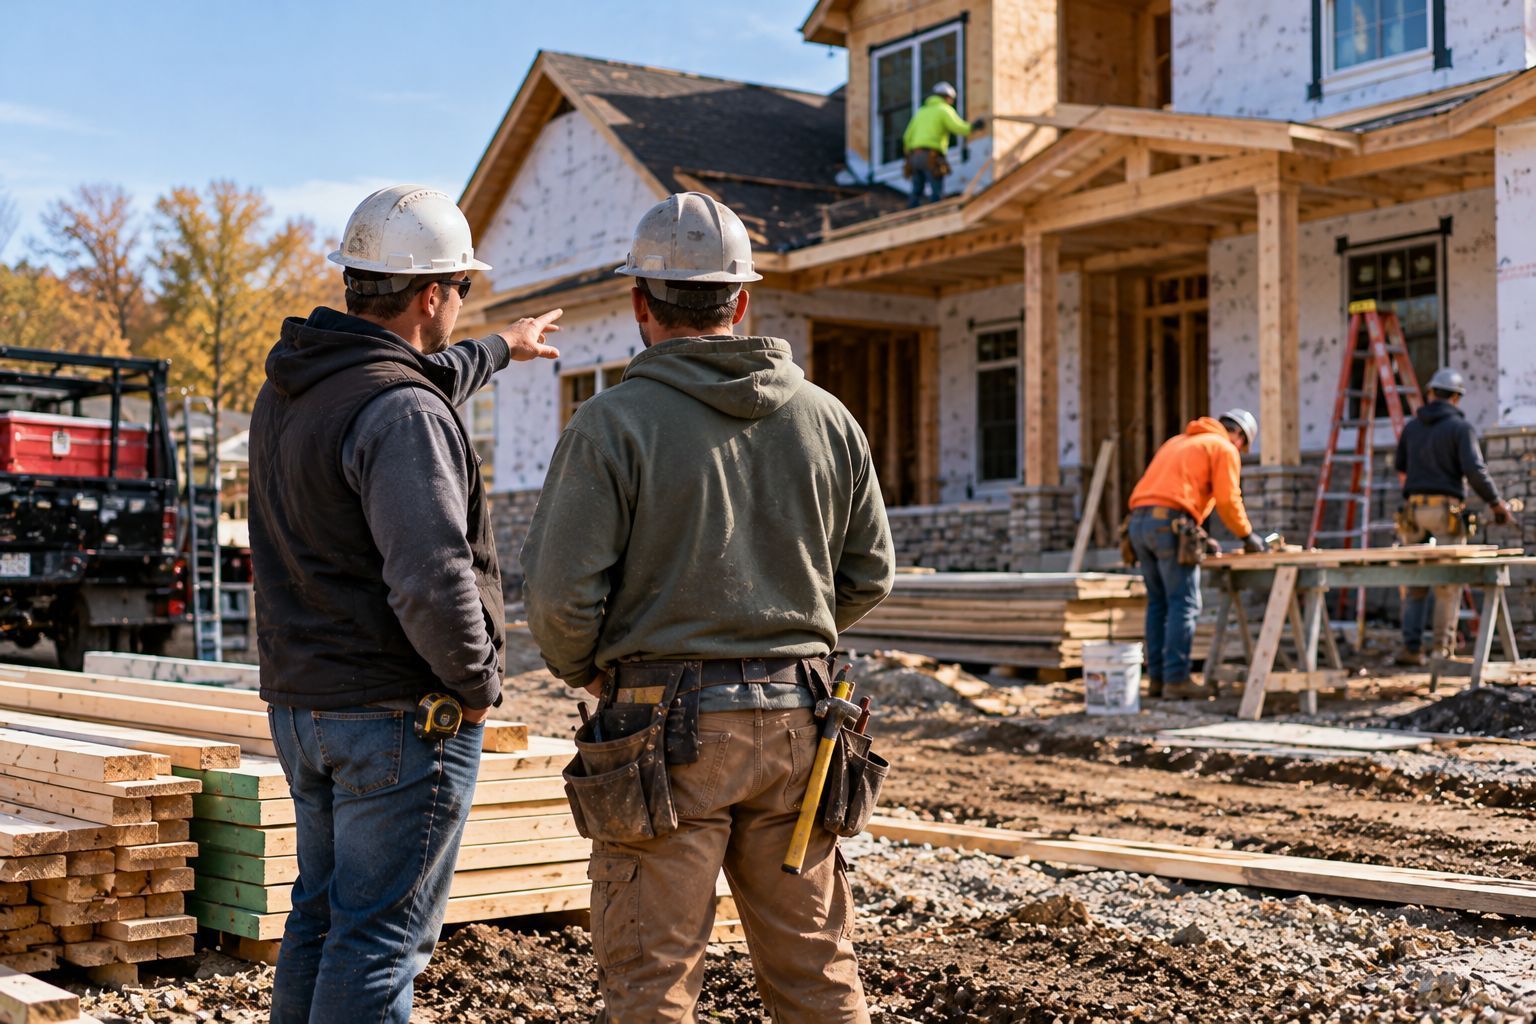
Ohio general contractors get burned in the same way over and over: a sub shows up with a good price, nobody asks for paperwork, and months later an injury claim or a surprise audit bill arrives. Collecting two documents before work begins prevents most of that trouble.
The Importance of Hiring Subcontractors in Ohio with Proper Documentation
When you hire subcontractors in Ohio, collect two documents before work begins: a current Ohio BWC certificate and a certificate of liability insurance. The BWC certificate shows the sub's workers are covered by the state fund. The liability certificate shows their own policy will pay for damage they cause. Without both, the bills for injuries, property damage, and audit charges can land on you.
Most contractors think about subs as a labor decision. Your insurance carrier and the state see it as a risk transfer. Every sub who arrives with proper paperwork takes responsibility for their own crew and their own mistakes. Every sub who arrives without it passes that responsibility back to you, whether you agreed to take it or not.
This affects a wide range of businesses. Roofers hire framers, remodelers bring in electricians and plumbers, and landscapers sometimes pay a buddy with a truck to haul debris for a week. Each of those arrangements creates the same question at audit time: did this person carry their own coverage, and can you prove it?
Your own coverage matters here too. Your general liability policy is priced on assumptions about how much work you do yourself and how much you hand off to insured subs. If those assumptions break down, your rate changes. If you're still putting your own protection together, our page on ohio general liability insurance explains how contractors' policies are typically built and rated.
The rest of this guide covers why each document matters, what to look for on them, and what happens financially and legally when a sub has no coverage.
Why You Need Their BWC Certificate
The BWC certificate is the only proof that a sub's workers are covered for on-the-job injuries in Ohio. If that coverage doesn't exist, the law can treat the sub's employees as your employees.
Ohio is one of the few monopolistic workers' compensation states. Instead of buying workers' comp from a private carrier, all amenable employers must pay into the State Insurance Fund run by the Ohio Bureau of Workers' Compensation, and private insurance cannot replace it. Contractors who move here from other states sometimes get this wrong. A sub may hand you a private workers' comp certificate from an out-of-state carrier, and for Ohio work it does not take the place of BWC coverage.
The penalty for overlooking this is serious. Under Ohio Revised Code 4123.01, if a subcontractor fails to pay BWC premiums, their workers are considered employees of the general contractor. If one of the sub's laborers falls off a ladder on your job, that claim can follow you. You didn't hire that laborer and may never have met them, but the statute doesn't care.
Ohio also uses a 20-factor test under ORC 4123.01(A)(1)(c) to decide whether a construction worker is a real independent contractor or a statutory employee. Factors include who controls the work, who supplies tools, how payment works, and whether the worker can profit or lose money on the job. A one-person "sub" who shows up when you tell them, uses your equipment, and gets paid by the hour can look a lot like an employee, whatever your paperwork calls them. You can read the full statutory definitions in ORC 4123.01 for the exact wording.
The status of the certificate matters as much as its existence. Ohio's BWC programs reward employers who stay current. For example, a $1 billion dividend proposed in August 2026 typically requires "non-lapsed" status to qualify. For you, a lapsed BWC policy is a warning sign. A sub who can't keep their state coverage active may be cutting corners in other places too.
The Role of General Liability Certificates in Ohio
A certificate of liability insurance shows the sub has coverage for bodily injury and property damage they cause. When something goes wrong, the claim stays on their policy instead of yours.
Picture a typical case. Your plumbing sub loosens a fitting in a finished basement, and it lets go on a Saturday night. The homeowner wakes up to two inches of water, ruined drywall, and a soaked sectional. If the plumber carries active general liability coverage, their carrier handles the claim. If not, the homeowner's carrier will probably come after you as the GC, and your own policy takes the loss. That claim stays on your loss history and affects your renewal pricing for years.
The certificate (usually an ACORD 25 form) lists the insured's name, the carrier, the policy number, effective and expiration dates, and limits for each coverage. It provides information only. It doesn't change the policy, which is why the details on it need a careful read.
Verifying Policy Limits and Carrier Ratings
Start with the named insured. It should match the business you're paying exactly. If the certificate says "Smith Contracting LLC" and your checks go to "Mike Smith," that gap could cause problems at claim time.
Next, look at the limits. Many contracts ask for $1 million per occurrence and $2 million aggregate, but your own contract with the property owner may set the minimum, so match your subs to it. Residential builders should know that the Home Construction Service Suppliers Act requires at least $250,000 in liability insurance. That figure is a legal floor, though, and a minimum limit can run out quickly on a serious water or fire loss.
Then check the dates. A certificate that expires in three weeks on a four-month job needs a calendar reminder. Ask to be named as an additional insured where your contract requires it, and make sure that wording appears on the certificate. A sub's agent can usually send an updated certificate the same day.
Common Ohio Carriers for Subcontractors
Ohio subs usually buy their business coverage from regional and national carriers that know the trades well. Erie, Westfield, Progressive, and Western Reserve show up often on certificates in Ohio, covering general liability, commercial auto, and package policies for small contractors. Seeing a well-known name on the form is reassuring, but the limits, dates, and named insured still need a close look.
What Happens When a Sub Is Uninsured
When a sub has no coverage, your insurance carrier will likely charge you extra premium at your annual audit as though that sub were your employee. You may also be responsible for their mistakes, from property damage to injuries to third parties.
Contractors often expect the risk to come from a dramatic accident. In practice, the audit is where most of them get hurt financially, because it happens every year whether or not anything goes wrong on a job.
Financial Consequences of the Insurance Audit
Most contractor general liability policies are rated partly on payroll and partly on payments to subcontractors. At the start of the policy term you estimate those numbers. After the term ends, an auditor reviews your books: 1099s, check registers, job costs.
Payments to subs who provided valid certificates usually fall into a low-rated "insured subcontractor" category, or are excluded. Payments to subs without proof of coverage get moved into a rated class, often charged as if those dollars were your own payroll. Say you paid an uninsured drywall crew $60,000 last year. The auditor can add that $60,000 to your exposure base, and the resulting bill arrives months after the work is finished and the money is spent.
The certificate you didn't collect in March can turn into an invoice in the following spring. Asking for it after the fact rarely helps. If the sub had no policy during the job, there's nothing to produce.
On the workers' comp side, Ohio's construction rules add another factor. For the policy year beginning July 1, 2026, the weekly construction payroll limitation is set at $1,922 per week as of this writing. That cap limits how much of a construction worker's weekly wage counts toward premium, but if an uninsured sub's crew gets treated as yours, their wages still count toward your BWC reporting. BWC rates have been falling, with private employers receiving a 1% average rate cut effective July 1, 2026, but a rate cut doesn't help much if your reportable payroll grows because of someone else's crew.
Legal and Safety Risks of Uninsured Subs
Liability problems hit harder than audit bills. If an uninsured sub's worker gets hurt, ORC 4123.01 can make that worker your statutory employee for workers' comp purposes. If the sub damages a neighbor's car with a dumpster, cracks a client's foundation, or starts a fire with a torch, the injured party will look for the business with insurance, and that's you.
There's also a safety pattern that many experienced contractors recognize. Subs who skip insurance are often the same ones who skip fall protection, permits, or proper equipment. The missing certificate signals a business that is running on thin margins and taking shortcuts.
Comparison of Subcontractor Coverage Requirements
Each of these three coverages does a different job, and only one is required by Ohio law for subs with employees. The table below summarizes them.
| Coverage | Purpose | Typical Limits | Ohio State Requirement |
|---|---|---|---|
| BWC (Workers' Comp) | Pays medical bills and lost wages for the sub's injured workers | Set by state statute, no limit selection | Required for amenable employers through the State Insurance Fund |
| General Liability | Pays for bodily injury or property damage the sub causes to others | Commonly $1M per occurrence / $2M aggregate | Not universally required; residential builders need $250K minimum under HCSSA; contracts often require more |
| Umbrella / Excess | Adds limits on top of general liability and auto | Often $1M to $5M | Not required by the state; driven by contracts and job size |
Here's how to read it. BWC is non-negotiable for any sub with employees, because Ohio law makes the state fund the only option. General liability is where your contracts come in. Your agreement with the property owner usually requires certain limits from you, and you should pass those requirements down to your subs in writing.
Umbrella coverage matters more as job values grow. A commercial client, a school district, or a large property manager may require excess limits from everyone on site. On small residential remodels you might not require an umbrella from every sub. For trades with high severity potential (roofers, electricians, anyone using open flame), it's still a reasonable request.
Sole proprietors fall into a gray area. A one-person operation with no employees may not be required to carry BWC coverage for themselves, though they can choose to buy it. They still need general liability if you want their mistakes covered by their own policy. The 20-factor test discussed earlier also applies: calling someone a sole proprietor doesn't settle the question if the working relationship looks like employment.
Managing Subcontractor Paperwork Effectively
The simplest system is to collect every certificate before a sub starts work, store it where you can find it in under a minute, and track expiration dates so nothing lapses during a job. That one habit eliminates most audit surprises.
Here's a process that works for small and mid-sized Ohio contractors:
- Make certificates a condition of the first payment. Put it in your subcontract: no BWC certificate and no COI means no check. Subs take paperwork seriously when it's tied to getting paid.
- Request certificates directly from the sub's agent. A certificate emailed from the agency is harder to alter than a PDF the sub forwards. Ask the agent to list you as certificate holder and as additional insured if your contract requires it.
- Check the basics on arrival. Named insured, policy dates, limits, and coverage types should match your contract. For BWC, make sure the policy is active and not lapsed.
- Store everything in one place. Use a shared folder organized by sub name, with the expiration date in the file name. A spreadsheet with columns for each policy's expiration date works fine as well.
- Set renewal reminders 30 days out. Request updated certificates before the old ones expire, not after.
- Keep certificates for past years. Your auditor will ask about last year's subs, not just this year's. Hold onto old certificates for at least as long as your audit and claims history might reach back.
The most common mistake is collecting a certificate once, when you first work with a sub, and never updating it. Three years later that same framer is still on your jobs, and the certificate on file expired two renewals ago. At audit, an expired certificate is often treated the same as no certificate.
Another pattern deserves attention: the occasional helper. The guy who hauls debris for two weeks in October or the cousin who helps with a deck build on weekends still shows up as payments on your books. Auditors find those payments. Either get paperwork from these people too, or understand that the money you pay them will probably be rated.
Using an agency that helps track this can save time. An independent agent who handles your policy can tell you which classification issues your carrier tends to flag at audit and help you prepare before the auditor contacts you.
Frequently Asked Questions About Ohio Subcontractors
Do I need a BWC certificate if the sub is a sole proprietor? If the sole proprietor truly has no employees, they may not be required to carry BWC coverage for themselves. Get it in writing anyway, along with their liability certificate, because Ohio's 20-factor test can still treat them as your employee if the working relationship looks like employment.
What happens if a sub's insurance expires mid-project? Any work done after the expiration date may be treated as uninsured, both for claims and at your audit. Stop payments until you receive an updated certificate, and set reminders so you catch renewals before the expiration date.
Can I charge a sub for the insurance cost if they are uninsured? Yes, many contractors write a clause into their subcontracts allowing them to deduct an insurance charge from an uninsured sub's payments to offset the audit cost. It only works if the clause is in a signed agreement before the work begins, so build it into your standard subcontract now.
Two documents protect you on every subcontracted job in Ohio: the BWC certificate covers the sub's workers through the state fund, and the liability certificate keeps their mistakes on their own policy. Skip either one and you take on their risk, often without knowing until an audit bill or a claim notice arrives. Collecting paperwork before the first payment, storing it carefully, and tracking renewals is not complicated work, and it pays off every year at audit.
Your own coverage should match the way you actually run jobs, including how much work goes to subs. MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH, and works with carriers such as Erie, Westfield, and Western Reserve as an agent, comparing options on your behalf. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. When you're ready to review your contractor coverage, start your quote here and we'll handle the comparison for you.
Search
Recent Posts



MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.