

The Ohio Valley sits in a corridor where warm, humid air from the south meets colder systems from the west. The result is a steady run of thunderstorms, straight-line winds, hail, and heavy downpours that overwhelm older storm drains. For homeowners, that translates into very specific claims: shingles peeled off in a wind event, siding dented by hail, trees through the roof, and basements flooded by sewer backup.
Sewer backup is a gap we see catch people off guard constantly. A standard policy usually excludes water that backs up through drains unless you've added a specific endorsement, and in a hillside neighborhood with aging municipal lines, one heavy storm can leave several inches of water in a finished basement. Carriers have watched these losses pile up across the region and priced accordingly.
Misclassification is the most common expensive mistake we see. A business gets lumped into one high-rated code, even though half the staff works in an office. Pennsylvania generally rates a business by its governing classification, but separate codes can apply when operations meet the PCRB's rules for division.
Take a small HVAC company where the owner's spouse handles billing full time. That clerical payroll may qualify for a far lower code than the field technicians' code. Review the classification page of your policy every year. If the description doesn't match what your people actually do, ask questions before the audit.
Your experience modifier compares your claims history to that of similar businesses. A 1.00 mod is average. A 0.85 mod cuts your premium by 15%, and a 1.25 mod raises it by 25%. Mods generally use three years of claims, excluding the most recent year, so today's injury affects your bill for years.
Frequency hurts more than severity. Five small medical-only claims often damage a mod more than one larger claim. Pennsylvania offers medical-only claim handling, but small injuries still need to be reported properly, so check how claims are counted before you decide how to handle minor incidents.
Frequently Asked Questions About PA Workers Comp Costs
It helps to think of Act 72 as three gates the worker has to pass through, in order:
- A written contract exists. No contract, no independent contractor status. A handshake deal or a text thread won't hold up.
- The worker is free from your control. They must be free from control or direction over the performance of services both under the contract and in fact. That second part trips people up: a contract saying "contractor controls the work" means nothing if your foreman is telling them how to frame the wall.
- The worker runs an independently established business. This is where the criteria above come in: proprietary interest, profit or loss, separate location, and so on.
The "in fact" language deserves attention. Investigators look at what happens on the job site, not just what the contract says. If you set their schedule, supervise their methods, and they can't send someone else in their place, the control prong fails no matter how polished the agreement is.
Payroll" for workers comp means more than base wages. It generally includes overtime pay (with the premium portion often excluded), bonuses, commissions, holiday and vacation pay, and certain other compensation. Business owners often miscount this, and the error shows up at audit.
Corporate officers follow special rules. For policies effective April 1, 2026, officer payroll ranges from $70,044 to $280,800 per year for rating purposes. An officer who pays themselves very little still gets rated at the minimum, and high earners get capped at the maximum. That ceiling rose sharply this year, so owners who pay themselves well may see more of their salary counted than they did in past years.
Required Documentation for a Clean Audit
Yes. With key person coverage, the business applies for the policy, pays the premiums, and is the beneficiary. In a cross-purchase buy-sell setup, the individual owners own policies on each other instead.
If a covered loss forces you to close, business income coverage replaces lost net income and helps pay ongoing expenses like rent, payroll, and loan payments while you rebuild. Picture a Butler County bakery after a kitchen fire. The ovens are replaceable, but six weeks without sales could end the business. Most BOPs also include extra expense coverage, which pays for things like renting temporary space so you can reopen sooner. Coverage usually applies only when the closure comes from a covered property loss, not from a slow season or a supplier's problems.
Can I change the key person if they leave the company?
Generally, no. Death benefits are typically received income tax-free if the business met IRC Section 101(j) notice and consent rules before the policy was issued and files Form 8925 each year. Proceeds paid to a named beneficiary are also generally exempt from the Pennsylvania Inheritance Tax.
Key person coverage and a funded buy-sell agreement both answer the same question: what happens to this business if someone essential dies? The business owns the policy and collects the benefit, premiums typically aren't deductible, and the payout stays income tax-free when Section 101(j) paperwork is done correctly and on time. Choose term or permanent coverage based on how long the risk actually lasts, and revisit valuations and face amounts as the company grows.
If your buy-sell agreement hasn't been reviewed in a few years, or you've never put a number on your key people, now is a sensible time. MVP Insurance, with offices in Zelienople, PA and New Springfield, OH, can compare options from multiple carriers so you don't have to. Start a quote and get a clear picture of what coverage would cost.
MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
Term coverage is usually the practical fit for protecting against the loss of a key employee during a specific window, like the life of an equipment loan or the years before a planned retirement. If your top salesperson is 45 and plans to work 15 more years, a 20-year term policy covers that period with room to spare.
Buy-sell funding is less clear-cut. If owners plan to stay until death or a late sale, permanent coverage can make sense because term policies often expire right when older owners are most likely to die. Cash value in a whole life policy can also help fund a lifetime buyout at retirement. Universal life gives flexibility, but owners need to review in-force illustrations every few years. Underfunded universal life policies have caused real problems for businesses that assumed coverage would last.
Conversion privileges are worth checking on any term policy. They let you switch to permanent coverage later without new medical underwriting, which matters if the insured's health changes.
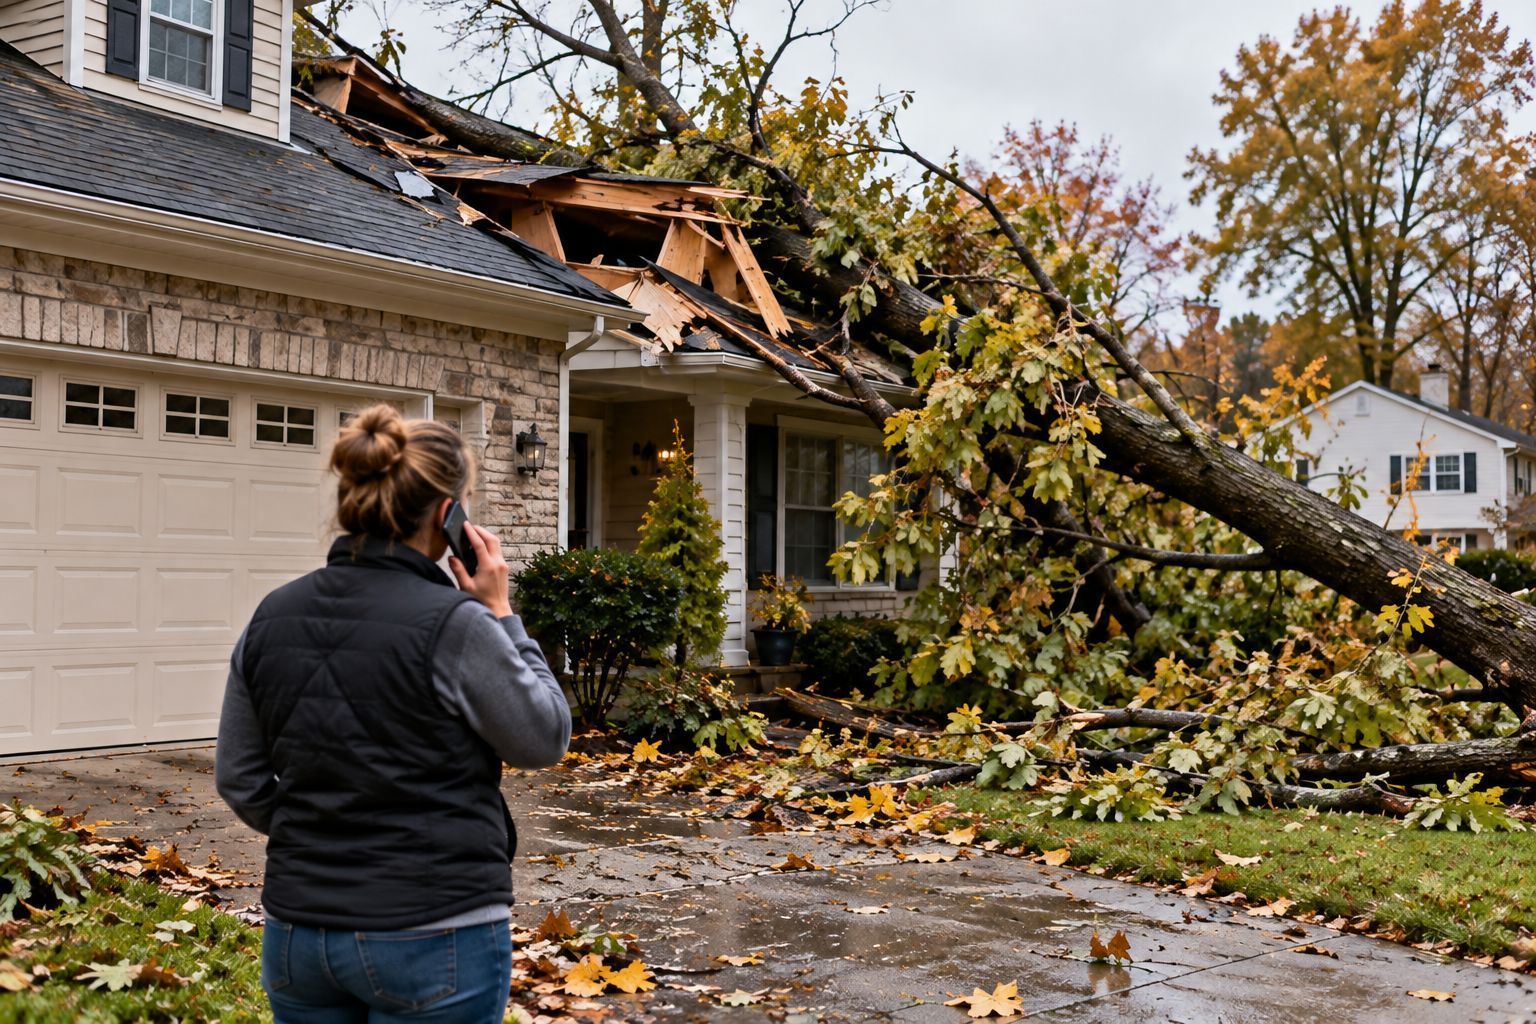
Ohio protects insurance consumers through the Ohio Department of Insurance (ODI). The department regulates how carriers sell policies and handle claims, sets deadlines insurers must meet, and runs a free complaint process when something goes wrong. If your insurer stalls or denies a claim unfairly, you can file a complaint with ODI and call free state hotlines for guidance.
That's the short version. The longer version matters because most disputes we hear about start small. A water damage claim sits unanswered for three weeks. An adjuster asks for the same receipts twice. A renewal notice raises a premium with no explanation. Knowing the rules, the timelines and who to call can turn a frustrating month into a quick fix. This guide walks through Ohio's consumer protections, the complaint steps, the deadlines insurers typically follow, and the free resources available to Ohio residents.
Ohio Insurance Department Consumer Protections and Rights
The Ohio Department of Insurance acts as the referee for the state's insurance market. It licenses agents and companies, reviews how carriers treat policyholders, and steps in when a consumer and an insurer can't resolve a dispute on their own. The department's own annual report frames this as keeping the market stable and competitive, noting that staff recovered or saved consumers millions of dollars through vigilant oversight over the past year.
For anyone carrying ohio personal insurance, such as auto, home, renters or umbrella coverage, those protections translate into a few practical rights:
- Policy transparency: You're entitled to clear policy documents and an explanation of what's covered and excluded.
- Fair claim handling: Insurers must respond to claims and inquiries within set timeframes and can't misrepresent policy terms.
- A written reason for denial: If a claim is denied, you should receive the reason tied to specific policy language.
- Access to dispute resolution: You can file a complaint with ODI at no cost.
One nuance trips people up. Health coverage disputes follow a different path. Ohio residents
must complete their health plan's internal appeal process before ODI can intervene in a medical coverage disagreement. Skip that step and your complaint will likely be sent back.
How to File a Complaint with the Ohio Department of Insurance
You can file a complaint with ODI online through the department's complaint center or by mail using the state's complaint form. Either way, the quality of your file determines how fast an analyst can act on it. Here's the process that tends to work:
- Contact your carrier first. Put your concern in writing to the insurer or adjuster and give them a chance to respond. ODI will want to see that you tried.
- Gather your documents. Pull together your policy number, claim number, the declarations page, and every email, letter or text exchanged with the carrier.
- Build a timeline. List dates: when the loss happened, when you reported it, when the adjuster inspected, and when you last heard back.
- Submit the complaint. Use the online portal for the fastest routing, or mail the printed form with copies (never originals) of your paperwork.
- Keep a copy of everything. Save your confirmation number and your submission.
Specifics help. A complaint that says "Progressive won't pay me" gives an analyst little to work with. A complaint that says "I reported a rear-end collision on March 3, the adjuster inspected March 10, and I've sent three emails since with no reply" is something ODI can act on immediately. The same applies whether your carrier is Erie, Westfield or anyone else: dated correspondence is your strongest evidence.
If you're unsure whether your issue qualifies, the state's guide to filing an insurance complaint lists the Consumer Services number, 800-686-1526, where you can speak with an analyst before filing.
Claim Handling Timelines and Ohio Administrative Code Requirements
Ohio sets written deadlines for how quickly insurers must communicate during a claim. These rules come mainly from the Ohio Administrative Code's unfair claims settlement provisions, plus a separate prompt pay law for health claims. Knowing them gives you a concrete benchmark: instead of wondering whether a delay is normal, you can compare it against what the rules require.
Required Deadlines for Claim Communications
As of this writing, Ohio Administrative Code 3901-1-54(F)(2) requires insurers to acknowledge receipt of a claim within 15 days. Insurers also typically must provide an appropriate reply to any written inquiry from a claimant within 15 days of receiving it. That second rule is the one most homeowners don't know about, and it's useful. If you emailed your adjuster asking about a roof estimate and heard nothing for three weeks, that silence may already fall outside the expected window.
The rules also expect insurers to begin investigating promptly and to tell you whether they accept or deny coverage within a set period after receiving proof of loss. If a carrier needs more time, it should explain why in writing and keep you updated. A denial should cite the specific policy provision it relies on.
Health claims run on Ohio's prompt pay law. If a health claim is materially deficient, the insurer typically must notify the provider within 15 days, and then has 45 days to process the claim once requested documentation arrives. Provider-side rules shifted recently too: as of July 8, 2026, insurers have one year rather than 24 months to recoup overpayments from providers, and providers now have 60 days instead of 30 to appeal a recoupment demand.
Comparison of Standard Ohio Claim Timelines
| Claim stage | Property and casualty | Health insurance |
|---|---|---|
| Initial acknowledgment | Typically within 15 days | Deficiency notice to provider typically within 15 days |
| Reply to written inquiries | Typically within 15 days | Handled under prompt pay rules |
| Investigation updates | Written explanation required if more time is needed | Insurer requests missing documentation |
| Final processing or payment | Decision and payment within the period set by the Administrative Code after proof of loss | Typically 45 days after documentation is received |
Prompt pay rules vary widely by state, so these timelines apply only to Ohio policies.
Where to Get Free Help and Insurance Guidance in Ohio
Ohio offers several free places to get help, and none of them require you to have a formal dispute. The ODI Consumer Services Division handles general questions about auto, home, life and health coverage, and analysts can explain your rights before you decide whether to file. The consumer complaint information page is a good starting point if you want to understand the process first.
Seniors and caregivers have a dedicated resource. The Ohio Senior Health Insurance Information Program (OSHIIP) provides free, unbiased Medicare counseling through its hotline at 800-686-1578. Counselors help with comparing plans, understanding Part D drug coverage and sorting out billing problems. From October 15 to December 7, 2026, ODI is also running statewide events to help Ohioans compare 2027 Medicare plans, and local agencies often host open enrollment help sessions as well.
Then there's local guidance from independent agencies. MVP Insurance, with an office in New Springfield, OH, helps clients understand coverage, review policy language and work through claims at no additional fee. Carriers compensate independent agents, so getting a second opinion on a confusing denial letter or renewal increase doesn't cost the policyholder anything extra.
The Role of Independent Agents in Resolving Policy Issues
An independent agent can often resolve a policy issue before it ever reaches the state. Because independent agents work with multiple carriers, they have established contacts at underwriting and claims departments and know how each company's process typically runs. That relationship gives them a practical route to escalate a stalled claim without a formal complaint.
Consider a few common situations. A homeowner insured through Western Reserve gets a partial payment on a wind claim but the estimate leaves out the gutters. An agent can review the adjuster's report, point to the policy language and request a supplemental review. A driver with Liberty Mutual sees a surcharge after a not-at-fault accident; the agent can ask the carrier to recheck the fault determination. A classic car owner with Hagerty disputes an agreed value after a loss, and the agent can pull the original appraisal and valuation records.
Agents also catch problems earlier. Many disputes trace back to coverage gaps nobody noticed at purchase: no water backup endorsement, liability limits too low for a household's assets, or a home business excluded under a standard homeowners policy. An annual review fixes these before a claim exposes them.
Agents can't override a carrier's decision, and some disagreements still belong with ODI. But when an agent has already documented the issue, your complaint arrives stronger and better organized.
Frequently Asked Questions About Ohio Insurance Protections
How do I check an agent's license in Ohio? Use the license lookup tool on the Ohio Department of Insurance website or call Consumer Services at 800-686-1526. You can confirm whether an agent or agency holds an active license and which lines of insurance they're authorized to sell.
What happens after I file a complaint with the state? An ODI analyst reviews your complaint and contacts the insurance company, which must respond to the department. The analyst checks whether the carrier followed Ohio law and the policy terms, then lets you know the outcome.
How long does an insurance company have to pay a claim in Ohio? It depends on the type of claim. Health insurers typically have 45 days after receiving requested documentation, while property and auto insurers must acknowledge claims within 15 days and decide and pay within the timeframes set by the Ohio Administrative Code.
The rules work best when you know them before you need them. Keep your correspondence dated, compare delays against the 15-day benchmarks, finish internal appeals on health claims, and lean on free state resources like Consumer Services and OSHIIP. These Ohio consumer protections exist so that policyholders aren't left guessing.
If you'd rather have someone in your corner from the start, MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH, licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. We compare coverage from carriers like Erie, Westfield and Progressive and stay involved when claims get complicated. When you're ready,
start your quote and see what a local review turns up.
Search
Recent Posts



MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.