


Owner, MVP Insurance
Ohio homeowners insurance covers the usual fire, theft, and liability risks, but the real gaps show up in the details: percentage-based wind and hail deductibles, water backup exclusions, freeze damage conditions, and rebuild costs on older homes. In the Mahoning Valley, getting those details right matters more than chasing a low premium.
The market has stabilized after a few rough years. Ohio carriers returned to underwriting profit with combined ratios of 92% in 2024 and 74% in 2025, after two years of triple-digit losses. That's good news for availability, but carriers didn't get there by accident. Many tightened deductibles, trimmed coverage, and got pickier about older roofs and wiring. If your policy renewed in the last two years without a careful review, there's a decent chance it changed in ways you haven't noticed.
Navigating Ohio Homeowners Insurance Coverage Requirements
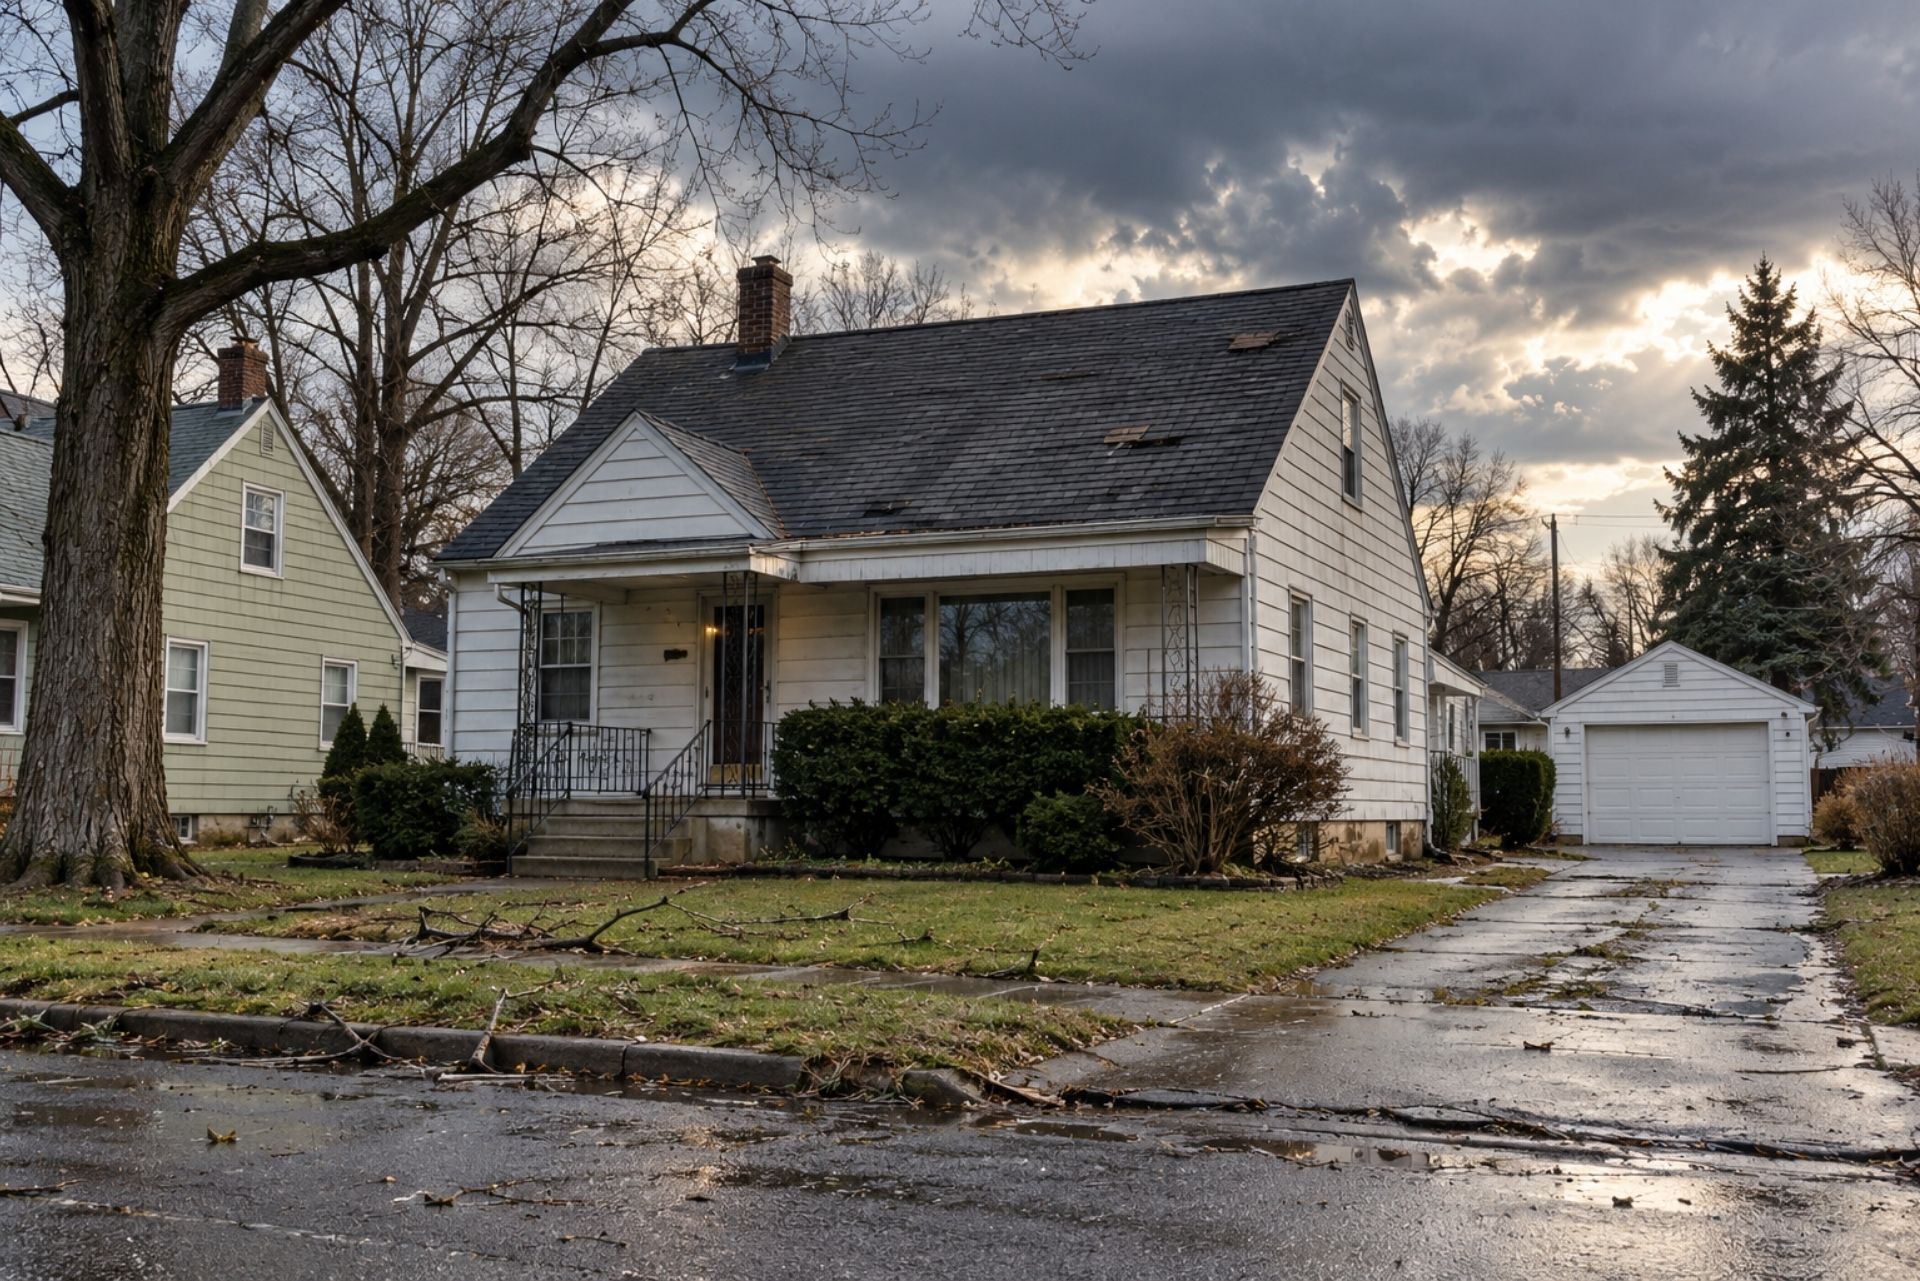
A solid Ohio policy pairs standard property protection with coverage built for this region's specific threats: spring wind and hail, basement water backup, and January pipe bursts. For Mahoning Valley homeowners, it also has to account for houses built 70 to 100 years ago and deductible structures that have shifted quietly over recent renewals.
Ohio doesn't legally require homeowners insurance, but your mortgage lender almost certainly does. Lenders care about the dwelling limit. You should care about everything else, including how the deductible works, what's excluded, and whether the policy pays to rebuild or just pays depreciated value.
Judith L. French, Director of the Ohio Department of Insurance, put it plainly: Ohioans without adequate protection risk facing costly out-of-pocket repairs, and an agent review helps confirm coverage reflects a home's full value. That advice lands hardest in older neighborhoods where market value and rebuild cost have drifted far apart.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
| Coverage | PA Minimum | Common Recommendation |
|---|---|---|
| Auto bodily injury | $15,000 / $30,000 | $250,000 / $500,000 |
| Auto property damage | $5,000 | $100,000 |
| Medical benefits (auto) | $5,000 | $10,000 or more |
| Home personal liability | None required | $300,000 to $500,000 |
| Umbrella | None required | $1 million or more |
Understanding Wind and Hail Deductibles in Ohio
Percentage-based wind and hail deductibles are spreading across Ohio policies, and they're the change most likely to surprise you after a storm. Instead of a flat $1,000 deductible, the carrier sets your wind and hail deductible as a percentage of your dwelling coverage.
The math adds up fast. Many Ohio insurers now use 1% or 2% of the dwelling limit, so a 2% deductible on a $350,000 home means $7,000 out of your pocket before the policy pays a dime on a hail-damaged roof. Your all-other-perils deductible might still read $1,000, which is why people often miss the change.
Here's how the two structures compare on that same $350,000 home:
- Flat $1,000 deductible: you pay $1,000 on any covered storm claim
- 1% wind/hail deductible: you pay $3,500
- 2% wind/hail deductible: you pay $7,000
A common mistake we see is a homeowner raising their dwelling limit to keep up with construction costs (the right move) without realizing their storm deductible rose with it. Sometimes paying a bit more in premium for a flat deductible is the smarter trade, especially if you have an older roof.

Written By
David Varrati
Owner, MVP Insurance
On this page
Where you live
Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.
Where you live
Basement Water Backup and Sump Pump Failure
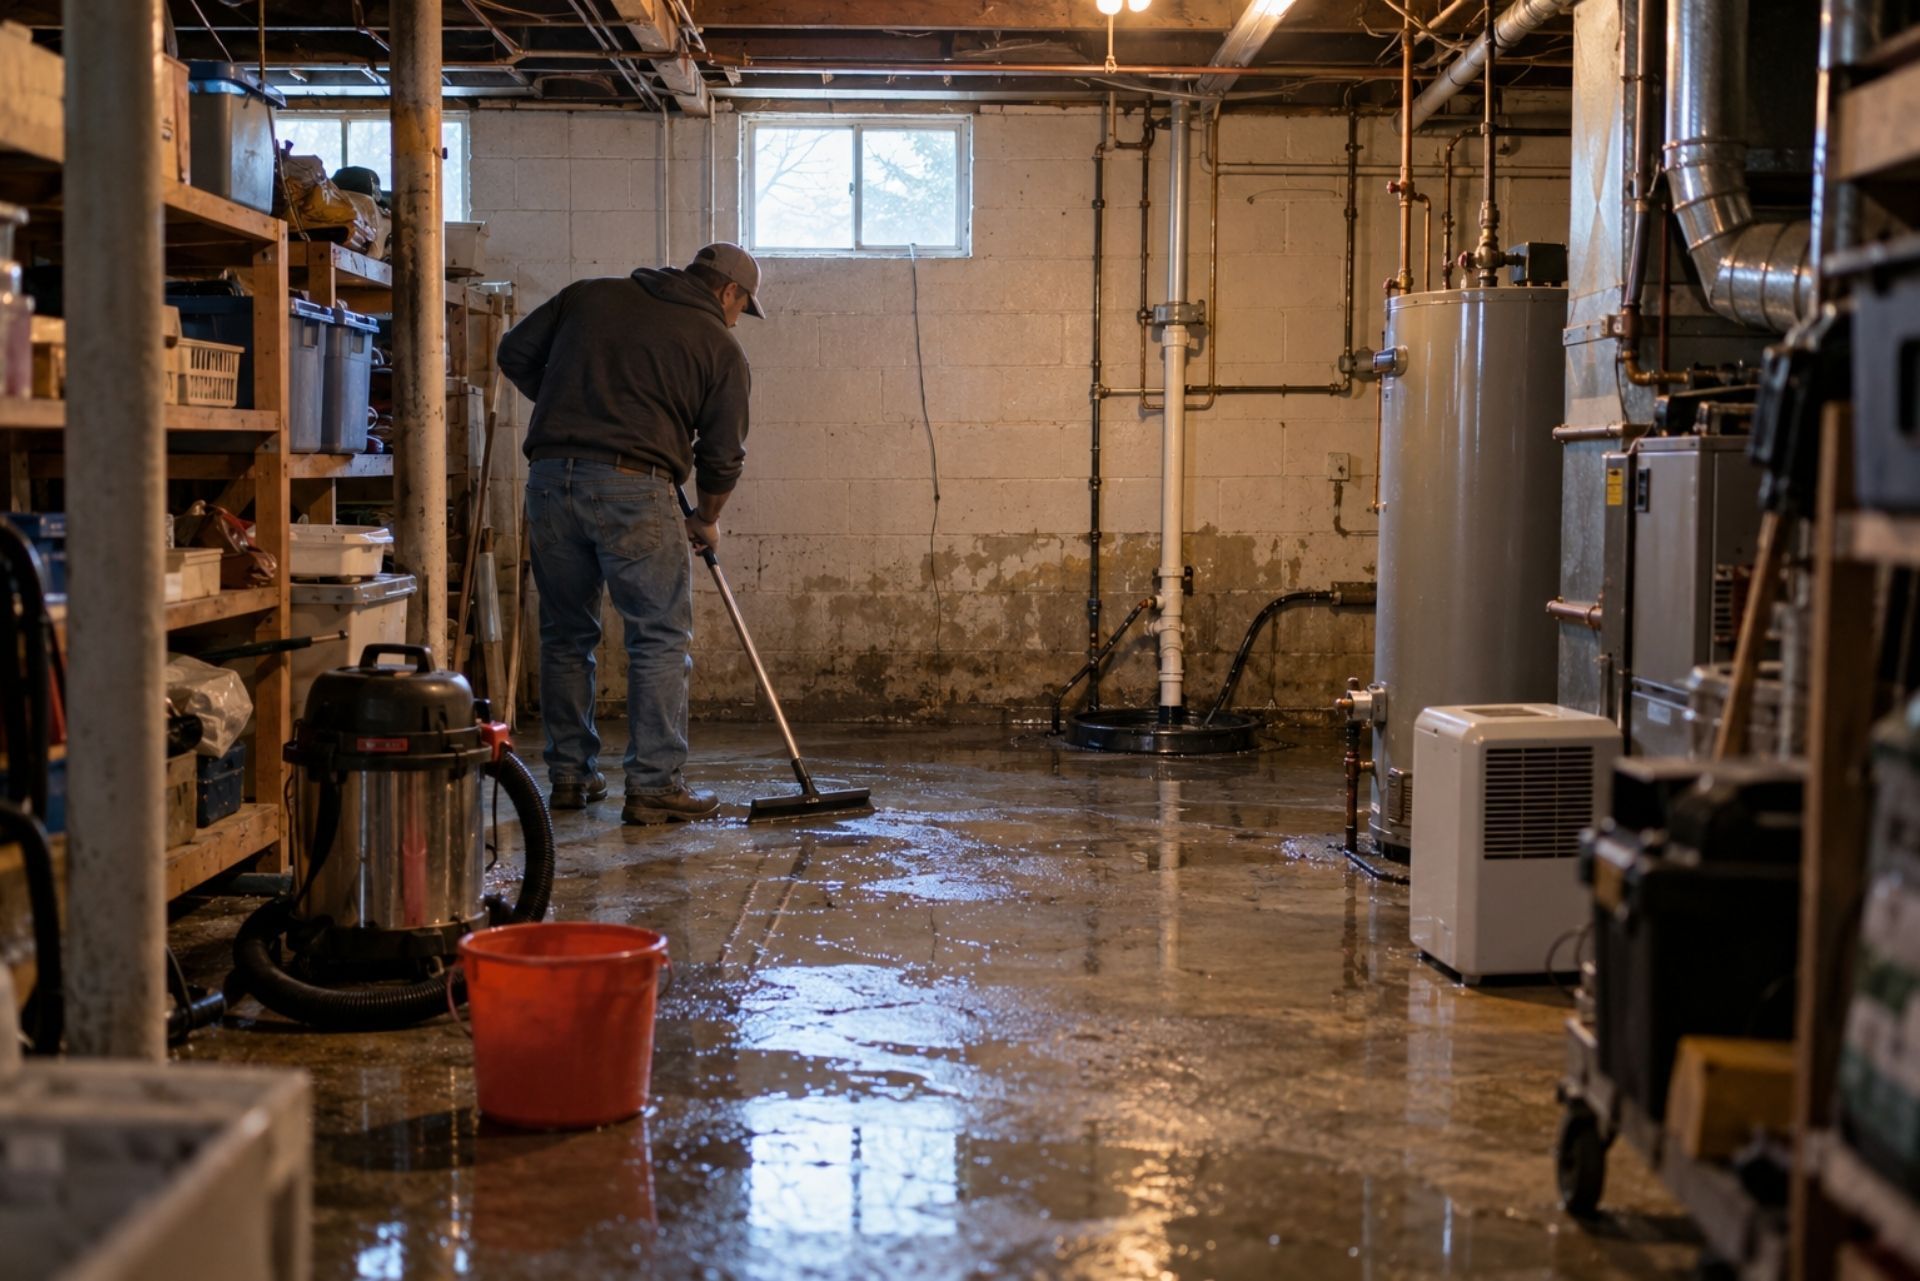
Standard homeowners policies generally exclude water that backs up through drains or overflows from a failed sump pump. You need a specific water backup endorsement to cover it, and it's one of the most valuable add-ons for Ohio homes.
Picture a heavy April storm. The power flickers out, the sump pump stops, and by morning there's six inches of water across the finished rec room. Carpet, drywall, a sectional, the kids' gaming setup: none of it is covered without the endorsement. Plenty of homeowners assume "water damage" is just covered, and they find out otherwise during the claim call.
Endorsement limits typically come in tiers, such as $5,000, $10,000, or $25,000. If you've finished your basement, pick a limit that matches what's actually down there. Older homes with clay tile sewer laterals or original floor drains carry extra risk, so a battery backup pump and a backflow valve are worth installing alongside the coverage.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Life Insurance
Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.
Preventing and Covering Freeze Damage
Burst pipes from freezing are typically covered under Ohio homeowners policies, but only if you took reasonable care to keep heat on. Most policies include a condition stating that freeze losses aren't covered if the home was left unheated, unless the water was shut off and lines drained.
That condition matters most when a house sits empty. Snowbirds heading south, a family member's home sitting vacant during an estate settlement, or a rental between tenants are all classic setups for denied claims. If the furnace quits on day three of a two-week trip and nobody checks, the carrier will ask what you did to maintain heat.
A few habits protect both your pipes and your claim:
- Keep the thermostat at 55°F or higher, even when you're away
- Have someone check the house every few days during cold snaps
- Install a smart thermostat or water sensor that sends alerts
- Shut off and drain water to a vacant property
Pipes in exterior walls and crawlspaces, common in older Valley homes, freeze first. Insulate them before December.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Insuring Older Mahoning Valley Housing Stock
Older homes in Youngstown, Boardman, Struthers, and out toward New Springfield are fully insurable, but carriers look harder at them. Underwriters want to know the age and condition of four things: roof, electrical, plumbing, and heating.
The concerns are real. A regional housing assessment found that 1 in 4 Mahoning Valley households face severe housing problems, including inadequate plumbing or kitchen facilities tied to aging infrastructure. Knob-and-tube wiring, 60-amp fuse panels, galvanized supply lines, and cast-iron drains can all trigger a decline or a surcharge with some carriers.
Documentation helps more than people expect. If you replaced the panel in 2019 or repiped in 2021, keep the invoices handy. An independent agent can match a well-maintained 1920s colonial with a carrier that rewards updates, rather than one that rejects anything built before 1950.
Replacement Cost Rebuilds vs Actual Cash Value
Replacement cost pays to rebuild your home with similar materials at today's prices. Actual cash value subtracts depreciation, which can leave you far short on an older house.
Here's the trap: a Youngstown home might sell for $110,000, but rebuilding 1,800 square feet after a fire costs far more. Ohio rebuild estimates for 2026 run roughly $120 to $350+ per square foot depending on location and finishes, and skilled labor costs rose about 5.7% in early 2026 alone. Even at the low end, that's well over $200,000. Mahoning County itself updates permit fees using 2026 average square-foot construction costs, which shows how official estimates track that rising curve.
Older homes also have to meet current code when rebuilt, so ask about ordinance or law coverage. Without it, the cost of bringing wiring, egress windows, and plumbing up to code falls on you.
Ohio Mine Subsidence Insurance Program
Ohio runs its own mine subsidence insurance program, generally available in certain counties with a history of underground coal mining. It covers structural damage when the ground settles or collapses into abandoned mine workings, which standard policies typically exclude as earth movement.
In designated counties, this coverage is usually added to your homeowners policy for a small fee. If you live in a historically mined area of eastern Ohio, ask whether your county participates and whether the coverage is already on your policy.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Life Insurance
Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.
The Ohio FAIR Plan as a Market of Last Resort
The Ohio FAIR Plan is a state-monitored option for homeowners who can't get coverage in the regular market, usually because of property condition, vacancy, or claim history. It's generally considered the market of last resort, not a first choice.
The plan is supported by all insurance companies licensed in Ohio, which share in its losses proportionally. To qualify, you typically need proof of denial from at least two private insurers. Coverage tends to be narrower than a standard policy, so review the plan's available coverages carefully.
The program also changes. Updates came through Bulletin 33 in February 2025 and Bulletin 34 in February 2026. Many homeowners use the FAIR Plan temporarily while they replace a roof or update wiring, then move back to a standard carrier.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Comparing Ohio Property Coverage Options
This table shows typical coverage parts and how they're commonly set. Your actual limits depend on the home and carrier.
| Coverage | What It Covers | Typical Setting |
|---|---|---|
| Dwelling (A) | The house structure | Full replacement cost |
| Other Structures (B) | Garage, shed, fence | Often 10% of Dwelling |
| Personal Property (C) | Belongings | Often 50-70% of Dwelling |
| Loss of Use (D) | Living costs after a loss | Often 20-30% of Dwelling |
| Liability (E) | Injuries, property damage to others | $300,000 to $500,000 |
| Water Backup | Drain or sump overflow | Optional, $5K to $25K |
| Ordinance or Law | Code upgrades on rebuild | Optional, % of Dwelling |
| Mine Subsidence | Collapse from old mines | Optional, select counties |
For context, the projected average Ohio premium for 2026 sits around $2,080 a year, below the national average of about $2,490. The statewide market reached roughly $5.1 billion in written premium by 2025.
Written By
David Varrati
Owner, MVP Insurance
On this page
The Role of Umbrella and Life Insurance in a Comprehensive Plan
Life Insurance
Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.
Common Questions About Ohio Home Insurance
Can I bundle home and car insurance in Ohio? Yes, and bundling often lowers your total cost. Our Ohio car insurance options can pair with your home policy, often with the same carrier.
Where do I find personal insurance in Ohio for my whole household? An independent agent can quote home, auto, umbrella, and more at once. See our personal insurance options in Ohio for the full lineup.
Does Erie offer water backup coverage in Ohio? Erie generally offers water backup as an endorsement, with limits that vary by policy. MVP Insurance works with Erie as an independent agent and can compare it against other carriers.
Is Westfield good for older homes? Westfield writes many Ohio homes and typically looks closely at updates to roofs and systems. Documented renovations usually help your application.
Does Progressive insure homes in Ohio? Yes, Progressive offers Ohio homeowners coverage and is often bundled with its auto policies.
What if my older home gets declined? Carriers like Foremost or American Modern sometimes write homes standard carriers won't, and the Ohio FAIR Plan exists as a last resort.
Written By
David Varrati
Owner, MVP Insurance
On this page
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Consulting with MVP Insurance in New Springfield
A good Ohio home policy comes down to the fine print: a storm deductible you can actually afford, water backup for the finished basement, heat conditions you understand, and a dwelling limit that reflects true rebuild cost on an older house. Those choices decide whether a claim feels manageable or devastating.
Josh Medure and David Varrati founded MVP Insurance in 2008 as an independent agency, which means they shop multiple carriers for you instead of selling one company's product. Stop by the New Springfield office at 13823 Grant St, New Springfield, OH 44443, or call (330) 707-9055. Pennsylvania clients can visit 108 E Grandview Ave, Zelienople, PA 16063, or call (724) 453-1122. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293.
If your policy hasn't had a real review since your last renewal, now's a smart time. Start your quoteand let a local agent compare carriers and catch the gaps before a storm finds them.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.



About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.
General Liability
Business Owners Policy
Professional Liability
Commercial Property
Workers Compensation
Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.
Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.













