


Ohio Commercial Auto Insurance

Owner, MVP Insurance

Ohio commercial auto insurance covers the trucks, vans, and cars your business uses, plus the liability that follows when an employee is behind the wheel. A solid policy should account for work equipment, rented and personal vehicles used for errands, who is allowed to drive, and the trips your crews make across the Pennsylvania line.


That last point matters more than most owners realize. If your shop sits anywhere near New Springfield, a "local" job can mean a 15-minute run east on US-224 or a hop onto I-680 heading toward the state line. Many Mahoning Valley businesses work both states every week, and their insurance needs to keep up.


The rest of this page breaks down how each piece fits together, where gaps tend to hide, and what to ask before you sign.

Essential Ohio Commercial Auto Insurance for Local Businesses

Commercial auto coverage protects your business from the financial fallout of an accident involving a company vehicle: injuries to other people, damage to their property, and repairs to your own truck. A personal auto policy usually won't respond when a vehicle is titled to a business or used mainly for work. That's the gap commercial auto fills.


MVP Insurance was founded in 2008 by Josh Medure and David Varrati to help businesses in the Mahoning Valley and western Pennsylvania find coverage that fits how they actually operate. As an independent agency, MVP shops multiple carriers instead of pushing one company's product. That matters for business vehicles, because carriers price contractors, delivery outfits, and service companies very differently.


Meeting Ohio's legal minimum is the floor, not the goal. The real job of the policy is protecting the assets you've spent years building, including the work trucks and vans that keep revenue coming in.

David Varrati

By: Joshua Medure

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page
Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Protecting Your Work Trucks and Vans

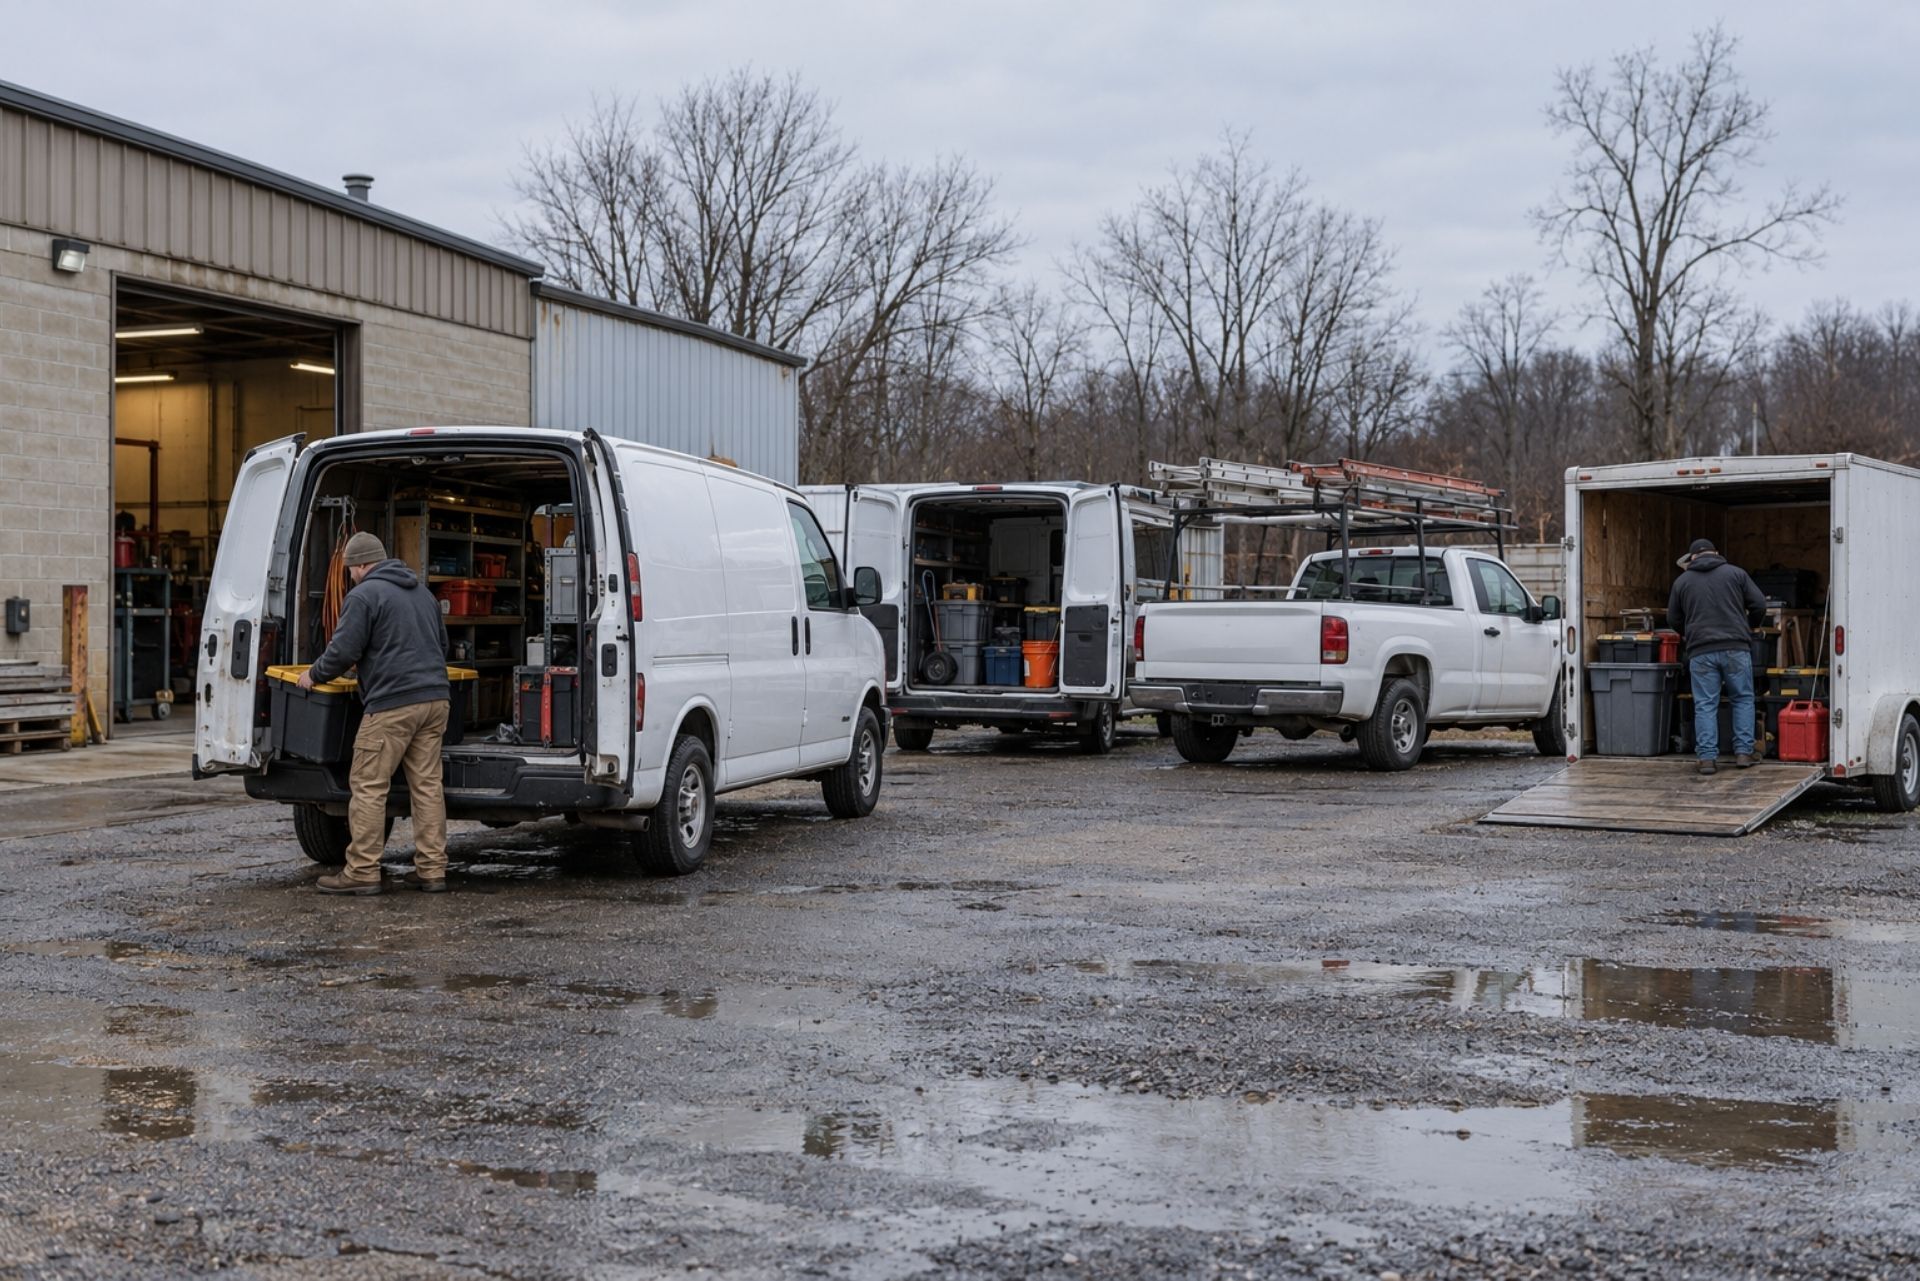
Work trucks and vans need coverage built around heavy use and the gear they carry. A plumber's van with shelving, a landscaper's pickup pulling a trailer, and an electrician's box truck all carry risks a standard sedan never faces.


Here's where owners get caught. The auto policy covers the vehicle and the liability from driving it, but tools and materials inside often fall under a separate policy. If someone breaks into your van overnight and takes $8,000 in power tools, your auto policy may pay for the broken window and nothing else. Inland marine or tools and equipment coverage usually handles the contents.


A few things worth confirming on any work vehicle:


  • Permanently attached equipment:Ladder racks, upfits, and lift gates should be listed so they're valued correctly.
  • Trailers:Some policies cover liability for a trailer while towed but not physical damage to the trailer itself.
  • Loading and unloading:Injuries during unloading can fall between auto and liability policies.


The cleanest setup ties your auto policy to your broader business insurance in Ohioand your general liability insurance, so the vehicle, the cargo, and the work site all line up without gaps.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Understanding Hired and Non-Owned Auto Liability

Hired and Non-Owned Auto (HNOA) coverage protects your business when an employee uses a personal car for work or when you rent a vehicle for a job. If you don't own a single company vehicle, you may still need this.


Picture an office manager driving her own SUV to pick up supplies and rear-ending someone at a light. Her personal insurance responds first. But if the injuries are serious and her limits run out, the injured party's attorney will look at who she was working for. Without HNOA, your business pays that defense and any judgment out of pocket.


Hired auto works the same way for rentals. If you rent a box truck for a weekend move or a pickup while yours is in the shop, the hired portion extends your liability protection to that vehicle.


HNOA is often inexpensive to add to a general liability or business owners policy. For small firms with no fleet, it's one of the most overlooked coverages we see.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Managing Driver Eligibility and Fleet Coverage

Fleet coverage puts multiple vehicles on one policy with one renewal date, which makes life easier once you're running three or more units. The catch is that carriers scrutinize every driver, and one bad record can raise the price for the whole fleet or get a driver excluded.


Ohio uses a point system where accumulating 12 points within two years triggers a six-month license suspension. Underwriters are much stricter than the BMV. Many commercial carriers in 2026 disqualify drivers with more than 4 to 6 points or one major violation within the past three years. So a driver with a perfectly valid license can still be uninsurable on your policy.


CDL holders deserve extra attention this year. The Ohio BMV began downgrading roughly 5,000 non-domiciled CDLs to standard Class D licenses to comply with updated FMCSA rules. If any of your drivers fall into that group, their eligibility for heavier vehicles may have changed.


MVP Insurance helps owners pull and review motor vehicle records before hiring and at renewal, so you know where every driver stands before a carrier tells you. It also helps to remember that PUCO runs inspections year-round, checking fleet safety and logbook accuracy.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Commercial auto works best as one piece of a broader plan. When an employee is hurt in a crash while driving for work, workers' compensation usually responds to their injuries, while your auto policy handles injuries to others and vehicle damage. Make sure your Pennsylvania workers comp coverage and your auto policy are coordinated so nobody falls between them.


General liability, property, and inland marine coverage for tools round out the picture. A contractor's tools stolen from a truck bed may fall under inland marine rather than auto. Reviewing your Pennsylvania business insurance together with your auto policy is the most reliable way to spot those gaps.

Integrating Workers Comp and Business Insurance

Cross-Border Trips Into Pennsylvania on I-680 and US-224

Most commercial auto policies cover you anywhere in the U.S., but crossing into Pennsylvania still raises real questions about registration, filings, and limits. New Springfield sits right next to the state line, so for a lot of local contractors and service companies, Pennsylvania jobs are routine.


A typical day might start in Boardman, run east on US-224 toward New Castle, then swing back up I-680. Your policy should reflect that reality. If your application says you operate "within 50 miles of Youngstown" and you're actually running regular routes into Lawrence or Mercer County, tell your agent. Misstated radius or territory can create problems at claim time.


Heavier vehicles have an added requirement. Commercial vehicles over 26,000 lbs, or with three or more axles, that travel between Ohio and Pennsylvania need apportioned registration through the International Registration Plan, which splits registration fees between both states.


State laws differ on things like minimum limits and how certain claims are handled, so confirm with your agent that your coverage holds up on both sides of the line (verify at publish). Our offices in New Springfield and Zelienople handle these two-state setups regularly.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Life Insurance

Comparing Commercial Auto Limits and State Requirements

Legal minimums and what your contracts actually require are two very different numbers. Ohio's statutory minimum of 25/50/25 is widely considered operationally inadequate for commercial work, and most commercial construction contracts now require a $1,000,000 combined single limit.

Item Ohio Pennsylvania Common for Business Use
Bodily injury per person $25,000 Set by PennDOT (verify at publish) Included in $1M CSL
Bodily injury per accident $50,000 Set by PennDOT (verify at publish) Included in $1M CSL
Property damage $25,000 Set by PennDOT (verify at publish) Included in $1M CSL
Contract requirement Not set by state Not set by state Often $1M CSL
IRP registration (26,001+ lbs, interstate) Required Required Confirm before first trip

A combined single limit gives you one pool of money for any mix of injury and property damage in a single accident. That flexibility matters when one crash involves three cars and a damaged storefront.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Commercial auto works best as one piece of a broader plan. When an employee is hurt in a crash while driving for work, workers' compensation usually responds to their injuries, while your auto policy handles injuries to others and vehicle damage. Make sure your Pennsylvania workers comp coverage and your auto policy are coordinated so nobody falls between them.


General liability, property, and inland marine coverage for tools round out the picture. A contractor's tools stolen from a truck bed may fall under inland marine rather than auto. Reviewing your Pennsylvania business insurance together with your auto policy is the most reliable way to spot those gaps.

Integrating Workers Comp and Business Insurance

Frequently Asked Questions About Commercial Auto Insurance

How much does commercial auto insurance cost in Ohio? It depends on vehicle type, how far you drive, your industry, and your drivers' records. The fastest way to get a real number is to have an independent agent compare several carriers for you.


Do I need commercial auto if I use my personal truck for work? Often, yes. If the truck is used mainly for business, carries tools, or is titled to your company, a personal policy may deny the claim.


What's the difference between hired and non-owned auto? Hired covers vehicles you rent or borrow for business. Non-owned covers your liability when employees drive their own cars on company errands.


Will my Ohio policy cover me in Pennsylvania? Most commercial auto policies cover travel across the U.S. Still, heavier trucks may need IRP registration, and you should list your regular Pennsylvania territory on the policy.


Can one bad driver affect my whole fleet? Yes. A driver with recent major violations can raise your premium or be excluded entirely, so review records before hiring.


Is there an agent near New Springfield or Zelienople? MVP Insurance has offices in both towns, which helps businesses that work on both sides of the state line.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Life Insurance

A combined single limit gives you one pool of money for any mix of injury and property damage in a single accident. That flexibility matters when one crash involves three cars and a damaged storefront.

Item Ohio Pennsylvania Common for Business Use
Bodily injury per person $25,000 Set by PennDOT (verify at publish) Included in $1M CSL
Bodily injury per accident $50,000 Set by PennDOT (verify at publish) Included in $1M CSL
Property damage $25,000 Set by PennDOT (verify at publish) Included in $1M CSL
Contract requirement Not set by state Not set by state Often $1M CSL
IRP registration (26,001+ lbs, interstate) Required Required Confirm before first trip

Consult With MVP Insurance for Your Business Coverage

Good Ohio commercial auto insurance should match how your business really moves: the vans loaded with gear, the employee running to the supply house in her own car, the drivers whose records carriers will check, and the crews heading east on US-224 for a Pennsylvania job. When those pieces connect to your liability and business policies, you avoid the gaps that turn one accident into a serious financial hit.


For a professional policy review, call the Zelienople office at 108 E Grandview Ave, (724) 453-1122, or the New Springfield office at 13823 Grant St, (330) 707-9055. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.


If you'd rather start online, you can request a quoteand let MVP compare carriers for you. A short conversation now costs far less than finding a coverage gap after a crash.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

Joshua Medure

Owner, MVP Insurance


I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.


Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.
Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.

Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania









