

Owner, MVP Insurance
Yes, you can get an NFIP flood policy written through American Bankers from a local Pennsylvania agent. MVP Insurance is an independent agency that works with American Bankers to place flood coverage for homes and businesses across the state. We handle quoting, elevation questions, and timing the policy around your closing date.
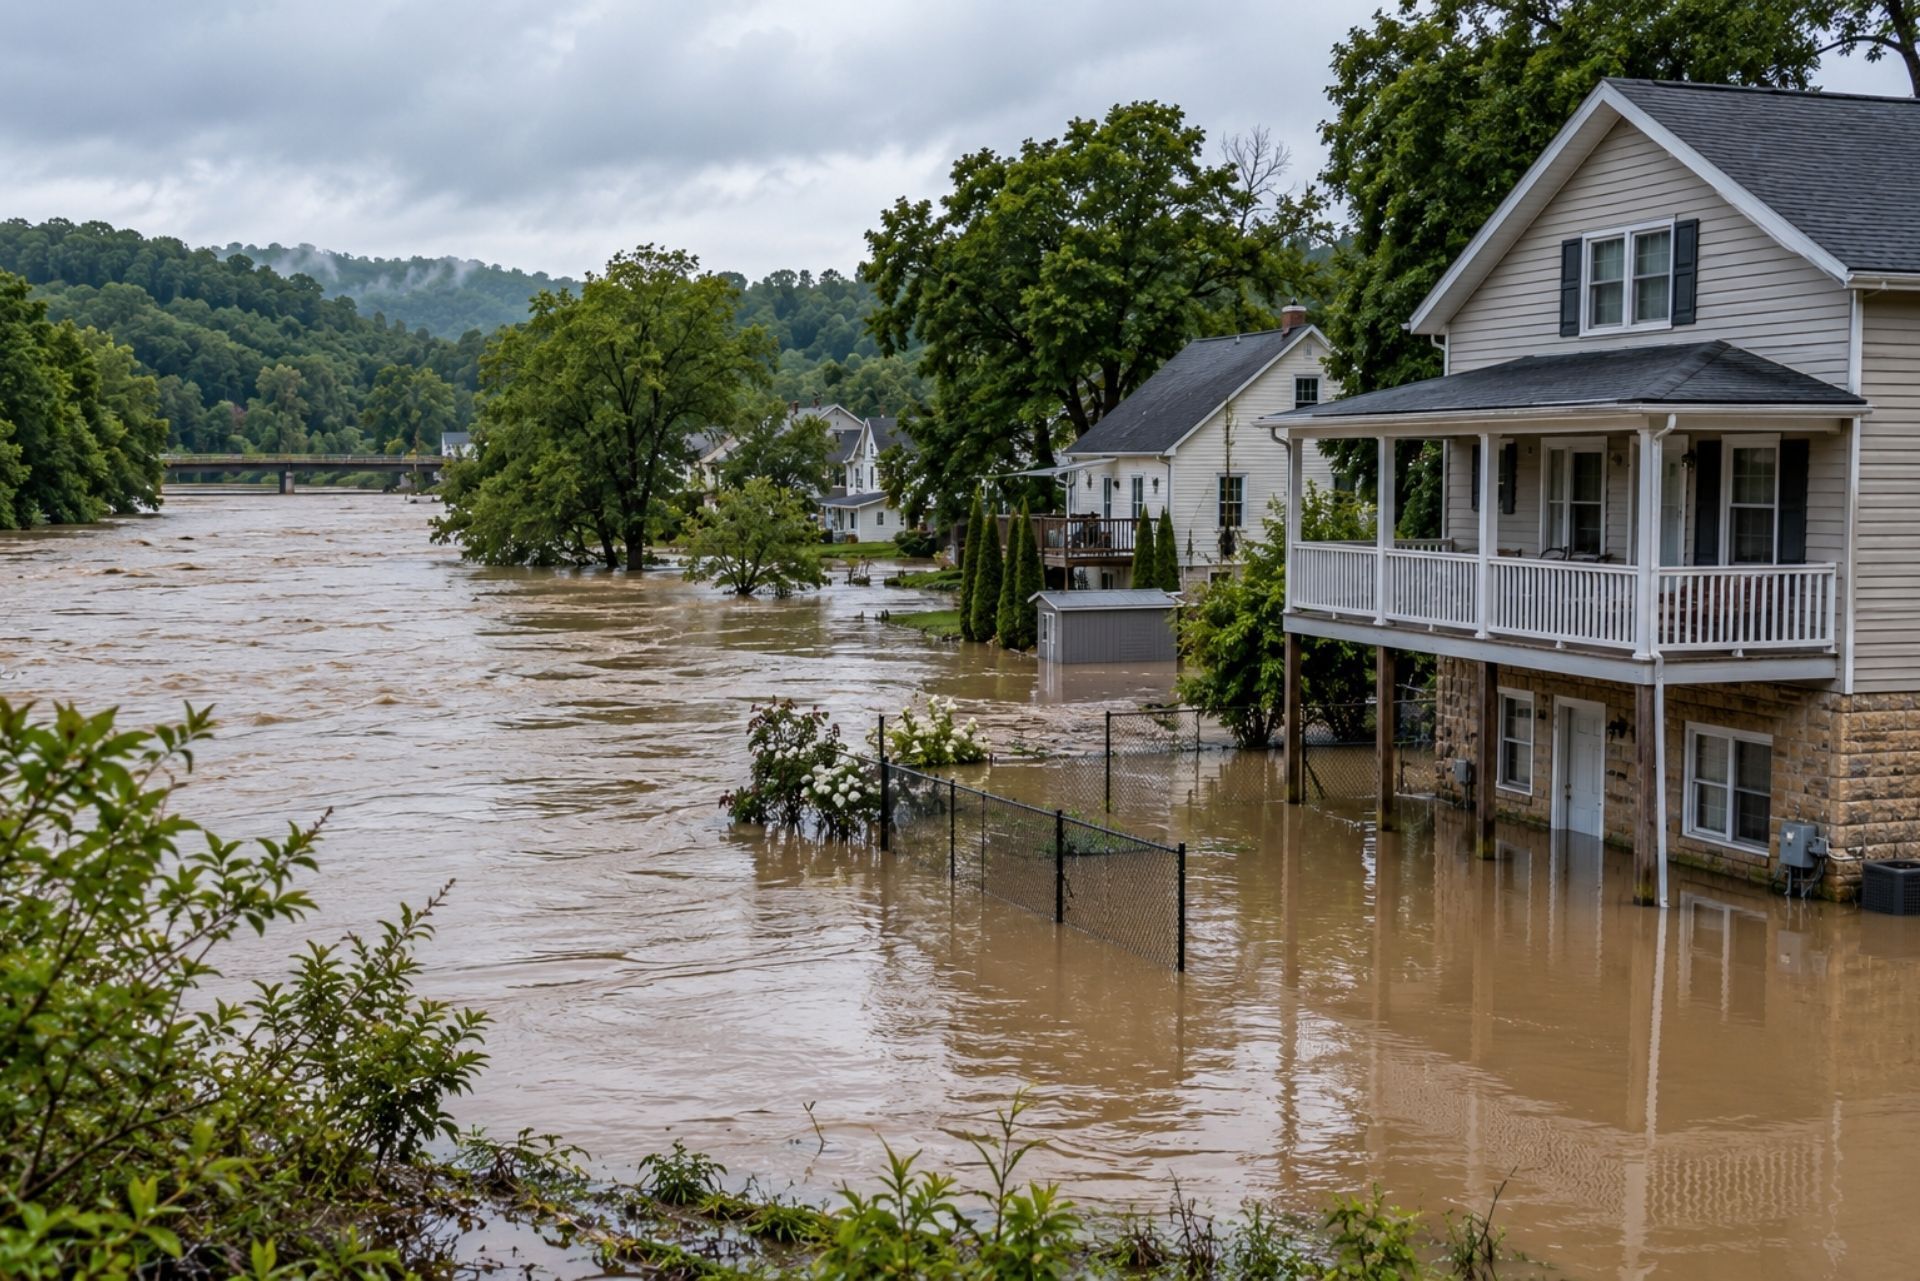
That last point matters more than most people expect. A buyer finds the house, gets the inspection back, locks a rate, and then hears from the lender two weeks before closing that the property sits in a Special Flood Hazard Area. Suddenly flood insurance is a requirement, and nobody has explained building limits, contents coverage, or what an Elevation Certificate is. Pennsylvania has plenty of these surprises. State officials point out that all 67 Pennsylvania counties have experienced destructive flooding, so river towns along the Ohio, Allegheny, Susquehanna, and Delaware are not the only places at risk.
This page walks through how American Bankers flood policies work, what they typically cover, and how to have coverage active on the day you sign.
Looking for an American Bankers Agent in Pennsylvania?
MVP Insurance is an independent agency that works with American Bankers to provide flood insurance throughout Pennsylvania. Our offices are at 108 E Grandview Ave in Zelienople, PA, and 13823 Grant St in New Springfield, OH. We are not American Bankers. We are an independent agent that places flood policies with them, alongside the other carriers we represent.
That distinction shapes how we work. A carrier's own representatives can tell you about their policy. An independent agent can tell you whether that policy fits your situation, and whether a different option makes more sense. For flood, American Bankers is often a strong fit because it writes standard NFIP policies, which many Pennsylvania lenders accept without a second look.
You can see the full list of companies we work with on our carriers page. If you want a broader picture of flood risk and coverage in the state, our Pennsylvania flood insurance guidecovers zones, costs, and common gaps in more depth. For American Bankers specifically, the rest of this page covers what local Pennsylvania American Bankers insurance agents can do for you.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Why People Look for an American Bankers Agent
People usually search for an American Bankers agent because the carrier is a major Write Your Own (WYO) company for the National Flood Insurance Program. That means the policy itself is federal flood coverage with standardized terms, but American Bankers handles the paperwork, billing, and claims administration. Homeowners like that combination: government-backed coverage, managed by a large established insurer.
Some people arrive here for a narrower reason. Their lender's flood determination came back positive, or their previous policy was already with American Bankers and they want a local contact instead of a phone tree. Others inherited an American Bankers flood policy when they bought a house, since NFIP policies can sometimes be assigned from the seller to the buyer.
The carrier also has real presence in this state. As of this writing, American Bankers Insurance Company of Florida ranks third in Pennsylvania for private flood market share, which tells you a lot of Pennsylvanians already trust it with flood risk. Whatever brings you here, the goal is the same: the right flood policy, written correctly, without missing a deadline.
Why Work With MVP Instead of Going Direct
Working with MVP gives you a local agent who knows Pennsylvania geography, not a generic 1-800 number. American Bankers does have a central line for NFIP policy management, reachable at 800-423-4403, and that line serves a purpose. But the person answering it likely has never driven Route 19 through Zelienople or seen how Connoquenessing Creek behaves after a week of rain.
Local knowledge shows up in small ways that save money and headaches. We know which neighborhoods tend to have pre-FIRM homes with low lowest-floor elevations. We know which lenders push for maximum building limits and which accept the loan balance. We know that a basement finished in a flood zone can create a coverage gap that surprises people after a claim.
Here is what you get working through us:
- One point of contact for quotes, changes, renewals, and mortgagee updates
- Comparison shopping across carriers, since we work for you, not for American Bankers
- 24/7 claims support so you are not stuck on hold after a storm
- Coordination with your lender and title company when you are buying a home
That last one is often the difference between a smooth closing and a delayed one.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Physical Damage Coverage for Tractors and Trailers
Trailer Interchange and Non-Owned Equipment
If you pull trailers you don't own under a written interchange agreement, your own physical damage policy usually won't cover them. Trailer interchange coverage handles damage to non-owned trailers while they're in your possession under that agreement.
Non-owned trailer coverage is a related option for trailers you use without a formal interchange contract. Intermodal carriers hauling containers out of ports and drayage operators run into this constantly. Read the agreement you sign with the trailer owner, since it often spells out the limit you're expected to carry.
NFIP Flood Policies Written Through American Bankers
An NFIP flood policy through American Bankers is federally backed coverage that typically follows NFIP rules for rating, coverage terms, and claims. American Bankers acts as the servicing company, but the coverage language comes from the federal Standard Flood Insurance Policy. That means the core terms generally look the same whichever WYO carrier you choose.
These policies may be written for several property types:
- Single-family homes, including primary residences and secondary homes
- Condo units and condo associations
- Small apartment buildings
- Commercial buildings such as storefronts, offices, and warehouses
Rating under the NFIP's current approach typically considers factors like distance to water, flood frequency, elevation, foundation type, and rebuilding cost. That is why two houses on the same street can carry very different premiums. A raised ranch on a crawlspace may rate quite differently from a split-level with a finished walkout basement.
A common mistake we see: homeowners assume their regular homeowners policy covers flood. It generally does not. Pennsylvania lawmakers have taken this seriously, and House Bill 1718 would require insurers to tell homeowners at issuance or renewal that standard policies do not cover flood damage. If you have never seen a separate flood declarations page, you probably do not have flood coverage.
Building and Contents Limits Under American Bankers
For residential properties, NFIP policies through American Bankers generally offer up to $250,000 in building coverage and $100,000 in contents coverage. Commercial properties typically reach up to $500,000 for building and $500,000 for contents. Building and contents are separate coverages, so you choose each one on its own.
Building coverage generally applies to the structure itself and things built into it: the foundation, electrical and plumbing systems, furnace, water heater, built-in appliances, and permanently installed cabinets. Contents coverage is for your belongings, such as furniture, clothing, electronics, and portable appliances. Many buyers skip contents to keep the premium down, then realize after a flood that their couch, beds, and kids' clothes were not covered.
Basements deserve their own warning. NFIP coverage below the lowest elevated floor is typically limited to essentials like the furnace, water heater, washer, dryer, and electrical panel. Finished drywall, carpet, and the TV in a finished basement often are not covered. In older Pennsylvania homes with lived-in basements, that gap can be large.
If your home's replacement cost exceeds the NFIP limit, excess flood coverage may be worth discussing. We can talk through that option when we quote.
Comparison of Standard NFIP Coverage Limits
| Property Type | Building Limit (typical max) | Contents Limit (typical max) |
|---|---|---|
| Single-family home | $250,000 | $100,000 |
| 2-4 family residence | $250,000 | $100,000 |
| Residential condo unit | $250,000 | $100,000 |
| Commercial building | $500,000 | $500,000 |
| Basement items | Limited to listed essentials | Limited to listed items |
Your lender will usually set a minimum building amount, often tied to the loan balance or the maximum available. Contents is generally your call.
The Role of Elevation Certificates in Rating
An Elevation Certificate (EC) may be used to document the exact height of your lowest floor compared to the base flood elevation (BFE), and for certain zones that can affect your premium. A licensed surveyor or engineer typically completes it after measuring the property. The form records foundation type, lowest floor height, adjacent grade, machinery locations, and flood openings.
Under the NFIP's current rating approach, an EC is not always required. Still, it can help in some situations. If your lowest floor sits several feet above the BFE, the certificate may support a lower rate than the default assumptions would produce. If the house is below BFE, the EC simply confirms what you are dealing with.
Here is how we usually handle it:
- Ask the seller first. Many Pennsylvania homes in flood zones already have an EC on file from a previous sale or permit.
- Check with the municipality. Floodplain administrators sometimes keep copies.
- Quote both ways when possible. We can compare the rate with and without the certificate.
- Order one only if it helps. A survey costs money, so it should earn its keep.
Pennsylvania may soon make this easier for buyers. Proposed House Bill 1704 would require sellers to disclose a property's flood history and insurance requirements before closing, which would bring flood information to light earlier in the deal.
Getting Coverage Before Closing on a New Home
Lenders often require flood insurance to be active at the moment of closing, and MVP Insurance can coordinate with your title company so the policy is in force for the transfer. The timing rules here are friendlier than most buyers expect. The NFIP usually imposes a 30-day waiting period, but a 0-day exception applies when flood insurance is purchased in connection with making, increasing, or renewing a mortgage loan.
The catch is the paperwork. Homebuyers can typically get immediate flood coverage at closing if the application and premium payment are completed at or before the loan closing. Miss that window and you may be stuck with a waiting period, or a lender that refuses to fund.
A realistic timeline looks like this:
- As soon as you are under contract: Ask whether the property is in a flood zone and whether the seller has an EC or an existing policy.
- Two to three weeks before closing: Get your quote, confirm limits with your lender, and decide on contents coverage.
- One week before closing: Send the application and mortgagee clause details. We share the declarations or binder with the title company.
- Closing day: Premium is paid, often through escrow on the settlement statement, and coverage starts.
We have seen buyers try to sort this out the day before closing. It sometimes works, but it is stressful for everyone at the table.
How to Get an American Bankers Quote
The fastest way to start an American Bankers flood quote is to call our Zelienople office at (724) 453-1122 or our New Springfield office at (330) 707-9055. You can also request a quote online and we will follow up. Either way, a real person handles it.
Having a few things ready speeds this up considerably. Gather the property address, year built, square footage, foundation type (basement, crawlspace, slab, or elevated), number of floors, and whether the basement is finished. If you have an Elevation Certificate or a prior flood policy declarations page, send those too. For a purchase, include the lender's name, loan number if you have it, and your target closing date.
Once we have that, we run the NFIP rating and compare it against other flood options we have access to. Then we walk you through the numbers in plain language: what the building limit protects, what contents covers, where the basement gaps are, and what the deductible means for an actual claim. You decide from there. No pressure, no script.
Popular American Bankers Policies and Features
The main line MVP places with American Bankers is flood insurance. Depending on the property, that may include options suited to lower-risk properties outside high-hazard zones, or standard coverage for homes in Special Flood Hazard Areas like Zones A and AE.
A few features clients ask about most:
- Separate building and contents coverage, so you can tailor each one
- Deductible choices, which typically let you trade a higher deductible for a lower premium
- Increased Cost of Compliance coverage, which may help pay to bring a substantially damaged building up to local floodplain rules
- Policy assignment, which may allow a buyer to take over the seller's existing NFIP policy
- Lender-friendly documentation, since NFIP declarations are widely recognized
Lower-risk properties are worth a mention. Plenty of Pennsylvania flood claims come from outside mapped high-risk zones, often from flash flooding on small creeks or water running downhill after heavy storms. Owners in these areas often skip coverage because their lender does not require it. Premiums in moderate or low-risk zones are often modest compared to high-risk rates, which makes the coverage easier to justify.
More About American Bankers and MVP Insurance
MVP Insurance was founded in 2008 by Josh Medure and David Varrati, and we maintain a professional relationship with American Bankers to provide dependable flood solutions for our clients. American Bankers is one of many carriers we work with as an independent agent. We place the business; they issue and service the policy under NFIP rules.
That setup gives you something useful. If your flood needs change (you add a second building, finish the basement, or buy a rental in a different flood zone), we can review whether American Bankers still fits or whether another carrier on our list makes sense. Our flood partners also include Franklin Flood and NEXT for certain situations, and we pair flood coverage with homeowners policies from carriers like Erie, Westfield, and Liberty Mutual.
The state is pushing flood awareness too. Pennsylvania created a dedicated Flood Insurance Ombudsman within the Insurance Department to coordinate education among FEMA, PEMA, and local agents. That effort helps homeowners understand what agencies like ours do every day: explain the policy before the water shows up, not after.
Frequently Asked Questions About Pennsylvania Flood Insurance
Is American Bankers flood insurance the same as FEMA flood insurance? For NFIP policies, yes in substance. American Bankers writes and services the policy, but the coverage follows federal NFIP terms backed by FEMA.
Does my homeowners insurance cover flooding in Pennsylvania? Generally no. Flood damage from rising water typically needs a separate flood policy.
How long does it take for flood insurance to start? Usually 30 days. If you buy it in connection with a new, increased, or renewed mortgage loan, coverage can typically start at closing with no waiting period.
Do I need an elevation certificate to buy flood insurance? Not always. It may lower your premium in some zones, so it is often worth asking the seller or township if one already exists.
How much flood coverage can I get for my house? Residential NFIP policies generally go up to $250,000 for the building and $100,000 for contents.
Can I get flood insurance if I'm not in a flood zone? Yes. Coverage is available outside high-risk zones, and premiums there are often lower.
Start a Quote with a Local Pennsylvania Agent
Flood coverage is one of those things that feels optional right up until it is not. American Bankers gives Pennsylvania property owners access to NFIP flood policies with clear building and contents limits, and a well-timed application can have that protection active the moment you take the keys. The details that matter most are knowing your limits, understanding basement gaps, using an Elevation Certificate when it helps, and getting the paperwork done before closing.
If you have a storm season ahead or a closing date on the calendar, now is the time to act. MVP Insurance, with offices in Zelienople, PA and New Springfield, OH, works with American Bankers as an independent agent and can compare your flood options in one conversation. Start your quotetoday and we will help you secure the property before the next heavy rain or settlement table.
MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

About the Author
Joshua Medure
Owner, MVP Insurance
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.