


Local Pennsylvania Foremost Insurance Agents

Owner, MVP Insurance

Coverage What It Protects Common Gap to Watch
Homeowners Dwelling, belongings, liability High wind/hail deductibles
Renters Belongings, liability, living costs Low liability limits
Auto Vehicle damage, injury liability State minimum limits only
Motorcycle Bike, gear, liability Custom parts excluded
Boat Hull, motor, liability on water Trailer or navigation limits
Umbrella Excess liability above other policies Underlying limits too low
Life Income replacement for family Only employer coverage

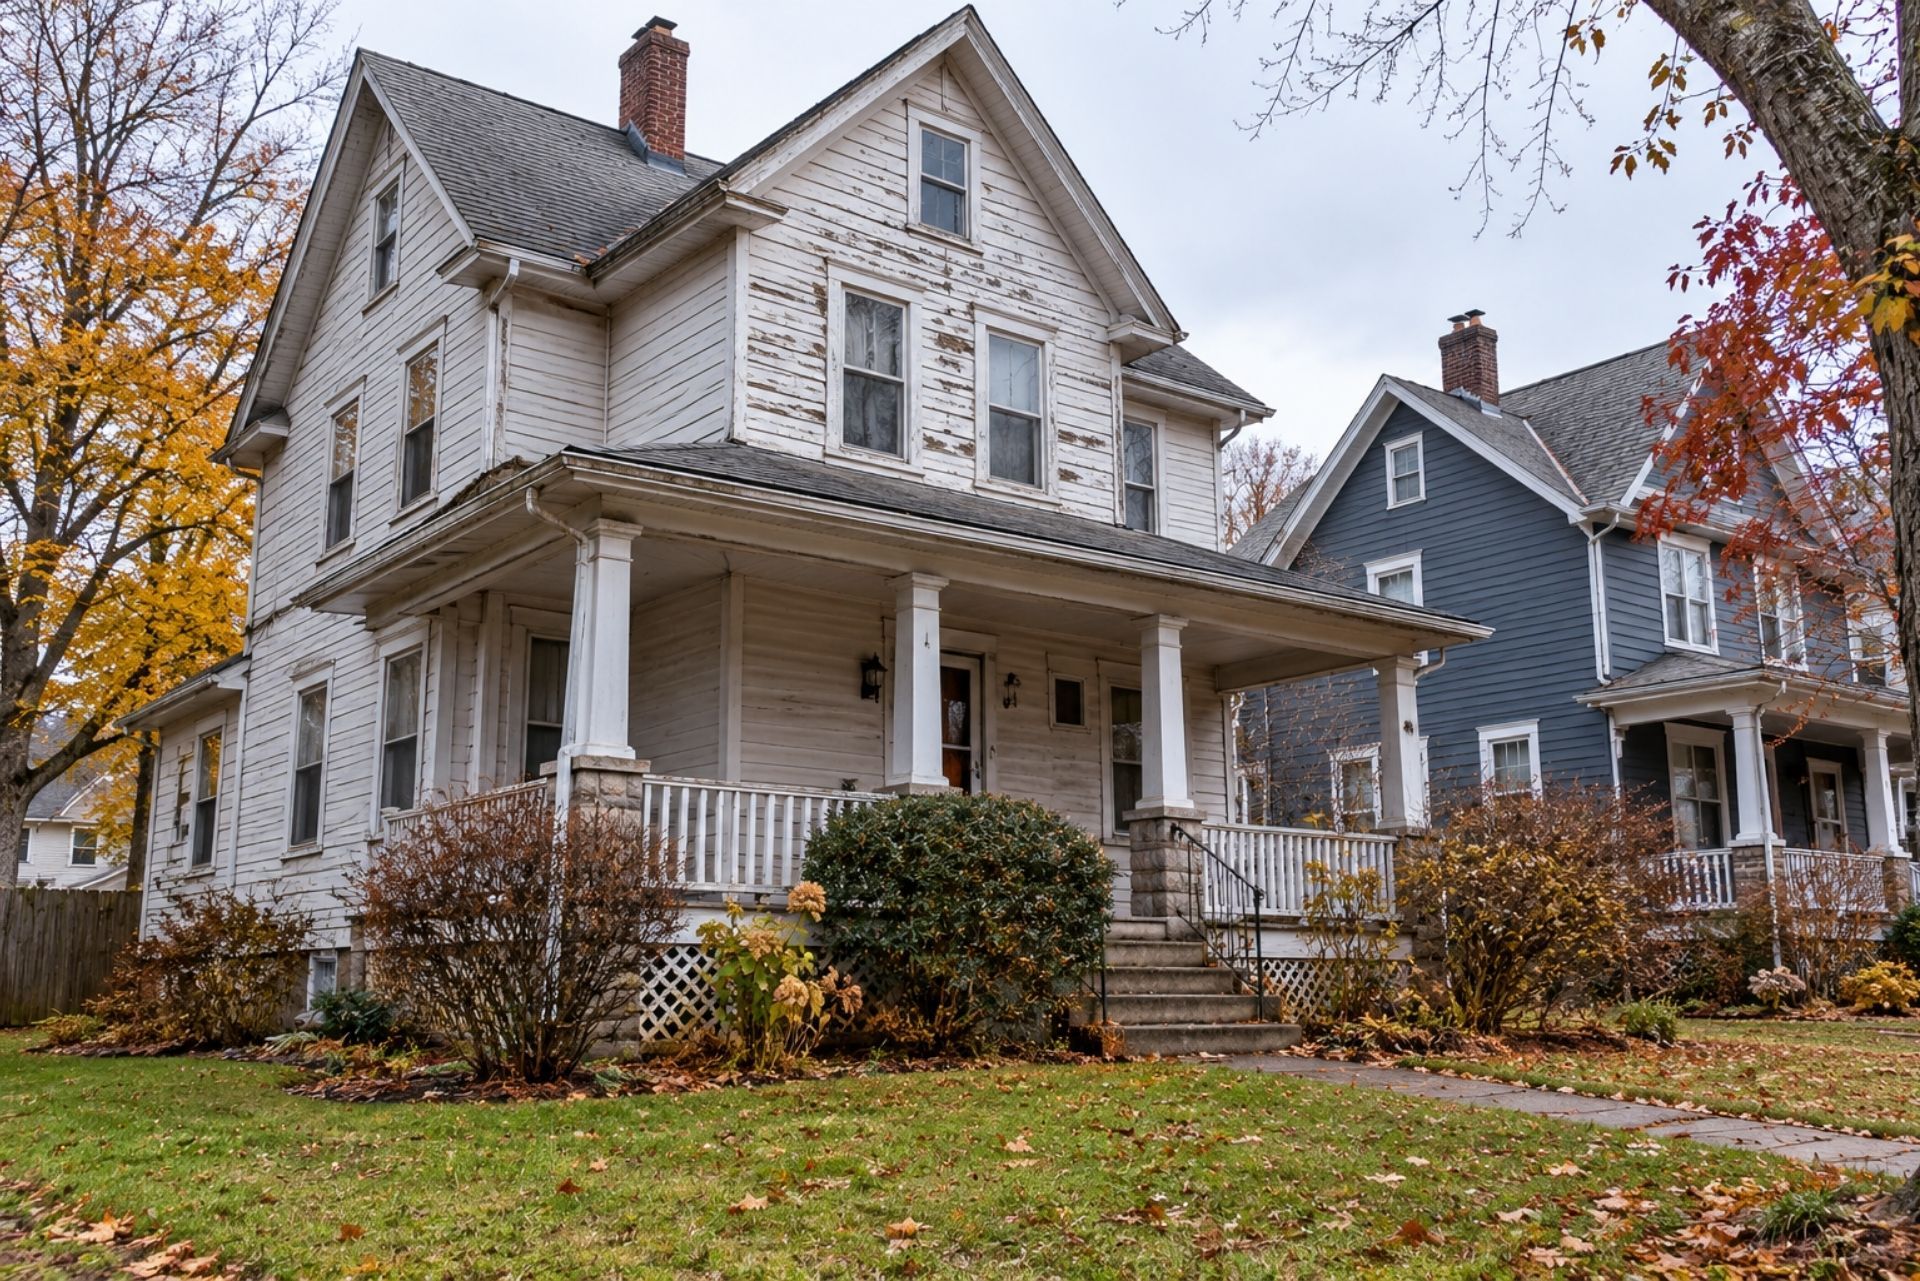
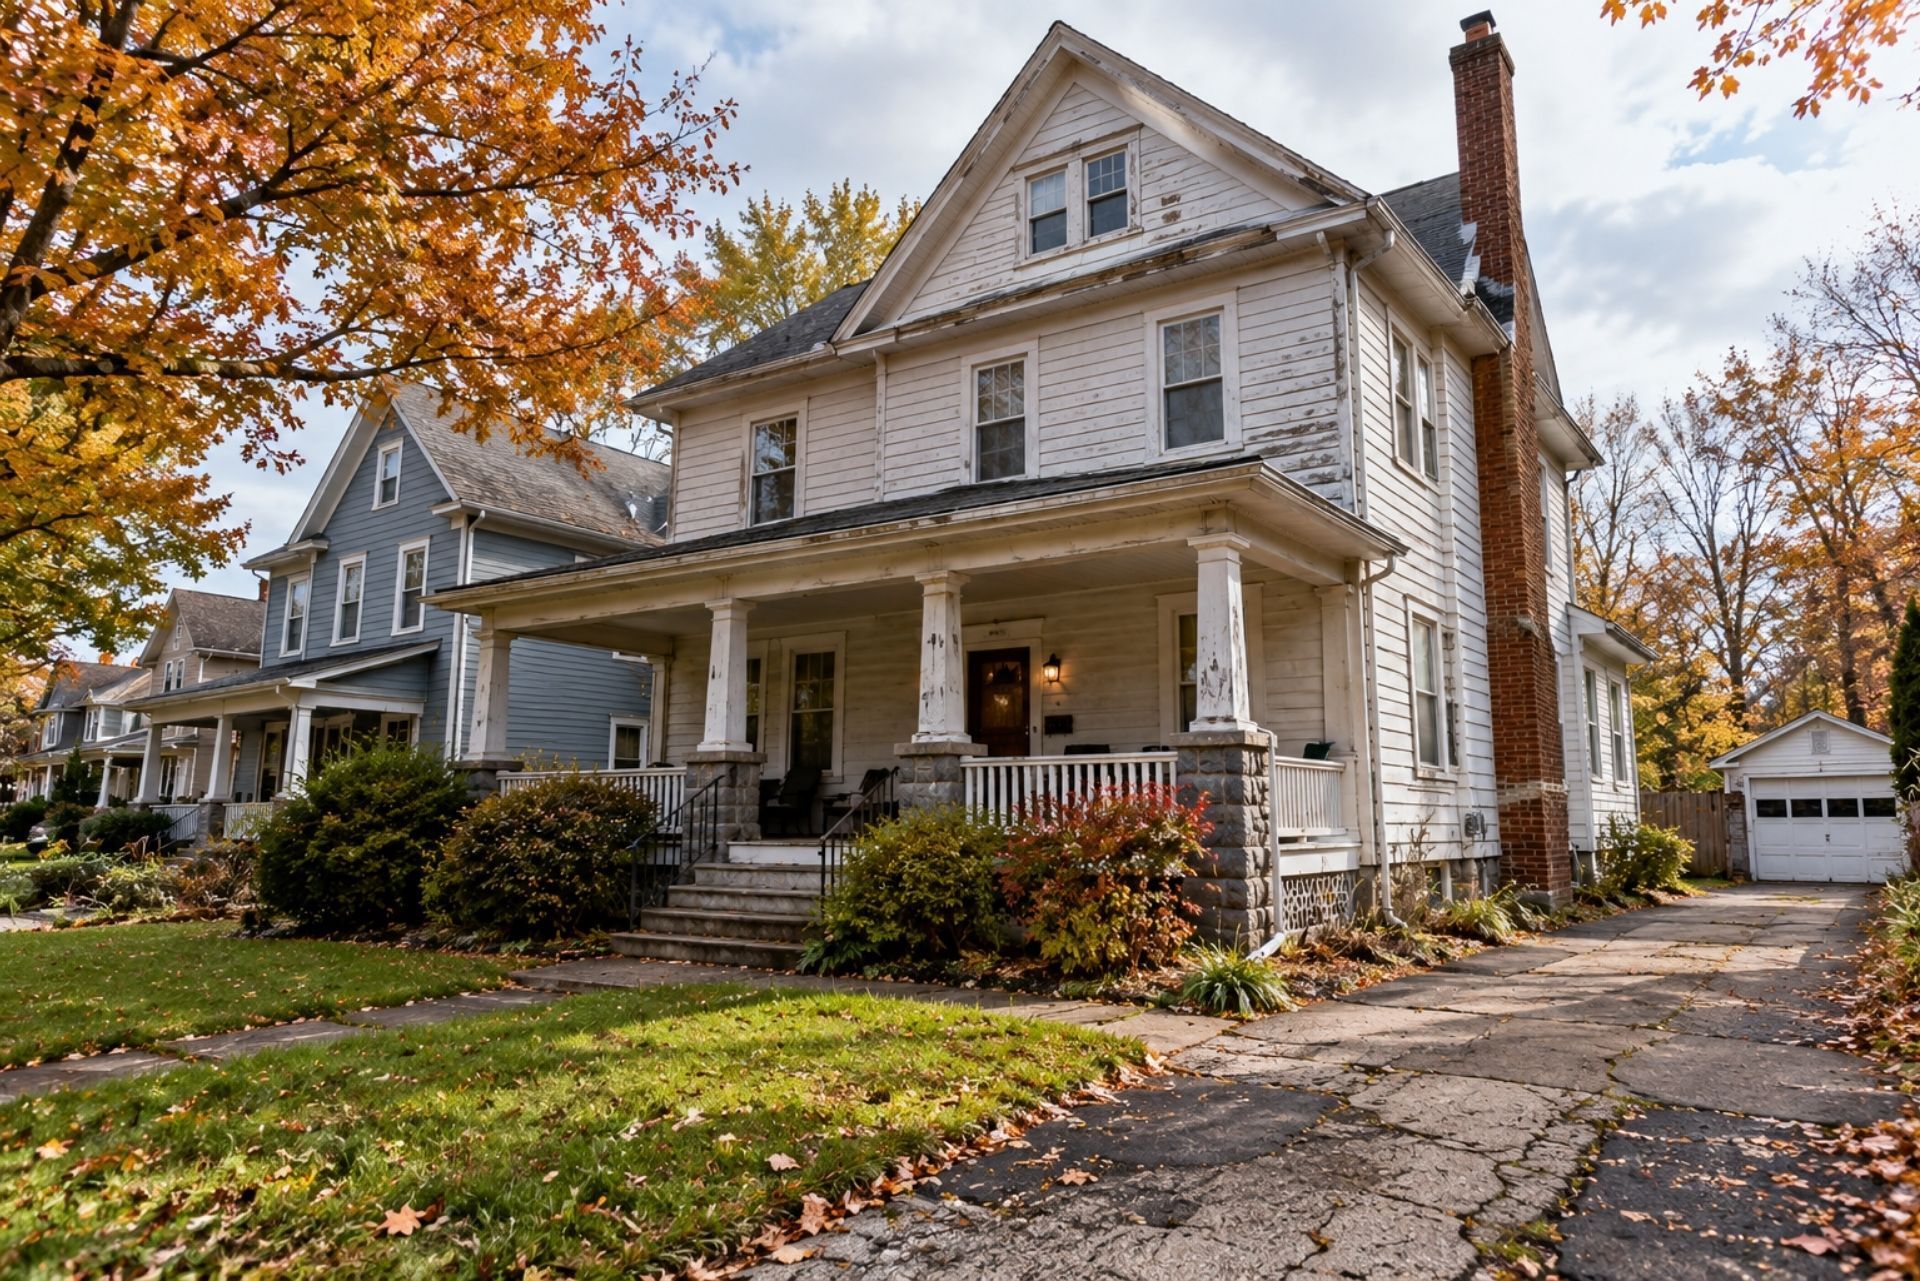
A home with a 25-year-old roof, a duplex you rent to students, or a driving record with a couple of tickets can make insurance shopping in Pennsylvania frustrating. Standard carriers often say no, and the internet sends you in circles. Local Pennsylvania Foremost insurance agents can place these risks with a carrier built for them, and a good agent explains why one policy fits better than another.

Looking for a Foremost Agent in Pennsylvania?

Local Pennsylvania Foremost insurance agents like MVP Insurance help homeowners and drivers get specialized coverage for properties or vehicles that standard carriers often decline. That includes older dwellings, rentals, vacant homes and higher-risk drivers. MVP is an independent agency that works with Foremost as one of several carriers, so you get a local agent who knows the product and can compare it against other options.


Founded in 2008 by Josh Medure and David Varrati, MVP has a Pennsylvania office in Zelienople and an Ohio office in New Springfield. The lines MVP places with Foremost are auto, home and flood. If a standard company has turned you down or quoted a premium that made no sense, this is usually the right next call.

David Varrati

By: Joshua Medure

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Why People Look for a Foremost Agent

Most people end up searching for Foremost after a standard carrier like Erie or Westfield passes on them. The usual reasons are the age of the home, the condition of the property or the applicant's loss history. Foremost focuses on the non-standard market, which is where those "no" answers end up.


Here are situations we see often in western Pennsylvania:


  • The 1920s farmhouse with knob-and-tube remnants or an older roof that a standard underwriter won't touch
  • The inherited house sitting empty while the family decides whether to sell or rent it
  • The small landlord with one or two rental units who doesn't fit a commercial program
  • The driver with a lapse in coverage, an at-fault accident or a young operator on the policy
  • The property near a creek where flood is a real concern but the buyer wants alternatives to the federal program


A common mistake is assuming the first decline means the house is uninsurable. It usually just means it needs a different kind of carrier.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

PCompleted operations coverage protects your business after the job is done and your crew has left the site. Without it, a claim from a furnace you installed in March might not be covered when the damage shows up in November. For HVAC work, delayed problems are common, not rare.


Consider how HVAC failures actually play out. A condensate line you routed slowly backs up and rots a subfloor over eight months. A refrigerant line set you brazed develops a pinhole leak that eventually floods a finished basement through the air handler pan. A gas connection holds for a season, then loosens with thermal cycling. In each case, the homeowner's claim arrives long after your invoice was paid.


Most commercial general liability policies include a products-completed operations aggregate, which is a separate pool of money for these after-the-fact claims. The detail people overlook is that the limit can be lower than you assume, or reduced by endorsement on some low-priced policies. If you install equipment for a living, that aggregate deserves as much attention as your per-occurrence limit.


Timing matters in the legal system too. Pennsylvania courts enforce deadlines strictly. The state Supreme Court recently upheld a firm one-year cutoff for lawsuits arising from home inspection reports, for example. That deadline applies to inspectors, not HVAC contractors. Construction-defect claims follow their own, often much longer, timelines, which is why keeping completed operations coverage in force year after year matters.


Contract disputes can also run alongside liability claims. The Superior Court broadened what counts as "performance" under CASPA, so contractors can sometimes recover interest and fees even when an owner's breach stopped the work. That's a payment issue, not an insurance one, but it's a good reason to keep clean job records, which also help when a completed operations claim comes in.

Foremost Auto, Home and Flood Coverage for Homes Standard Carriers Pass On

Foremost offers flexible auto, home and flood policies designed for situations that typically fall outside the guidelines of traditional companies like Liberty Mutual or Progressive. Foremost generally writes specialty coverage for dwellings valued from $5,000 to $1,000,000, with a focus on non-standard risks such as mobile homes and older rental properties.


On the auto side, Foremost may offer coverage for drivers who need a second chance, along with policy options that can work for households a standard carrier would surcharge heavily. Pennsylvania drivers still need to meet state minimum requirements and choose between limited and full tort, and an agent can walk you through that choice before binding anything.

Coverage for Older and Rental Dwellings

Older homes are where Foremost tends to stand out. Some policies may include an Agreed Loss Settlement provision for older homes, which typically pays the full insurance amount listed on the policy if the home is a total loss. That matters because rebuilding a plaster-and-lath house to modern code can cost far more than its market value, and owners often argue with adjusters over that gap after a fire.


Rentals are a core focus too. Foremost positions itself as a landlord and rental property insurance specialist for both single-unit owners and professional landlords with larger portfolios. Landlord policies may cover the structure, loss of rental income and liability, but they generally do not cover the tenant's belongings. Tenants still need their own renters policy.

Specialized Flood Insurance Options

Standard homeowners policies typically exclude flood, and Pennsylvania has plenty of river towns and low-lying neighborhoods where that exclusion hurts. Private flood has become a real alternative. Some Pennsylvania homebuyers have seen private quotes at a median of 54% below NFIP prices,though results vary by property and elevation.


The state has also backed this market. Pennsylvania Insurance Commissioner Michael Humphreys has described private flood insurance as a "strong, reliable, and affordable" alternative to the NFIP,particularly during federal program lapses. Our Pennsylvania flood insurance pagecovers more on how private and federal options compare.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Why Work With MVP Instead of Going Direct

Working with MVP instead of going direct gives you a local agent who can compare Foremost quotes with other specialty carriers, so the policy actually fits your Pennsylvania property. A direct channel can only offer its own product. An independent agent can tell you when Foremost is the right answer and when it isn't.


For a vacant home, an older dwelling or a rental, MVP may compare Foremost with American Modern. For a collector car, Hagerty or J.C. Taylor might be the better fit. For flood, Franklin Flood, American Bankers or NEXT may come into the picture. You can see the full roster on our carriers page.


MVP works for you, not the carrier, so the goal is the right coverage at a fair price rather than pushing one company. The agency also uses modern tools to make policy changes and documents easier to manage, and claims support is available 24/7 when something goes wrong at 2 a.m.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Popular Foremost Policies and Comparison

Popular Foremost policies in Pennsylvania include specialty homeowners insurance, landlord dwelling fire policies and non-standard auto coverage for drivers with unique needs. The right one depends on who lives in the property and how it's used.

Policy Type Typically Fits Features That May Be Available Watch For
Specialty Homeowners Older or unique owner-occupied homes Agreed Loss Settlement, dwelling and liability coverage Roof age and wiring questions
Landlord / Dwelling Fire Single rentals or small portfolios Structure, lost rent, landlord liability Tenant belongings not covered
Vacant Dwelling Inherited or between-tenant homes Switch to rental usage when occupied Vacancy limits on theft and vandalism
Non-Standard Auto Drivers with lapses, tickets or accidents PA minimums up to higher limits Tort selection and SR-22 needs
Flood Homes in or near flood zones Building and contents options Waiting periods before coverage starts

The vacant-to-rental row trips up a lot of owners. If a house sits empty longer than the policy allows, a theft or burst-pipe claim may be limited or denied. Telling your agent the moment a tenant moves in, or moves out, avoids that problem.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

How an Agent Places It and How to Get a Foremost Quote

To get a quote, an MVP agent collects your property or vehicle details and submits them through the Foremost platform to find the specific program that accepts your risk profile. Through the ForemostSTAR system, independent agents can quote specialty business and move policies between "Vacant" and "Rental" usage types as a property's status changes.


Here's how the process usually goes:


  1. Gather the basics. Year built, square footage, roof age, heating type, electrical and plumbing updates, and occupancy. For auto, driver licenses, VINs and recent claims or violations.
  2. Disclose the honest picture. Prior losses, vacancies and tenant situations. Surprises at claim time cost far more than a slightly higher premium.
  3. Agent submits and matches the program. Foremost has different programs for different risks, and the agent places you in the one that fits.
  4. Compare side by side. MVP may run the same risk with other specialty carriers so you see real choices.
  5. Review and bind. Go over deductibles, loss settlement terms and exclusions before you sign.


Photos of the roof, electrical panel and furnace often speed things up considerably.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

More About Foremost and MVP Insurance

Foremost is a member of the Farmers Insurance Group, and MVP Insurance is an independent agency authorized to place business with them alongside carriers like Frederick Mutual and Municipal Mutual. MVP is not Foremost. MVP is a separate agency that represents you and can place your policy with Foremost when it's the right fit.


The financial picture behind Foremost is solid. AM Best affirmed an "A" (Excellent) Financial Strength Rating for Farmers Insurance Group, including Foremost, in 2026 with a positive outlook. S&P Global Ratings also raised the group's rating to "AA-" in June 2026 after statutory capital grew to $11.5 billion.


MVP serves Pennsylvania from its Zelienople office and Ohio from New Springfield, so clients on both sides of the state line work with the same team.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Frequently Asked Questions About Pennsylvania Specialty Insurance

Is Foremost a real insurance company or just a program? Foremost is a real insurance company and part of the Farmers Insurance Group. You buy it through agents like MVP, which works with Foremost as an independent agency.


Can I insure a house with an old roof in Pennsylvania? Often, yes. Foremost and similar specialty carriers may accept older roofs that standard companies decline, though the roof's condition can affect price and settlement terms.


Does landlord insurance cover my tenant's stuff? No. A landlord policy typically covers the building and your liability, so tenants need their own renters policy for their belongings.


Do I need flood insurance if I'm not in a flood zone? It's not required, but flooding happens outside mapped zones too. A homeowners policy generally excludes flood, so separate coverage is the only way to protect against it.


What happens if my rental sits empty? Many policies limit coverage after a property is vacant for a set period. Tell your agent right away so the policy can be switched to vacant coverage.


Will a specialty policy cost more than a standard one? Sometimes, because the risk is different. Comparing several specialty carriers through one agent is the simplest way to keep the price reasonable.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Start a Quote with Your Local Pennsylvania Foremost Insurance Agents

An older home, a rental or a driving record with a few marks shouldn't leave you without solid coverage. Foremost was built for exactly those cases, and an independent agent who compares it with other specialty carriers gives you a clear view of your options before you commit to anything.


MVP Insurance handles auto, home and flood placements with Foremost from two local offices:


  • Zelienople, PA:108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122
  • New Springfield, OH: 13823 Grant St, New Springfield, OH 44443, (330) 707-9055


Have your property or vehicle details handy and start your quoteonline, or call the office closest to you. An agent will match your risk to the right program and walk you through the differences in plain language. MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

Joshua Medure

Owner, MVP Insurance


I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania







