


Ohio Motorcycle Insurance

Owner, MVP Insurance

Ohio motorcycle insurance starts with state-required liability coverage, but a smart policy goes further. Riders under 18 and novice riders in their first year generally must wear helmets, and add-ons like medical payments, custom parts coverage, and lay-up coverage for winter storage fill gaps that a bare-minimum policy leaves wide open.


Most riders in the Mahoning Valley and across northeast Ohio buy their first motorcycle policy the same way: they call whoever insures their car, ask for "the legal stuff," and hang up. That works right up until a deer runs out on Route 7 or someone backs into your parked bike outside a diner in Canfield. Then the questions start. Who pays for your ER visit? What about the custom exhaust and the custom paint job? Why are you still paying full premiums in January when the bike hasn't moved since Halloween?


The good news is that motorcycle coverage is flexible once you understand the pieces. Some parts are required by Ohio law. Others are optional but solve very specific problems riders run into every season. This guide walks through each piece in plain language, so you can build a policy that fits how you actually ride.

Ohio Motorcycle Insurance Requirements and Liability Limits

Ohio requires every motorcycle operator to carry liability insurance that meets the state's financial responsibility minimums. Liability pays for injuries and property damage you cause to other people. It does not pay to fix your own bike or treat your own injuries, which surprises a lot of first-time riders.


The required coverage has three parts: bodily injury per person, bodily injury per accident, and property damage. The state sets a floor for each, and those minimums are generally the same ones that apply to cars in Ohio. As of this writing, those floors are modest compared to the cost of a serious crash, so many riders choose higher limits to protect their savings and home. A single hospital stay for an injured passenger can blow past state minimums quickly.


You also need to carry proof. Riders must show proof of insurance at traffic stops, accident scenes, and vehicle inspections, and riding without it can lead to license suspension. Keep a digital ID card on your phone and a paper copy under the seat.


If you also need coverage for your home or other vehicles, our Ohio personal insurance options and Ohio car insurance pageexplain how bundling works. MVP Insurance serves riders from offices in Zelienople, PA and New Springfield, OH.

David Varrati

By: David Varrati

Owner, MVP Insurance


MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Umbrella

An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.

Coverage PA Minimum Common Recommendation
Auto bodily injury $15,000 / $30,000 $250,000 / $500,000
Auto property damage $5,000 $100,000
Medical benefits (auto) $5,000 $10,000 or more
Home personal liability None required $300,000 to $500,000
Umbrella None required $1 million or more

Ohio Helmet Rules for Novice and Young Riders

Ohio does not require every adult rider to wear a helmet, but the law generally does require one for riders under 18 and novice riders during their first year of licensure. Under ORC § 4511.53, any operator or passenger under 18 must wear a protective helmet with the chin strap fastened. The novice designation applies to anyone who has not been licensed to operate a motorcycle for more than one year.


A few details trip people up:


  • Permit riders: Anyone on a Temporary Instruction Permit is required by law to wear a helmet, regardless of age.
  • Passengers: If the operator must wear a helmet because of age or novice status, any passenger they carry must wear one too.
  • Helmet standard: Required helmets must meet FMVSS 218, which means DOT-approved. Novelty "beanie" helmets without that certification don't count.

For new riders, Motorcycle Ohio safety courses are one of the most useful resources available. The state-run program offers training for beginners and experienced riders alike, and completing a course builds real skills for braking, cornering, and emergency maneuvers. Some insurers may also factor safety course completion into pricing, so keep your certificate handy when you request a quote.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

Where you live

Your ZIP code sets the base for both home and auto: weather patterns, repair costs, traffic density and local claim history all feed into it. Distance to a fire station and hydrant matters for the home policy.

Where you live

Coverage Ohio Minimum Suggested for Cross-Border Commuters
Bodily injury (per person) $25,000 $100,000 or more
Bodily injury (per accident) $50,000 $300,000 or more
Property damage $25,000 $100,000
Uninsured/underinsured motorist Optional Match your liability limits
Medical payments Optional Worth adding for PA trips
Umbrella policy Not required Consider if you own a home

Medical Payments and Custom Parts Coverage

Medical payments coverage pays for your injuries no matter who caused the crash, while custom parts coverage protects the money you've put into upgrading your bike. Both are optional in Ohio, and both address gaps that standard liability leaves behind.

Medical Payments (MedPay)

MedPay is no-fault coverage that pays medical bills for you and your passenger regardless of who was at fault. Ohio insurers typically offer limits from $500 to $10,000. It helps most when your health plan carries a high deductible or excludes motorcycle injuries, which some do. Picture a low-speed slide on gravel: no other driver to blame, a broken wrist, and a $3,000 deductible. MedPay can cover that out-of-pocket hit quickly. One caution: riders need a dedicated motorcycle policy or a specific endorsement to receive these benefits, because standard auto policies often exclude them.

Custom Parts and Equipment

Standard comprehensive and collision coverage usually pays for factory equipment only, often with a small allowance for extras. Chrome, custom paint, aftermarket seats, saddlebags, upgraded exhaust, and premium lighting can push well past that allowance. Custom parts coverage raises the limit so those additions are covered after a theft or crash. Save receipts and photos of every upgrade. The most common claim headache we see is a rider who can't prove what a custom part cost.


Parts used in repairs are also getting legislative attention. Ohio House Bill 636, which addresses transparency around OEM versus aftermarket repair parts, remains under committee review as of October 2026.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Life Insurance

Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.

Lay-Up Coverage for Winter Storage

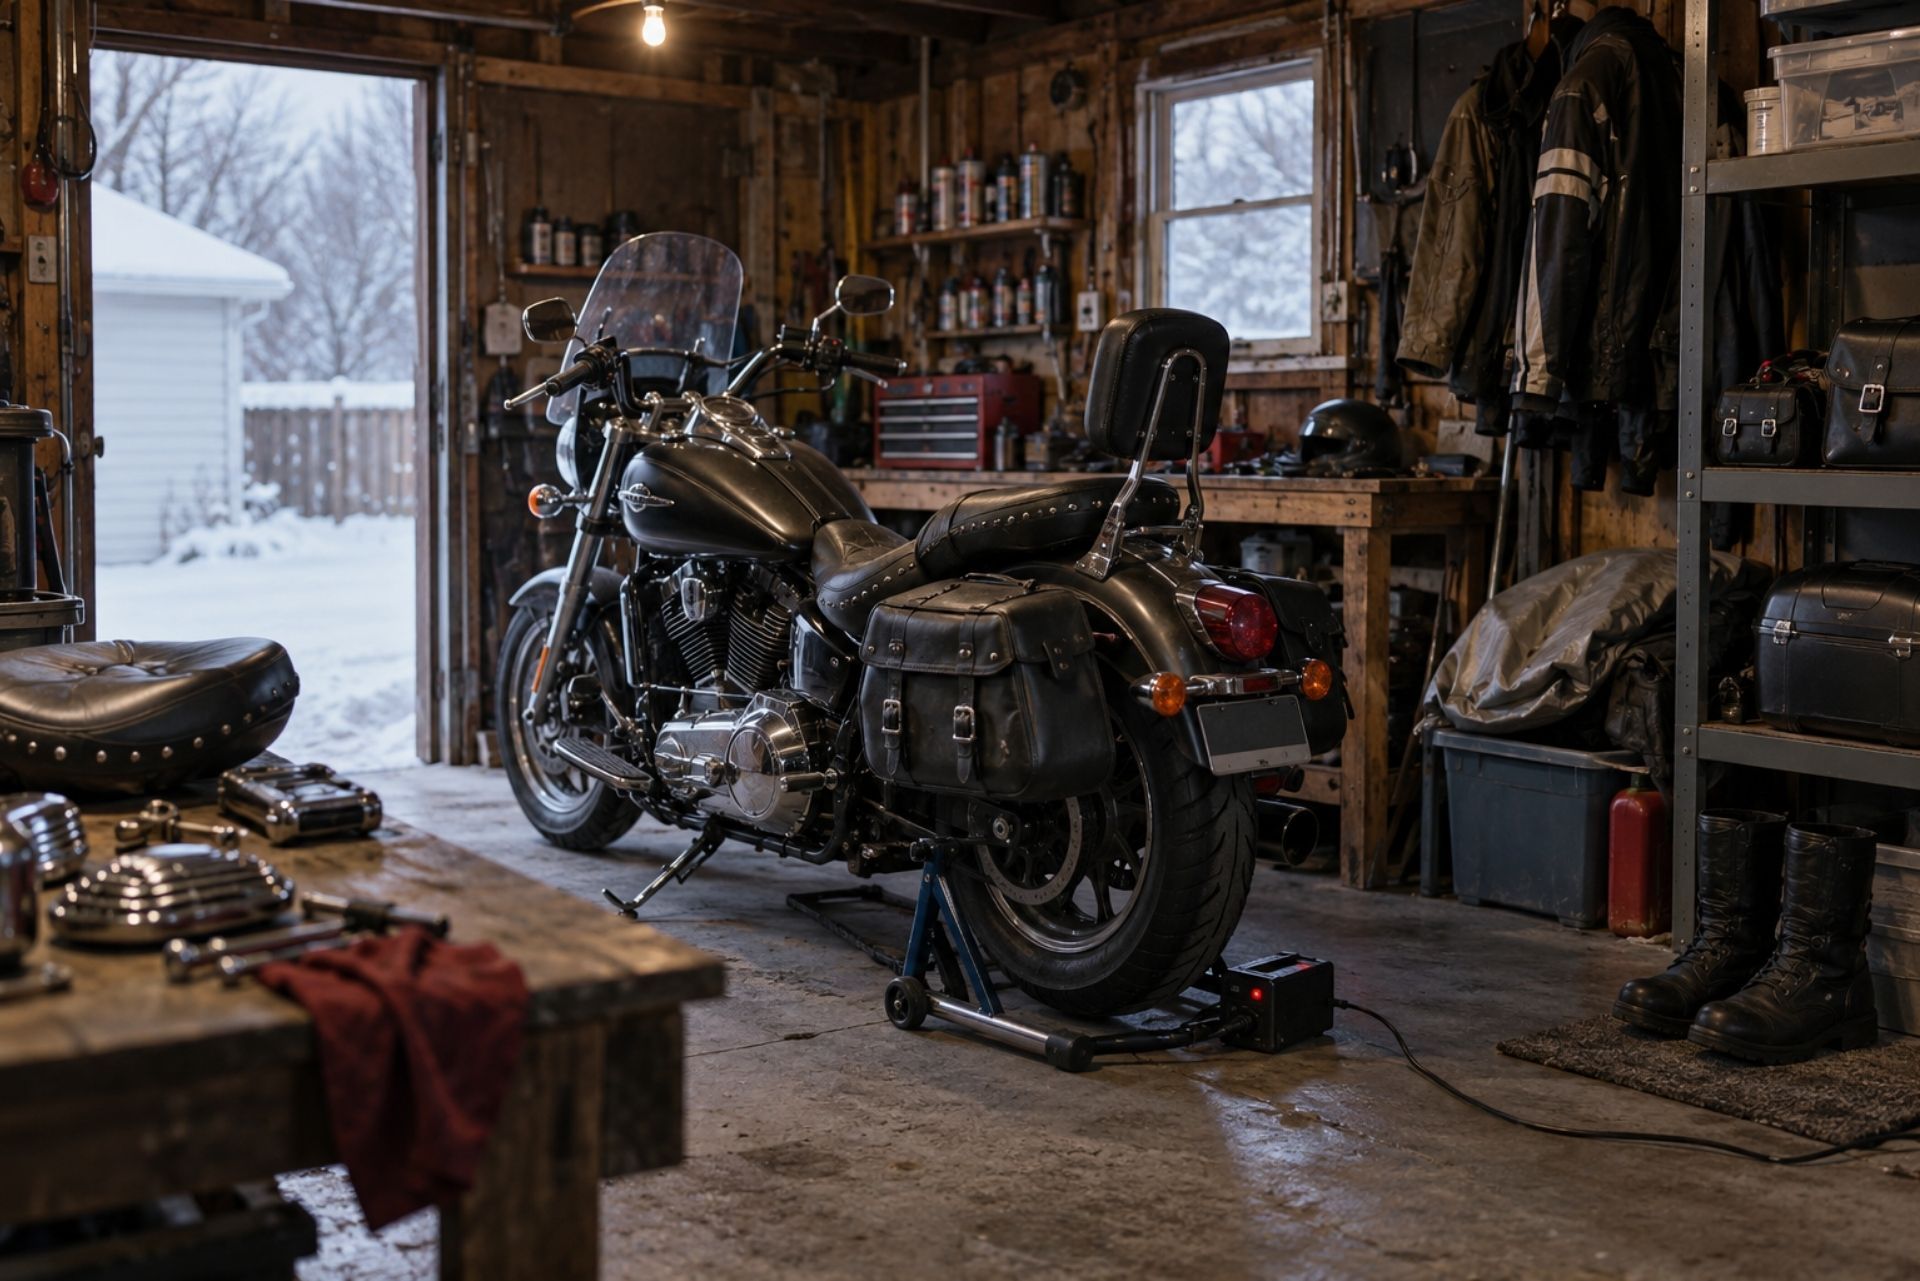
Lay-up coverage lets you keep comprehensive protection on your motorcycle during the off-season while pausing liability and collision, which lowers your premium for the months the bike sits in storage. For Ohio riders who park the bike from roughly November through March, that can add up to real savings.


Here's why you don't want to cancel the policy entirely. A garaged bike can still be stolen, catch fire, get crushed when a shelf collapses, or suffer damage from a burst pipe or flood. Comprehensive covers those risks. Dropping all coverage also creates a lapse in your insurance history, which can affect your rates when you reinstate in spring.


A few practical tips for using lay-up well:


  1. Set a clear restart date before riding season. The biggest mistake is taking the bike out on a warm February afternoon while liability is still paused, which means riding uninsured.
  2. Confirm your storage location with your agent, especially if the bike lives in a rented unit or a friend's barn.
  3. Keep custom parts coverage active if it's attached to comprehensive.


Not every carrier handles lay-up the same way. Some build seasonal adjustments into the policy automatically, while others need you to request the change. An independent agent can tell you how each option works before you commit.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Replacement Cost Rebuilds vs Actual Cash Value

Comparing Ohio Motorcycle Coverage Options

Most carriers offer the same core coverages, but they differ in limits, endorsements, and how they treat seasonal riding and customized bikes. MVP Insurance works with each carrier below as an independent agent, so we can compare them side by side for you.

Coverage Erie Westfield Progressive Hagerty
Liability Available Available Available Available
Medical Payments Typically offered Typically offered Typically offered Ask about options
Comprehensive Available Available Available Available
Custom Parts Endorsement options Endorsement options Endorsement options Often built for collector bikes
Seasonal / Lay-Up Ask your agent Ask your agent Ask your agent Ask your agent
Ideal fit Riders bundling home and auto Local, service-focused coverage Everyday and newer riders Vintage and collector motorcycles

The right carrier depends on your bike, your riding habits, and what else you insure. A rider with a 1970s Triumph that comes out for summer shows has different needs than someone commuting on a new sport bike. We generally recommend comparing at least a few options rather than defaulting to whoever covers your car.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

The Role of Umbrella and Life Insurance in a Comprehensive Plan

Life Insurance

Life coverage keeps a mortgage paid, funds college plans and gives a surviving spouse time to adjust. Term policies cover a set period at a lower cost, while permanent policies build cash value. The most frequent mistake we see is relying only on a group policy through work, which usually ends when the job does.

Frequently Asked Questions About Ohio Motorcycle Insurance

Do I need motorcycle insurance in Ohio if I only ride a few times a year? Yes. Ohio requires liability coverage any time the bike is ridden on public roads, no matter how often you ride.


Do adults have to wear helmets in Ohio? Generally, no. Helmets are required for riders under 18, novice riders in their first year, permit holders, and passengers of riders who must wear one.


Does my health insurance cover motorcycle crash injuries? Sometimes, but high deductibles and exclusions are common. MedPay helps cover what your health plan doesn't.


Can I stop paying for insurance over the winter? You can usually reduce coverage with a lay-up option instead of canceling. That keeps theft and fire protection in place and avoids a gap in coverage.


Is my aftermarket exhaust covered automatically? Usually only up to a small limit. Add custom parts coverage if you've invested much in upgrades.


Will a safety course lower my rate? It may, depending on the carrier. Mention your Motorcycle Ohio course completion when you request a quote.

Written By

David Varrati

Owner, MVP Insurance


Owner, MVP Insurance

On this page

04

Review, bind, and relax

Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.

Choosing the Right Policy with MVP Insurance

The right motorcycle policy covers what Ohio requires, follows the helmet rules for new and young riders, and adds the pieces that matter for your bike: MedPay, custom parts, and lay-up coverage for winter. Getting that mix right is easier with someone who shops multiple carriers on your behalf.


MVP Insurance was founded in 2008 by Josh Medure and David Varrati, and the agency works for riders, not insurance companies. That independence means we compare coverage from carriers like Erie, Westfield, Progressive, and Hagerty to find the fit for your riding season. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293.


Ready to see your options before the next riding season? Start your quote online, or call our Zelienople office at (724) 453-1122 or our New Springfield office at (330) 707-9055. We'll handle the comparison work so you can spend more time on the road.

MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.

We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.

Our Owners

Two friends who started an agency

Owner

Joshua Medure

I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


Connect on LinkedIn

About the Author

David Varrati

Owner, MVP Insurance


I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.

Personal Insurance in Ohio & Pennsylvania

Coverage for your home, your car, and your family

Protect the everyday things that mean the most to you.

Homeowners Insurance

Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.

Car Insurance

We proactively shop the market to find the best combination of coverage and price for every car in your driveway.

Renters Insurance

Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.

Umbrella Insurance

Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.

Life Insurance

Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.

Flood Insurance

Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.

Business Insurance in Ohio & Pennsylvania

No matter how big or small your business, we protect it

Practical coverage for your people, your property, and the work you do.

Industries We Serve

Insurance built around the work you do

Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance

General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance

Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance

Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.

5-Star Rated on Google

What our clients say

Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.

Contractors & Tradesmen

General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.

Explore More

Insurance Tips & News

Insurance tips for Ohio and Pennsylvania families and businesses

Practical ideas for protecting what matters to you.

How to File an Insurance Complaint in Pennsylvania: What the Insurance Department Handles, How to
24 October 2026
How to File an Insurance Complaint in Pennsylvania. What Pennsylvania households should know, explained in plain English by a local independent agent.

Pennsylvania Insurance Guaranty Association Explained: What Happens When an Insurer Fails, Claim
24 October 2026
Pennsylvania Insurance Guaranty Association Explained. What Pennsylvania homeowners should know, explained in plain English by a local independent agent.

Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules: Notice Periods, Allowed Reasons Under
24 October 2026
Pennsylvania Auto Insurance Cancellation and Nonrenewal Rules. What Pennsylvania drivers should know, in plain English.


Insurance Questions, Answered

Questions our clients ask

A little clarity can make your next step easier.

  • What does an independent insurance agency do?

    An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.

  • Can MVP Insurance quote both my home and auto?

    Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.

  • Do you insure businesses in Ohio and Pennsylvania?

    Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.

  • How do I import my current policy for a quote?

    Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.

  • How do I report a claim or make a payment?

    Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.

  • How often should I review my insurance?

    Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.

Covington office, Monday through Friday

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461

Request Your Free Quote

Let's make insurance simple for you

Tell us what you need. We will help you explore your options.

Call Pennsylvania








