

Every Pennsylvania driver chooses between limited tort and full tort, and that choice affects your right to sue after an accident. It is one of the most misunderstood checkboxes on the application.
With limited tort, you can still recover medical bills and lost wages from an at-fault driver. What you give up is the right to sue for pain and suffering unless your injury meets the state's definition of a serious injury. Limited tort usually costs less, which is why many people choose it without realizing what they waived.
Full tort lets you seek compensation for pain and suffering without meeting a specific injury threshold. That matters for injuries like whiplash, a broken wrist, or a concussion that heals but disrupts your life for months. These injuries often fall short of "serious" under limited tort rules.
A quick comparison:
- Limited tort: lower premium, pain and suffering claims only for serious injuries
- Full tort: higher premium, full right to sue for pain and suffering
- Who chooses it: the selection usually applies to everyone covered under your policy, including family members
If you aren't sure which one you picked, look at your declarations page. People are often surprised to find limited tort selected years ago by default.
| Coverage | What It Pays For | Typical PA Limit Example |
|---|---|---|
| Dwelling (A) | Rebuilding the house itself | $300,000 (full rebuild cost) |
| Other Structures (B) | Detached garage, fence, shed | 10% of dwelling: $30,000 |
| Personal Property (C) | Furniture, clothes, electronics | 50% to 70% of dwelling: $150,000 to $210,000 |
| Loss of Use (D) | Hotel and meals while displaced | 20% to 30% of dwelling: $60,000 to $90,000 |
| Personal Liability (E) | Injuries or damage you cause others | $300,000 to $500,000 |
| Medical Payments (F) | Minor guest injuries, regardless of fault | $1,000 to $5,000 |
Every carrier licensed in Pennsylvania must meet the same 15/30/5 liability and $5,000 first party benefit minimums, but they differ in how they price coverage, package options, and handle tort selection. That's why comparing carriers matters more than comparing the minimum itself.
Erie has deep roots in Pennsylvania and tends to bundle auto with home coverage in ways that appeal to families. Progressive offers a wide range of options and is often a fit for drivers with a varied record or those who want to adjust coverage online. Westfield, a regional carrier, works through independent agents and frequently fits households looking for solid auto and home packages. None is right for everyone. Your driving history, vehicle, zip code, and credit-based insurance factors all shift which carrier comes in more favorably.
MVP Insurance's independent agents work with carriers like Erie, Progressive, and Westfield to find policies that meet Pennsylvania's state mandates and fit your situation. As an independent agency, MVP works with these carriers on your behalf rather than acting as the carrier itself. That means one conversation can produce several quotes to compare side by side, including how each handles first party benefits, tort options, and higher liability limits.
A few things worth asking any agent when you review quotes:
- What does it cost to raise liability to 100/300/100 compared with the minimum?
- How much more is full tort on this policy?
- What would $25,000 in first party benefits add?
- Does the carrier offer uninsured and underinsured motorist coverage at matching limits?
That last question is important. Plenty of drivers on Pennsylvania roads carry only the minimum, or nothing at all. Uninsured and underinsured motorist coverage protects you when the other driver can't pay. For a deeper look at coverage options across the state, see our guide to pennsylvania car insurance.
Meeting the state's minimum car insurance requirements is the starting line, not the finish. Liability at 15/30/5, $5,000 in medical benefits, a current ID card, and no lapses will keep you legal. Whether that is enough protection is a separate question, and for most households with a home, savings, or a steady paycheck, the answer is no.
If you'd like a second set of eyes on your current policy or want to compare options from several carriers at once, you can start your quote here with MVP Insurance. The team has offices in Zelienople, PA and New Springfield, OH, and serves drivers across both states. MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
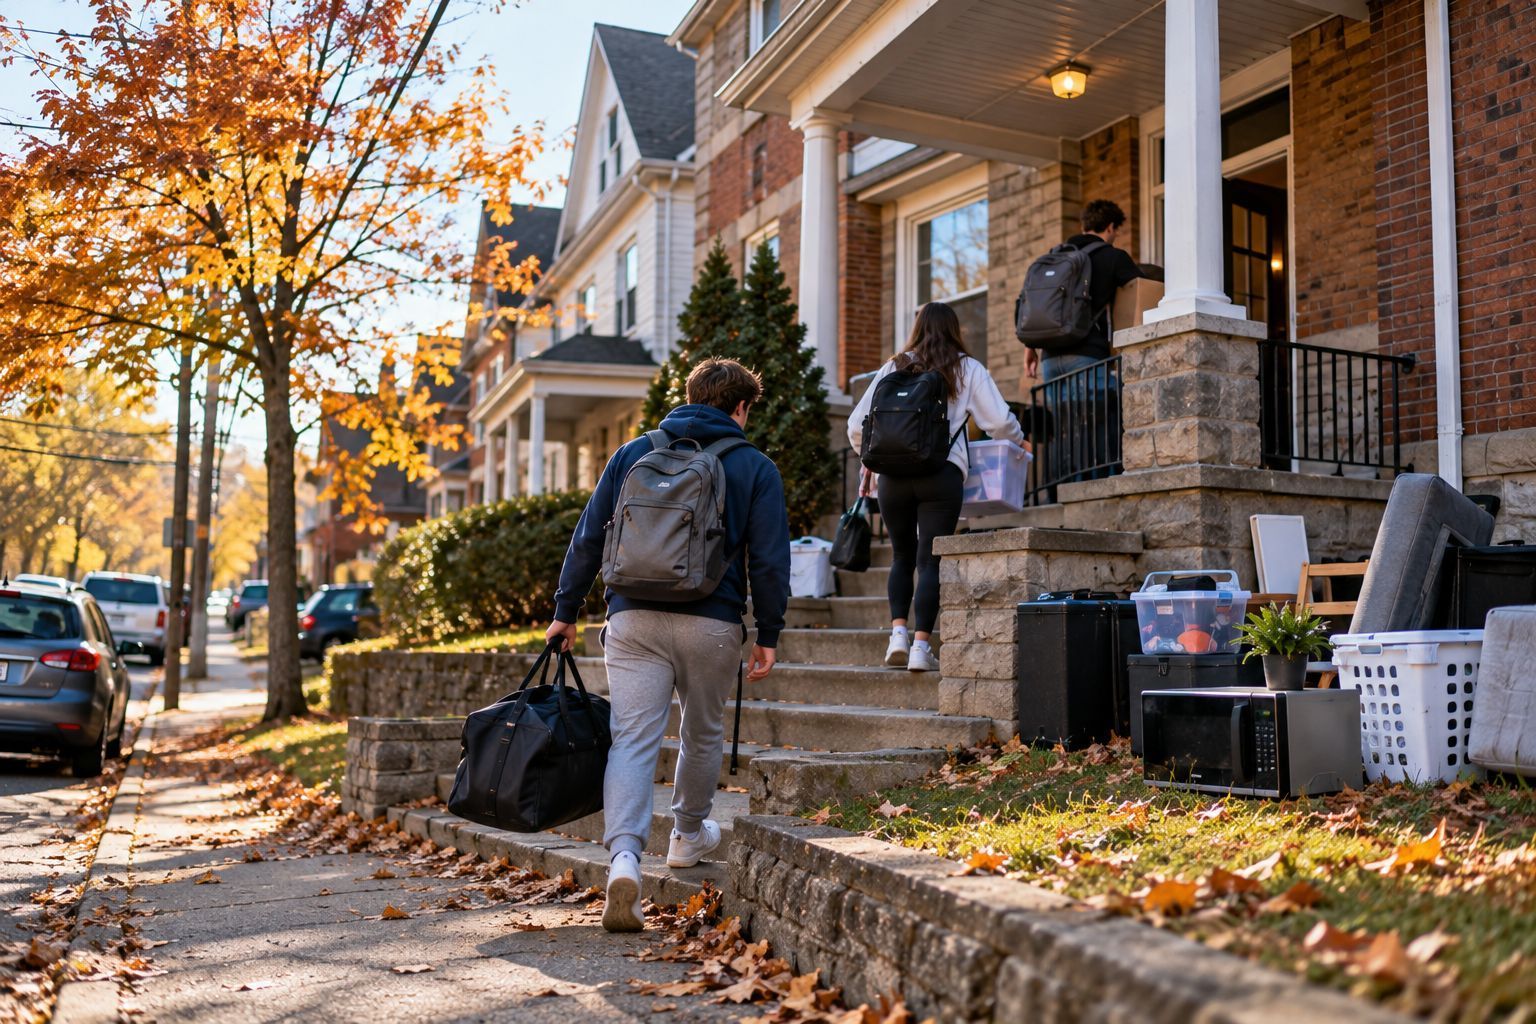
Renting to college students in Pennsylvania can be steady, profitable work, but it takes the right coverage. Student tenants bring constant demand and constant turnover, along with liability and fire exposures most single-family landlords never face. Before you sign the next group of sophomores to a twelve-month lease, it helps to know where the real risks sit and how insurance handles them.
Renting to College Students in Pennsylvania: Risks and Rewards
Renting to students in PA calls for specific pennsylvania landlord insurance built for high turnover and elevated liability. Student housing almost never sits empty, which is the upside. The tradeoff is real exposure to social host liability claims, guest injuries and a higher chance of fire than a typical long-term family rental.
The reward side is simple math. A four-bedroom house near campus, leased by the room, often brings in more than the same house rented to one family. Demand renews every fall, and many landlords fill units months before move-in.
The risk side is where owners get surprised. A standard homeowners policy does not cover a house you rent out, and a basic dwelling fire policy may not include liability at all. Many landlords also skip local compliance details, which can come back to bite them. Pennsylvania courts have made clear that landlords must follow local safety ordinances strictly, and in one 2026 case, the court held that failing to provide a lead-safe certificate can void a landlord's right to collect rent or evict for non-payment. Paperwork is part of risk management too.
Managing Landlord Liability and Social Host Risks
Pennsylvania landlords can be held liable for injuries on their property when a dangerous condition they knew about, or should have known about, contributed to the harm. With student rentals, the conditions that get people hurt tend to be the ones that show up at a party: a loose railing on a back deck, a broken stair tread, poor lighting on an exterior walkway. Add alcohol and a crowd of thirty, and a small maintenance issue becomes a lawsuit.
Social host scenarios are the specific worry. Pennsylvania law takes underage drinking seriously, and the person who serves alcohol to a minor faces the most direct exposure. But injured guests and their attorneys often name everyone connected to the property, including the owner. Even when a landlord ultimately isn't responsible, defending the claim costs money, and that is exactly what liability coverage pays for.
A few habits reduce your exposure:
- Fix structural issues fast and document every repair with dates and photos.
- Ban kegs and large gatherings in the lease, and spell out consequences.
- Inspect between semesters, not just at move-out.
- Carry adequate limits, often paired with an umbrella policy for multi-unit owners.
Carriers like Erie and Frederick Mutual often offer liability limits on dwelling policies that address these student housing concerns. MVP Insurance works with these carriers as an independent agent, so you can compare how each one treats tenant-occupied properties near campus.
Addressing Party and Fire Risks in Student Housing
Kitchen fires are the most common physical claim in student rentals, followed closely by party damage. Students cook late, leave pans unattended and pile pizza boxes next to the stove. Space heaters, overloaded power strips and candles in bedrooms round out the list.
Fire data is getting more detailed across the state. As of January 1, 2026, all Pennsylvania fire departments must report incidents to the National Emergency Response Information System, which supports community risk reduction efforts. Over time, that kind of reporting tends to make loss patterns more visible to local officials and, eventually, to underwriters.
Party damage is a different animal. Think punched drywall, broken doors, red wine on carpet, a cracked toilet tank that floods the basement. Some of this is covered as vandalism or sudden water damage, depending on the policy form, while plenty of it falls under wear and tear or intentional tenant damage, which most policies exclude. Your security deposit is the first line of defense, and Pennsylvania landlords are legally required to return that deposit, minus documented damages, within 30 days of lease termination.
Insurers such as Municipal Mutual and Farmers of McCandless provide coverage options for these dwellings, provided safety measures are enforced. In practice, that means working smoke detectors in every bedroom and hallway, fire extinguishers in the kitchen, and occupancy limits that match local zoning. An underwriter who finds eight students in a house zoned for four may decline a claim or cancel the policy.
Lease Insurance Requirements for Pennsylvania Students
Requiring renters insurance in the lease is one of the simplest ways to protect your own policy. Your landlord coverage protects the building and your liability as an owner. It does not cover a student's laptop, bike or gaming setup, and it shouldn't be the policy absorbing small claims.
Here's a common scenario. A tenant's guest trips over a backpack inside the unit and sprains an ankle. Without renters insurance, that claim lands on you, even though you had nothing to do with it. With a renters policy in place, the tenant's personal liability coverage responds first, and your loss history stays clean.
Renters policies from companies like Progressive or GEICO are typically inexpensive relative to the protection they offer, and they make students responsible for their guests and their own belongings. To make the requirement stick:
- Write a minimum liability amount into the lease.
- Ask to be listed as an interested party so you get notified if the policy lapses.
- Collect proof of coverage before handing over keys.
- Check again at each lease renewal.
Some students may already be covered under a parent's homeowners policy for belongings, but liability for an off-campus apartment is a separate question. A standalone renters policy removes the guesswork.
Comparison of Landlord Insurance Coverage Options
Policy forms vary by carrier, but this table shows how the main options generally handle student rental risks.
| Coverage Type | What It Covers | Student Rental Fit |
|---|---|---|
| Dwelling Fire (DP-1) | Named perils like fire and lightning | Bare minimum, often no liability |
| Dwelling Fire (DP-3) | Open perils on the structure | Stronger fit for student homes |
| Premises Liability | Injuries to tenants and guests | Essential near campus |
| Loss of Rent | Lost income while repairs happen | Valuable for by-the-room leases |
| Umbrella Policy | Extra liability above base limits | Smart for multiple properties |
| Tenant Renters Policy | Tenant belongings and liability | Require it in the lease |
Loss of rent coverage deserves more attention than it gets. If a kitchen fire closes a five-bedroom house for three months, that's a full semester of income from five tenants. Without this coverage, you're paying the mortgage out of pocket while contractors work.
Insuring Properties Near Pitt and Slippery Rock
Pittsburgh and Slippery Rock sit roughly an hour apart, but insuring rentals in each market feels like two different jobs. Oakland rentals face dense, urban liability and theft exposure. Slippery Rock rentals deal with spread-out properties, older farmhouse conversions and longer emergency response distances. MVP Insurance, with its office in Zelienople, sits between the two and understands how carriers view each market differently.
University of Pittsburgh: Urban Liability Concerns
Oakland packs thousands of students into row houses and converted multi-units on narrow streets. Liability is the dominant concern, especially around large spontaneous gatherings. In March 2026, Pittsburgh and Pitt police dispersed an unpermitted gathering of several thousand people on Semple Street to address safety and traffic hazards. Landlords with porches and roof access on streets like that carry real exposure.
Theft and break-ins also run higher in dense neighborhoods. Strong exterior locks, lighting and a renters insurance requirement keep those claims off your policy.
Slippery Rock: Managing Rural Student Rentals
Slippery Rock is a smaller borough, and many student rentals are older homes on larger lots outside town. Fire is the bigger concern here, because the nearest hydrant or station may be farther away, which affects your rating. Wood stoves, aging wiring and outbuildings all draw underwriter questions.
Bonfires and outdoor parties are the Slippery Rock version of the Oakland block party. Set clear lease rules on fire pits and keep detailed photos of the property's condition at every turnover.
Putting a Student Rental Plan Together
The landlords who do well with students treat insurance, lease terms and maintenance as one system. Strong liability limits, a DP-3 style policy, loss of rent coverage and a firm renters insurance requirement cover most of what goes wrong near campus. Add local code compliance, working smoke detectors and enforced occupancy limits, and you've closed the gaps that sink most claims.
If you own rentals near Pitt, Slippery Rock or another Pennsylvania campus, an independent agent can compare how several carriers handle student-occupied homes. You can
start your quote here with MVP Insurance, which has offices in Zelienople, PA and New Springfield, OH. MVP Insurance holds Ohio license #37714, Pennsylvania license #519263, and NPN 10588293.
Pennsylvania Student Rental FAQ
Do I need a special policy for student rentals in PA?
Yes, you need a landlord or dwelling policy, since homeowners insurance doesn't cover rented homes. Tell your agent the property is rented to students so the policy reflects actual use.
Does landlord insurance cover tenant party damage?
Sometimes. Sudden events like vandalism or a burst pipe may be covered, but intentional damage and wear and tear usually are not, so the security deposit often covers that instead.
Can I require my Pitt or Slippery Rock tenants to have insurance?
Yes. Pennsylvania landlords can make renters insurance a lease requirement and ask for proof before move-in.
Search
Recent Posts



MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.