

Owner, MVP Insurance
Coverage
A pontoon parked at a Lake Milton dock and a 24-foot cruiser running out of Sandusky face very different risks. Yet many Ohio owners carry nearly identical boat policies without realizing it. The details that matter most get skimmed at signing: how the hull is valued, where the boat is allowed to go, and what happens when it sits in a barn from November to April.
This guide is written for boaters in the Mahoning Valley and across northeast Ohio. It covers agreed value hull protection, the specific hazards on the reservoirs closest to our New Springfield office, Ohio's boater education rules, Lake Erie navigation limits, and winter storage. The goal is simple. You should be able to read your own declarations page and spot the gaps before a claim exposes them.
Essential Coverage for Ohio Boat Insurance
Ohio boat insurance gives watercraft owners financial protection against two main risks. Liability covers injuries or damage you cause to other people. Physical damage covers your own hull, motor, and trailer. Most policies also add medical payments, uninsured boater coverage, towing, and on-water assistance, so one policy handles both the boat and the people around it.
Many owners assume their homeowners policy already covers the boat. It usually doesn't, or only barely. A typical home policy may cover a small rowboat or a low-horsepower outboard with a limit of a few thousand dollars, and it often provides no liability once you're on the water. Our homeowners insurance options in Ohiocan coordinate with a separate watercraft policy so nothing falls through the middle.
Boats also fit naturally into a broader Ohio personal insurance plan,alongside your auto and umbrella coverage. That setup matters most for liability. If a skier is hurt behind your boat, you want your umbrella policy to sit on top of the boat liability limit. The umbrella can't help if the boat policy underneath it has a limit that's too low.

On this page
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield and Zelienople and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help homeowners, drivers, renters and condo owners, landlords, contractors, restaurant owners, shop owners, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Umbrella
An umbrella policy adds liability protection above the limits on your home and auto policies. One serious accident can cost more than those limits, and the umbrella is what stands between the claim and your savings.
Understanding Agreed Value Hull Coverage
Agreed value is the amount you and the insurer settle on when the policy is written. If the boat is a total loss, that is what gets paid, with no depreciation taken off. Actual cash value works differently. It pays replacement cost minus wear and age, and on a ten-year-old fiberglass runabout that deduction can be painful.
Here's a common scenario. An owner buys a used bowrider for $38,000 and insures it at actual cash value because the premium is lower. Three years later, a fire at the marina destroys it. The adjuster values it at $26,000, minus the deductible. On an agreed value policy, the payout would have been the stated figure.
A few points about agreed value to keep in mind:
- Partial losses still involve depreciation sometimes. Many policies depreciate certain parts, such as canvas, upholstery, and outboard motors, even when the hull itself is on agreed value.
- The value needs updating. Insuring a restored boat at its 2019 value leaves you underinsured in 2026.
- Survey requirements vary. Older or higher-value boats may need a marine survey before an insurer agrees to a number.
As an independent agency, MVP Insurance works with carriers that write agreed value marine coverage, including Erie, Westfield, Progressive, and Hagerty. Hagerty tends to fit classic and wooden boats, while Progressive and Erie handle a lot of everyday fishing boats and pontoons.
Lake Milton, Berlin Lake and Mosquito Lake Exposures
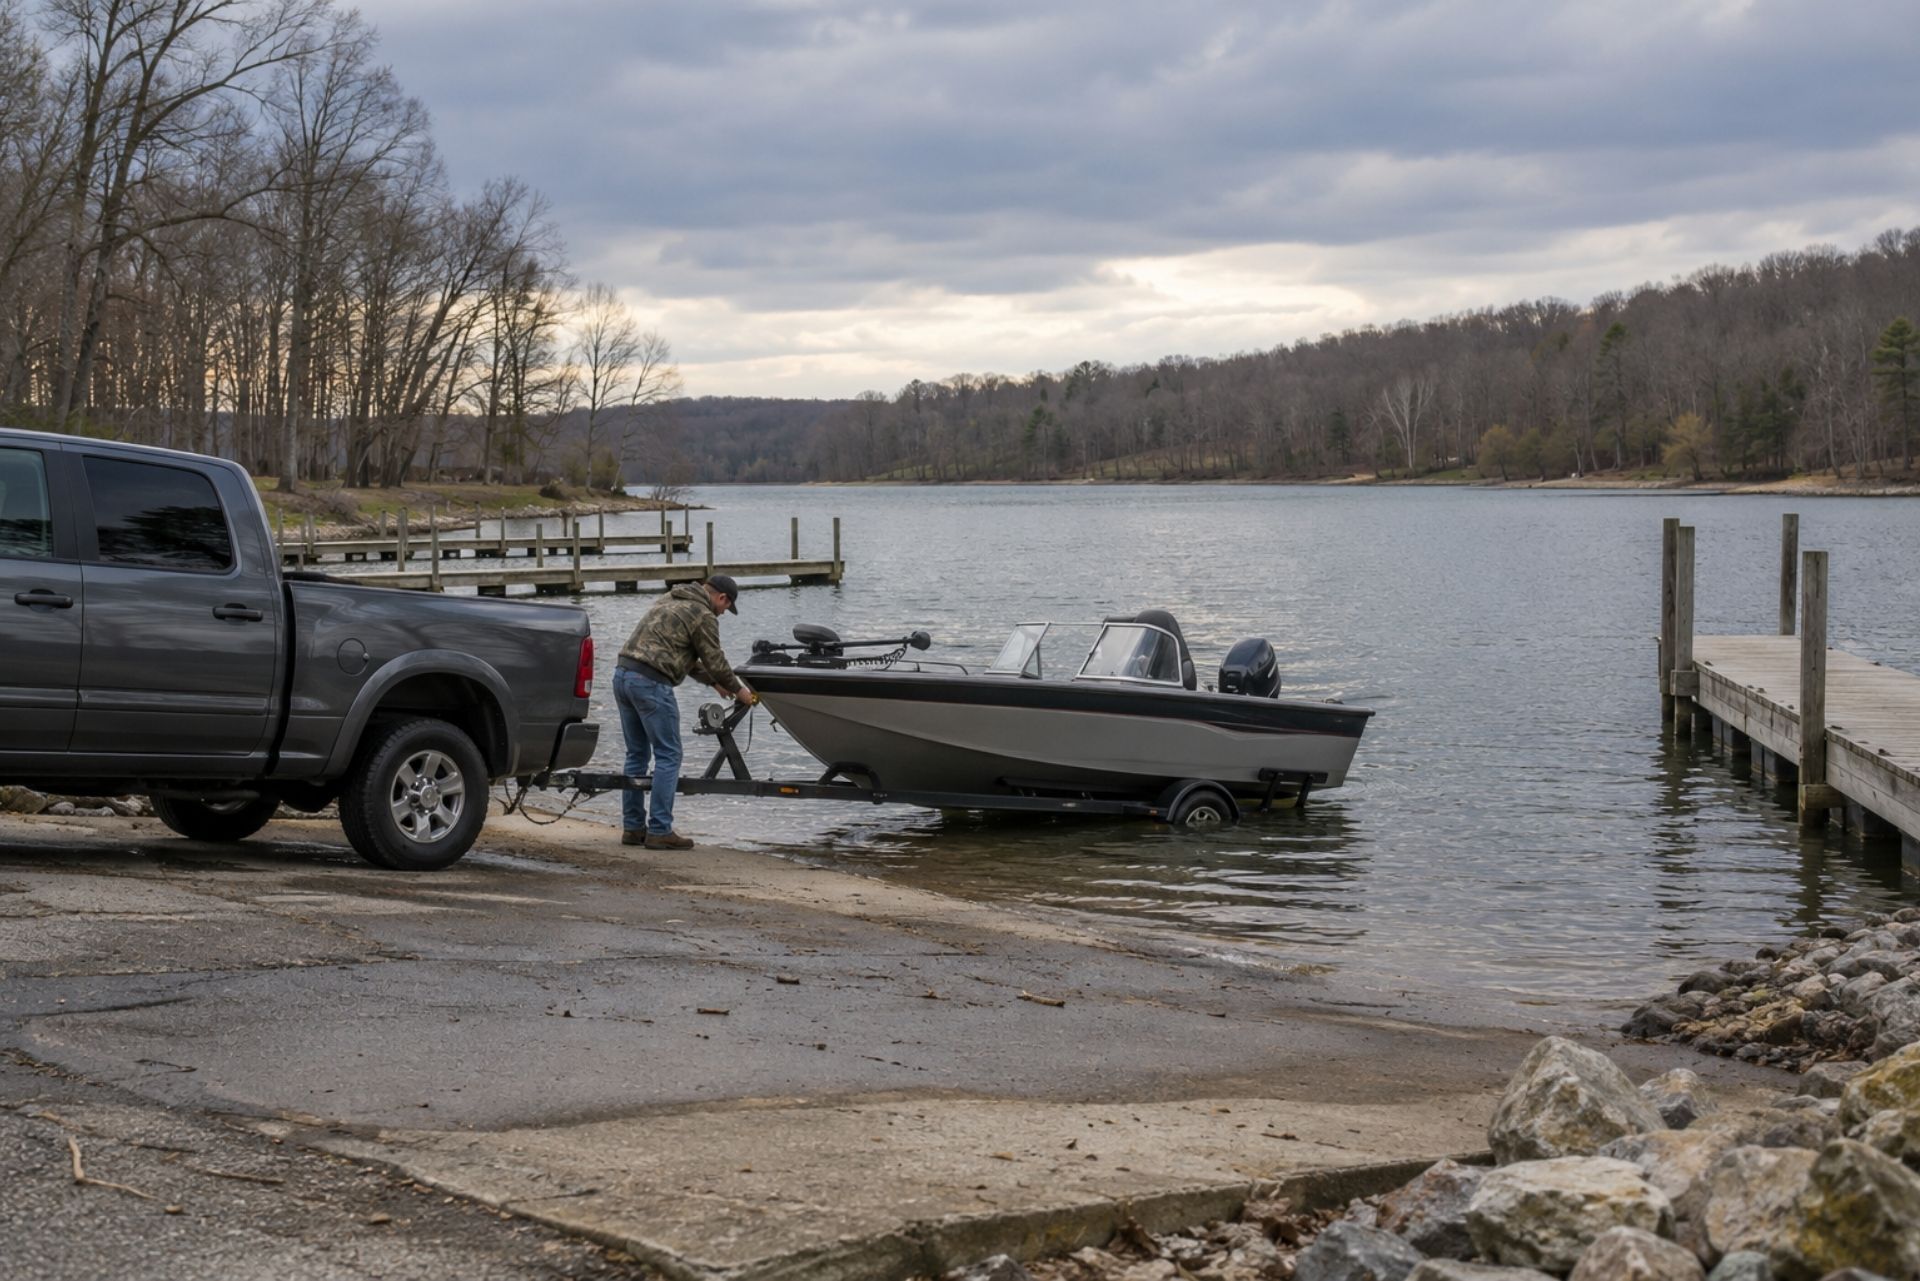
The three reservoirs closest to our New Springfield office each bring their own claim patterns. Shallow water, submerged objects, and heavy summer traffic cause most of the damage we see. Hull and lower-unit claims tend to be far more common here than dramatic collisions.
Lake Milton is narrow in places and gets crowded on summer weekends. The shallower areas toward the north end and near the shorelines punish props and lower units, especially when water levels drop later in the season. Its compact size also packs tubers, skiers, and personal watercraft into tight space, which raises liability exposure.
Berlin Lake is larger, with more open water. Water levels change with reservoir management, and stumps and debris can sit just below the surface in coves. A struck stump can crack a hull or shear a skeg in a second.
Mosquito Creek Lake is wide and shallow across large stretches, which means wind can build a chop quickly. Fishing boats working the shallow flats regularly find bottom they didn't expect. If you boat on these lakes, consider a lower deductible on lower-unit damage, and make sure your towing coverage is set at a realistic level.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
Ohio Boater Education Rules and Requirements
The Ohio DNR requires boater education for operators born on or after January 1, 1982. Under Ohio Revised Code 1547.05, those operators must complete an approved boater education course to run powercraft over 10 horsepower. As of this writing, that is the general rule. Exemptions exist for certain licensed operators and other narrow situations.
The penalty is real. Operating without a required certificate is a fourth-degree misdemeanor that can carry a fine of up to $250. Renters have a newer option as well. Since June 2026, renters born after 1982 can typically meet the requirement by passing an abbreviated online exam that's valid only for the rental period.
There's also an insurance angle that people overlook. Many carriers offer premium credits for completing a boating safety course. Insurers also ask who operates the boat, so an uncertified 19-year-old taking the family boat out alone is worth discussing with your agent before summer rather than after an accident.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Deductibles are where you can trim premium without gutting protection. Industry voices suggest raising deductibles to $1,000 to offset higher urban base rates. Just make sure you can actually pay that amount after a February break-in.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Protecting Older Housing Stock and Garaged Vehicles
Cleveland's older housing stock creates an auto insurance angle people don't expect. Many homes in Ohio City, Tremont, Slavic Village, and the inner-ring suburbs have detached garages built decades ago, often narrow, aging, or unusable for modern vehicles. That pushes cars onto driveways and streets, which raises theft and weather exposure.
If your garage does house your car, its condition matters. A collapsed roof from heavy snow damages the vehicle (a comprehensive auto claim) and the structure (a homeowners claim). Coordinating both policies avoids finger-pointing between coverages, and Cleveland residents can save up to 20% by bundling auto with homeowners or renters policies.
Review your homeowners insurance options in Cleveland alongside your Ohio car insurance coverage so the gaps between them close.
Lake Erie Navigation Limits and Coastal Risks
Every boat policy defines where the vessel is covered, and that area is called the navigation limit. Leave it, and coverage can lapse for the trip. On Lake Erie, this matters more than most inland owners realize.
Standard recreational marine policies for the lake often define navigation limits as coastal waters north of 40° North Latitude. Some inland-only policies written for reservoir boats exclude the Great Lakes entirely. If you trailer your boat from Mosquito Creek to Port Clinton for a walleye weekend, your policy needs to include Lake Erie by name or by definition.
Canada is the other trap. Boaters entering Canadian waters must report to the Canada Border Services Agency immediately upon landing, anchoring, or mooring. Failing to report can lead to vessel seizure and may void insurance coverage for the trip. Before crossing toward Pelee Island, make sure your policy extends into Canadian waters.
Erie's weather also changes fast. Policies built for the lake usually include higher towing limits and fuel spill liability, both of which are worth having.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
These suggestions are a starting point, not a universal rule. Your agent can tailor them to your assets, vehicles, and budget.
Winter Storage and Lay-up Periods
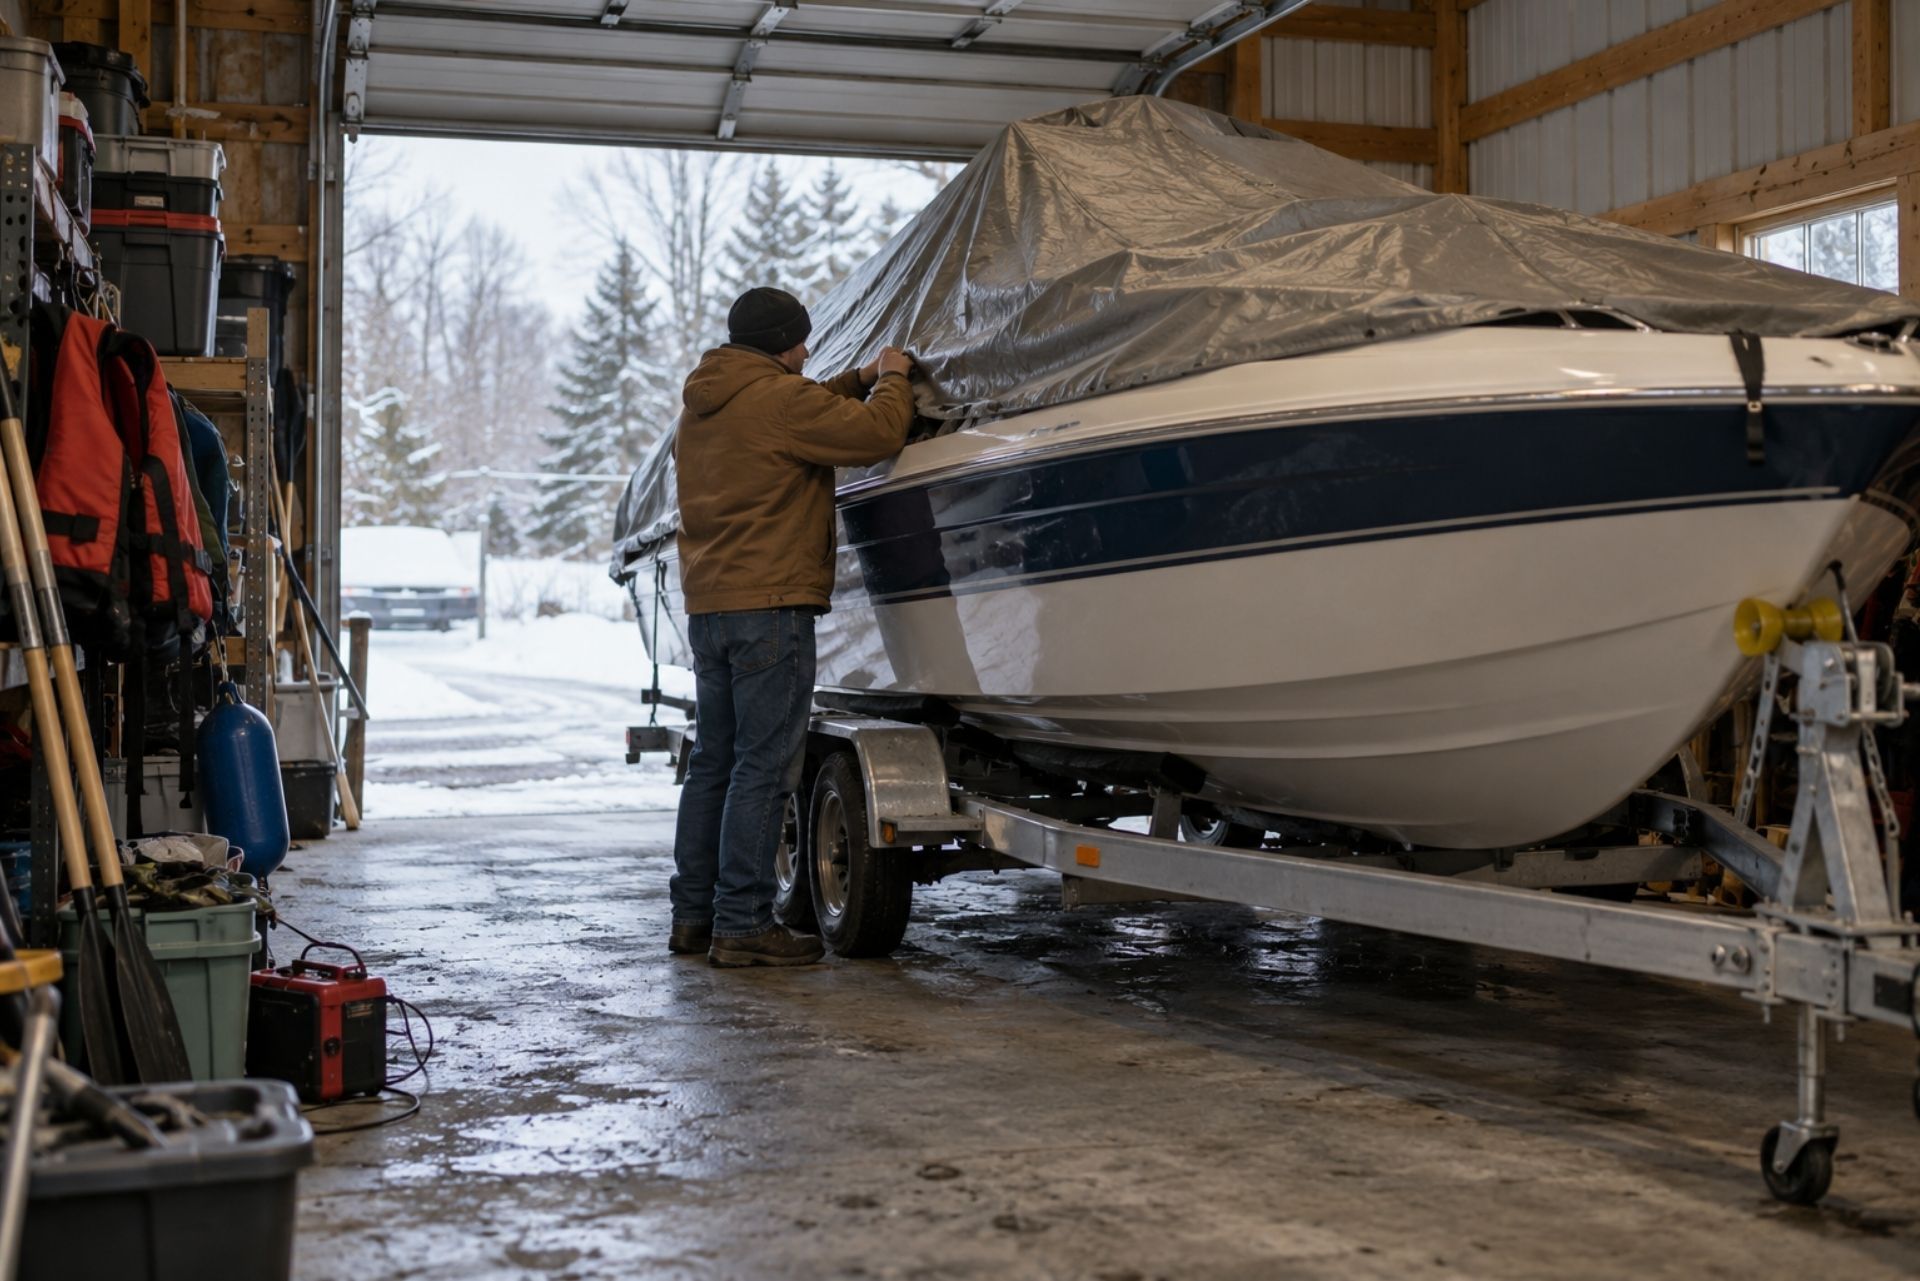
Most Ohio boat policies include a lay-up period, a stretch of months when the boat is expected to be out of use in exchange for a lower premium. It typically runs from November 1 to April 1. Using the boat during that window without notifying your carrier can jeopardize a claim.
What surprises people is that lay-up does not mean "no coverage." Your boat still needs protection while it sits. Winter claims we commonly see include:
- Freeze damage to engine blocks and outdrives that weren't properly winterized (often excluded as a maintenance issue)
- Snow load collapse of shrink wrap, covers, or storage building roofs
- Theft of outboards, electronics, and entire trailered boats from driveways
- Fire at storage facilities, which can affect dozens of boats at once
Some owners drop coverage completely in the off-season to save money. That's a gamble that rarely pays off. A comprehensive-only lay-up policy keeps the hull protected for a fraction of the in-season cost. If your boat is stored at a marina, ask whether the facility's insurance protects your boat. Usually it covers only their own negligence.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
How Stacking Protects Multi-Vehicle Households
Say your household insures three cars, each with $50,000 in underinsured motorist coverage. Stacked, an injured family member could typically access up to $150,000. Unstacked, they get $50,000.
Here's where stacking usually makes the most sense:
- Households with two or more vehicles, since each added car increases the available limit
- Families without strong disability coverage who would struggle if a breadwinner couldn't work
- Drivers who chose limited tort, because uninsured motorist claims can help offset restricted lawsuit rights
- Commuters on busy corridors where uninsured drivers are more common
Single-car owners get less benefit from stacking, so unstacked may be reasonable there.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Comparing Ohio Boat Insurance Options
Different boats need different structures. A $9,000 jon boat doesn't need the same policy as a $90,000 cruiser running Lake Erie. Comparing several carriers side by side is where an independent agency earns its keep.
Coverage Type Comparison Table
| Coverage | What It Pays For | Who Needs It Most |
|---|---|---|
| Agreed Value Hull | Set amount on total loss, no depreciation | Newer, classic, or high-value boats |
| Actual Cash Value Hull | Value minus depreciation | Older, lower-value boats |
| Liability | Injuries or damage you cause others | Every boat owner |
| Uninsured Boater | Your injuries caused by uninsured operators | Busy lakes like Milton |
| Towing/Assistance | On-water tows, jump starts, fuel delivery | Lake Erie and large reservoirs |
| Lay-up/Storage | Fire, theft, collapse during off-season | Owners who store Nov to Apr |
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
Where you live
What you drive and own
Vehicle type, repair cost and safety features drive the auto premium. For the home, the rebuild cost, roof age, and updates to wiring, plumbing and heating carry the most weight.
Claims and credit where allowed
Three to five years of claims follow you from carrier to carrier. Both Ohio and Pennsylvania allow insurers to use a credit-based insurance score within state rules, so improving it over time can lower your premium.
| Situation | Coverages usually carried | What to check | Main cost drivers |
|---|---|---|---|
| First home | Homeowners, auto, often umbrella | Rebuild cost, deductible, lender requirements | Age and construction of the home, location, claims history |
| Young driver in the household | Auto with the teen listed, umbrella | Good-student and driver-training discounts, liability limits | Driver age and record, vehicle type, annual miles |
| Rental condo | Condo unit-owners policy with loss of rent | Where the association policy stops, tenant liability | Unit value, association deductible, rental use |
| Renter | Renters policy | Replacement cost on belongings, liability limit | Belongings value, location, deductible |
| Lake toys | Boat or watercraft policy, umbrella | Trailer and gear coverage, navigation limits | Horsepower, hull value, where it is stored and used |
| Motorcycle or RV | Motorcycle or RV policy, auto | Custom parts, roadside and vacation liability | Vehicle value, riding season, storage |
| Growing family | Term life, home, auto, umbrella | Coverage amount against mortgage and income | Age, health, term length, amount |
These suggestions are a starting point, not a universal rule. Your agent can tailor them to your assets, vehicles, and budget.
Frequently Asked Questions About Boating in Ohio
Do I need boat insurance to use Lake Milton or Berlin Lake? Ohio doesn't generally require boat insurance by state law, but marinas and lenders often do. Even without a requirement, one liability claim can cost far more than years of premiums
Does my boater education certificate lower my insurance premium? Often, yes. Many carriers give a credit for completing an approved safety course, so mention it when you request a quote.
Who has to take Ohio's boater education course? Generally, anyone born on or after January 1, 1982, who operates a powercraft over 10 horsepower. Renters may have a shorter online option.
Can I insure an older boat with American Modern or Foremost? Both carriers write specialty watercraft coverage, including older boats and personal watercraft. MVP Insurance works with both as an independent agent and can compare them against other options.
Is my boat covered if I take it to Canada on Lake Erie? Only if your navigation limits include Canadian waters and you follow border reporting rules. Ask before the trip, not after.
Do I need insurance while my boat is stored for winter? Yes. Fire, theft, and snow collapse still happen in the off-season, and a lay-up policy covers those risks at a lower cost.
Written By
David Varrati
Owner, MVP Insurance
Owner, MVP Insurance
On this page
How Stacking Protects Multi-Vehicle Households
Say your household insures three cars, each with $50,000 in underinsured motorist coverage. Stacked, an injured family member could typically access up to $150,000. Unstacked, they get $50,000.
Here's where stacking usually makes the most sense:
- Households with two or more vehicles, since each added car increases the available limit
- Families without strong disability coverage who would struggle if a breadwinner couldn't work
- Drivers who chose limited tort, because uninsured motorist claims can help offset restricted lawsuit rights
- Commuters on busy corridors where uninsured drivers are more common
Single-car owners get less benefit from stacking, so unstacked may be reasonable there.
04
Review, bind, and relax
Once you approve, we bind the policies, send your ID cards and set a reminder for next year's review.
Contact MVP Insurance for Your Watercraft Quote
The right boat policy comes down to a few decisions: agreed value versus actual cash value, navigation limits that match where you actually boat, honest operator information, and winter protection that doesn't lapse. Get those right, and a stump on Berlin Lake or a snow-crushed shed becomes an inconvenience instead of a financial hit.
MVP Insurance was founded in 2008 by Josh Medure and David Varrati. As an independent agency, we work for you rather than any one carrier, and we compare policies so you don't have to. If you're ready to see your options, start your quoteonline or call either office.
- New Springfield, OH:13823 Grant St, New Springfield, OH 44443, (330) 707-9055
- Zelienople, PA:108 E Grandview Ave, Zelienople, PA 16063, (724) 453-1122
MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293. Talk to Josh, David, or our team before launch day, so your boat is covered from the first trip of the season to the last.
MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.
Personal Insurance in Ohio & Pennsylvania
Coverage for your home, your car, and your family
Protect the everyday things that mean the most to you.
Homeowners Insurance
Your home is one of your most valuable assets. We compare carriers to protect the house, your belongings, and your liability.
Car Insurance
We proactively shop the market to find the best combination of coverage and price for every car in your driveway.
Renters Insurance
Own a condo or rent your home? We insure your unit, your belongings, and your personal liability at a fair rate.
Umbrella Insurance
Extra liability protection above your home and auto policies. Large coverage limits for a small added cost each year.
Life Insurance
Protect the people who rely on you most, so they can keep their home and lifestyle if the unexpected happens.
Flood Insurance
Standard home policies do not cover flooding. We help you add flood coverage through the NFIP or a private carrier before the water rises.
Business Insurance in Ohio & Pennsylvania
No matter how big or small your business, we protect it
Practical coverage for your people, your property, and the work you do.

General Liability

Business Owners Policy

Professional Liability

Commercial Property

Workers Compensation

Commercial Auto
Industries We Serve
Insurance built around the work you do
Every industry carries different risks. We know the coverage each one needs and shop the carriers that write it well.

Contractors Insurance
General contractors, remodelers, roofers, and trade crews. We cover the liability, tools, vehicles, and workers your jobs depend on.

Plumber Insurance
Water damage claims follow plumbers everywhere. We cover your liability, your tools, your van, and your crew, job after job.

Restaurant Insurance
Kitchens, bars, and cafes face fire, spoilage, and slip risks. We package property, liability, and liquor coverage in one plan.
5-Star Rated on Google
What our clients say
Our clients say it best. Here is what they share about working with Josh, Dave, and the MVP team.
Contractors & Tradesmen
General contractors, roofers, electricians and plumbers. We cover liability, tools, vehicles and crews so every job stays protected.
Insurance Tips & News
Insurance tips for Ohio and Pennsylvania families and businesses
Practical ideas for protecting what matters to you.



Insurance Questions, Answered
Questions our clients ask
A little clarity can make your next step easier.
What does an independent insurance agency do?
An independent agency works with multiple insurance companies. We compare your options, explain the differences, and help you choose coverage that fits your needs.
Can MVP Insurance quote both my home and auto?
Yes. We can compare home and auto insurance options together. We explain available discounts and check how the policies work together.
Do you insure businesses in Ohio and Pennsylvania?
Yes. We help businesses in both states compare options for property, liability, employees, and commercial vehicles. The right policy depends on your work and the risks involved.
How do I import my current policy for a quote?
Use our Canopy policy import link to share your current policy information. Our team can then review your existing coverage and compare options with you.
How do I report a claim or make a payment?
Visit our Client Center for billing and claims information. You can also call either office for help finding the right carrier contact.
How often should I review my insurance?
Review your coverage each year and after a major change, such as a move, new vehicle, or business expansion. Tell us what changed so we can help you check your protection.


Covington office, Monday through Friday
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461
Request Your Free Quote
Let's make insurance simple for you
Tell us what you need. We will help you explore your options.