

Pennsylvania teens move from a learner's permit to a junior license to a senior license. Each step requires a minimum amount of time, practice, or clean driving before the next one unlocks. Here's what each stage actually requires and what it means at home.
CG 20 37: Coverage After the Project is Finished
Can my 16-year-old drive their friends home from school in Pennsylvania? During the first six months of a junior license, they can carry only one passenger under 18 who isn't an immediate family member, unless a parent or guardian is in the car. After that window, the limit eases if your teen has stayed violation-free.
Does a teen with a learner's permit need to be on my car insurance? It depends on the carrier. Some require permit holders to be listed, and others don't rate them until they're licensed. Tell your agent when the permit is issued so there's no gap if something happens.
Can a junior license holder drive home from work after 11 PM? Yes. Pennsylvania's curfew includes an exception for travel to and from employment. Your teen should keep proof of their work schedule in the car in case they're stopped.
Pennsylvania's licensing rules work because they ease teens into risk instead of handing them full privileges on day one. Supervised hours, passenger caps, and the overnight curfew all target the situations where new drivers get hurt most. For families, those same rules shape the insurance conversation. A clean junior year, solid liability limits, and the right car assignment can keep your teen safer and your premium more manageable.
If your teen's road test is coming up, now is a good moment to see how different carriers would price your household. MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH. We compare policies across multiple carriers so you don't have to. When you're ready, you can start your quote here, and we'll walk you through the options. MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
Pennsylvania still offers homeowners insurance below the national average, but recent increases have been steep, and Western PA homeowners have felt it through storms and rising rebuilding costs. Your location sets the starting point. Your deductible, your roof and home systems, and how you use your policy decide much of the rest.
The most useful step is seeing real numbers side by side instead of accepting a single renewal at face value. MVP Insurance is an independent agency with offices in Zelienople, PA and New Springfield, OH, and the team compares multiple carriers so you don't have to. When you're ready, start your quote here and get a clearer picture of what your home should cost to insure.
MVP Insurance is licensed in Ohio (license #37714) and Pennsylvania (license #519263), NPN 10588293.
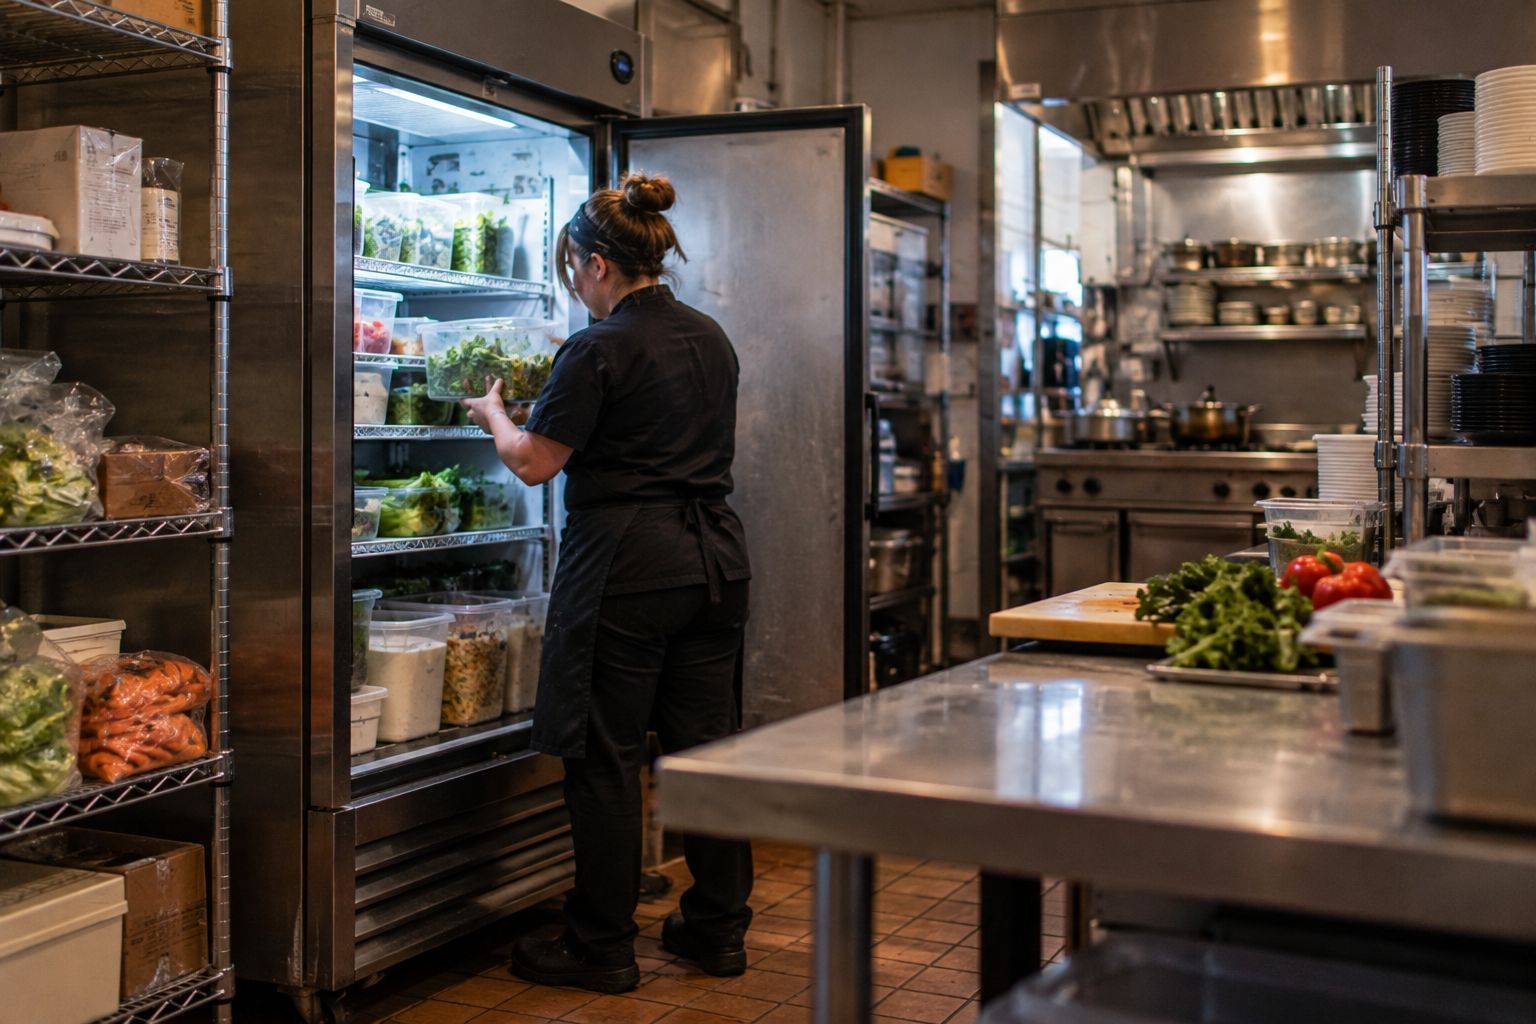
Every summer storm in Pennsylvania threatens to wipe out a restaurant's walk-in cooler overnight. The right insurance can turn that loss into a reimbursed expense instead of a cash-flow crisis. Most of that protection, though, depends on endorsements many owners have never read.
Protecting Pennsylvania Restaurants from Food Spoilage and Power Outage Risks
Food spoilage and power outage coverage for Pennsylvania restaurants pays for perishable inventory lost when refrigeration fails from a mechanical breakdown or when utility power goes out. It is usually added as an endorsement to a pennsylvania commercial property insurance policy rather than included automatically.
MVP Insurance, an independent agency with offices in Zelienople, PA and New Springfield, OH, often sees restaurant owners assume their property policy already handles this. It frequently doesn't, or it handles only part of it. A standard property form responds well to fire, wind, or theft. A compressor that quietly dies at 2 a.m., or a substation failure three miles away, is a different story.
The risk is growing. In 2025, 2.88 million Pennsylvania customers were affected by significant outages, and 94.5% of reportable outages were weather-related. Looking ahead, the PJM grid serving the state is projected to be six times less reliable by 2030 as data center demand climbs.
The Role of Equipment Breakdown Coverage in Preventing Spoilage
Equipment breakdown coverage pays when your own refrigerators, freezers, or electrical systems fail from internal causes such as motor burnout, a short circuit, or a failed compressor. Standard property insurance usually covers only external events like fire or wind. That gap is why a burned-out walk-in motor often gets denied under a basic policy.
A typical breakdown claim looks like this. A reach-in freezer's compressor fails on a Friday night, and by Saturday morning the internal temperature has climbed past safe levels. Equipment breakdown pays to repair or replace the unit. When paired with spoilage coverage, it also pays for the chicken, seafood, and prepared sauces you had to throw out.
Carriers such as Erie, Westfield, and Frederick Mutual often offer equipment breakdown protection for restaurants, either built into a business owner's policy or as an add-on. MVP works with these carriers as an independent agent, which makes it easier to compare how each one treats spoilage after a breakdown. Some policies include a small spoilage amount inside the breakdown endorsement. Others require a separate spoilage form.
How Utility Interruption Coverage Handles Off-Premises Power Failures
Utility interruption coverage applies when the outage starts somewhere other than your restaurant. A downed line on Route 19, a transformer failure on your block, or storm damage to a regional substation all qualify. Without it, an off-premises outage can leave a full cooler uninsured, even if you carry equipment breakdown.
This catches a lot of owners off guard. The standard ISO Spoilage Coverage endorsement (CP 04 40) covers perishable stock lost to power outages, but "Power Outage" must be specifically selected on the schedule to extend coverage to off-premises utility failures. If that box isn't checked, the endorsement may only respond to breakdowns or contamination.
Timing matters too. Many Pennsylvania utility interruption endorsements include a 24-hour waiting period before business income coverage triggers, while direct spoilage damage usually applies right away. So a six-hour outage might pay for spoiled food but not for the dinner service you lost. As of this writing, annual premiums for utility interruption time element coverage in Pennsylvania typically run from about $952 to $3,584, depending on location and grid stability.
Determining Appropriate Spoilage Limits for Your Inventory
Set your spoilage limit based on the most perishable inventory you ever hold, not your average week. Standard business owner's policies in Pennsylvania typically include a default spoilage sub-limit of $10,000 to $25,000. That can fall short quickly during busy periods.
Consider the weeks when your coolers are packed. Thanksgiving and Christmas catering, Penn State home football weekends, Pittsburgh Steelers playoff runs, summer festival season, and graduation parties all push inventory well above normal. A restaurant holding $14,000 of product on a typical Tuesday might hold $35,000 the Thursday before a holiday weekend.
A simple way to size your limit:
- Pull invoices from your three heaviest delivery weeks of the past year.
- Total the perishables on hand at peak, including dairy, proteins, produce, and prepped items.
- Add high-value stock such as aged beef, seafood, or temperature-sensitive wine.
- Build in a cushion for menu changes and rising food costs.
Fine-dining operations with aged meats or extensive wine programs should consider spoilage limits of $50,000 or more to avoid being underinsured.
Comparison of Restaurant Coverage Options
| Coverage | What Triggers It | Typical Gap |
|---|---|---|
| Basic property | Fire, wind, theft | No internal breakdown |
| Equipment breakdown | Motor burnout, short circuit | Off-site outages |
| Spoilage endorsement | Breakdown, contamination | Power outage must be selected |
| Utility interruption | Off-premises power loss | Income waiting period |
Common Exclusions and Policy Requirements for PA Business Owners
The most common exclusions involve outages you caused or equipment you neglected. Insurers generally won't pay if someone manually shut off power, if the utility cut service for nonpayment, or if a unit failed because of skipped maintenance. Planned outages announced in advance by the utility may also be excluded.
Maintenance records matter more than many owners expect. If an adjuster sees a condenser coil caked with grease and no service history, a breakdown claim can turn into a coverage dispute. Keep dated invoices from your refrigeration technician and a simple cleaning log.
Temperature documentation is the other big issue. As of this writing, some carriers such as Liberty Mutual or NEXT may require specific temperature monitoring, like alarmed sensors or recorded logs, as a condition of spoilage coverage. Those records also protect you with health inspectors. October 2026 inspections in Lancaster County led to the voluntary destruction of food held at 50°F, above the 41°F legal limit. A logged timeline shows exactly when product crossed that threshold.
Policy language can also change faster now. The Pennsylvania Insurance Department's Notice 2026-07 deregulated rate and form filing requirements for property and casualty lines, so read your renewal documents closely.
Frequently Asked Questions About Restaurant Spoilage Insurance
Real losses rarely look neat. After a 2026 storm, Amici Pizza owner Vinny Epifanotto lost thousands of dollars in food and said, "I don't think I've ever seen a storm like this... it caught me by surprise." Nationally, outages have increased by 60% over the last decade, and some operators have lost six figures in sales during long events. These are the questions owners ask most.
Does restaurant insurance cover food lost in a power outage? Only if your policy includes spoilage coverage with the power outage option selected or a utility interruption endorsement. A basic property policy usually won't pay for food lost when the grid fails.
What's the difference between equipment breakdown and utility interruption? Equipment breakdown covers failures inside your building, like a dead compressor. Utility interruption covers outages that start off-site, like a downed power line or transformer failure.
How much spoilage coverage does a Pennsylvania restaurant need? Base it on your peak perishable inventory, such as holiday weekends. Many default limits of $10,000 to $25,000 are too low for busy or high-end kitchens.
Spoilage protection comes down to three questions: Does your policy cover internal breakdowns? Does it cover outages from the grid? Does your limit match your fullest cooler? A gap in any one of them can leave a restaurant paying out of pocket after a single summer storm. Before the next heavy-inventory season, review your spoilage limit, confirm the power outage selection, and organize your maintenance and temperature records.
If you'd like a second set of eyes on your current coverage, MVP Insurance can compare restaurant options from multiple carriers and explain where the gaps are. You can start your quote online or reach the team in Zelienople, PA or New Springfield, OH. MVP Insurance is licensed in Ohio (#37714) and Pennsylvania (#519263), NPN 10588293.
Search
Recent Posts



MVP Insurance is a local, independent agency, licensed to serve individuals and businesses across Ohio and Pennsylvania.
We serve clients from our offices in New Springfield, Ohio and Zelienople, Pennsylvania and throughout Northeast Ohio and Western Pennsylvania, working with multiple carriers to help contractors, landlords and real estate investors, restaurants, retail shops, auto repair shops, professional offices and many other personal and commercial clients find coverage that fits.
Our Owners
Two friends who started an agency
Owner
Joshua Medure
I am a Penn State marketing graduate with more than ten years in insurance. My childhood friend David and I started MVP Insurance in Northeast Ohio because we wanted the people around us to have an agency that gives honest advice, real choices and someone who picks up the phone. I lead the agency’s insurance strategy, which means I read the policies so our clients do not have to. Away from the office, I coach youth football.


About the Author
David Varrati
Owner, MVP Insurance
I started MVP Insurance with my childhood friend Josh because we wanted people in Northeast Ohio and Western Pennsylvania to have an agency that explains things plainly and picks up the phone. I studied Political Science at Slippery Rock University and have spent more than ten years helping families and individuals protect what matters to them. When I am not in the office, you will find me coaching youth sports.